PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154391

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154391
Waste Pre-processing For Alternate Fuel and Raw Materials (AFR) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the waste pre-processing for alternate fuel and raw materials market size is expected to increase from USD 2.02 billion in 2025 to USD 2.25 billion in 2026 and reach USD 3.33 billion by 2031, at a CAGR of 8.14% over 2026-2031.
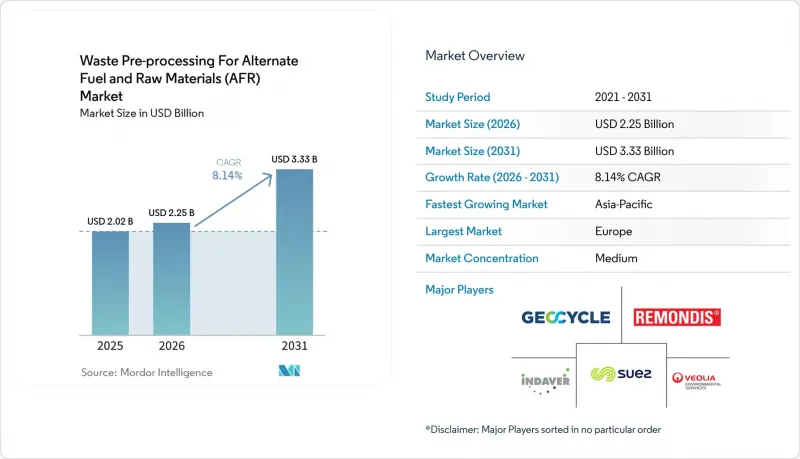
Global Waste Pre-processing For Alternate Fuel and Raw Materials (AFR) Market Trends and Insights
Fossil-Fuel Substitution and Cement Decarbonization
Fuel combustion accounted for 30% of cement production emissions, making fuel replacement a direct operating priority for cement plants. The waste pre-processing for alternative fuels and raw materials market benefits when plants require engineered fuels instead of irregular waste deliveries. The GCCA states that fuel quality requirements now address calorific value, alkali content, chloride limits, and moisture control. Heidelberg Materials set a target above 50% for alternative fuel use and plans for more than 30% of its clinker plants to achieve at least 45% AFR use. These targets create demand for suppliers that can provide high-calorific solid recovered fuel at consistent specifications. Investment in feeding and dosing equipment also supports multi-year arrangements rather than one-time waste transactions.
Landfill Diversion and Circular-Economy Mandates
Europe's landfill rules are directing more residual material toward recovery and co-processing routes. The Waste Framework Directive supports prevention, reuse, recycling, recovery, and disposal in that order. The waste pre-processing for alternative fuels and raw materials market gains access to larger local volumes when landfilling becomes more restricted. Regulation 2026/1703 restricts exports of mixed municipal waste for recovery, which reduces overseas outlets for residual waste. France also updated requirements related to solid recovered fuel production during 2025. These rules encourage facilities that can turn difficult municipal and industrial streams into compliant fuels. Higher costs for competing disposal routes can improve the economics of processing lower-calorific sludge and construction residues. This increases the range of materials that can enter the waste pre-processing for alternative fuels and raw materials market when technical controls are in place.
Feedstock Variability and Kiln-Stability Risk
Variable moisture, calorific value, and ash composition can prevent residual waste from meeting main-burner fuel requirements. Research on kiln burner technology identifies moisture below 10% as necessary for stable main-burner combustion. High-moisture fuel can destabilize the calciner and cause uneven clinker burning. This makes drying and moisture conditioning necessary for many municipal solid waste and agricultural residue streams. Operators without biodrying or thermal drying equipment are less able to compete for premium fuel contracts in the waste pre-processing for alternative fuels and raw materials market. The need for tighter quality control can narrow margins when incoming materials change in composition.
Other drivers and restraints analyzed in the detailed report include:
- Demand for Consistent High-Calorific Fuels and Energy Recovery Capacity
- AI-Enabled Sorting, Traceability, and Alternative Raw Materials Integration
- High Pre-Processing Capital, Logistics, and Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Municipal solid waste held 33.4% of the waste pre-processing for alternative fuels and raw materials market share in 2025. Its large volume and proximity to urban collection systems support the location of processing facilities near municipal waste flows. Industrial and commercial waste remains a useful input because its composition is often more uniform and less contaminated. That uniformity can reduce the processing steps needed to produce higher-calorific solid recovered fuel. Construction and demolition wood is emerging as a pellet feedstock for cement kilns. The Construction and Demolition Recycling Association worked with the American Cement Association and the EPA during 2025 and 2026 on non-hazardous secondary material classification for clean cellulosic biomass. Waste tires retain a heat value near that of coal after shredding and steel separation. Sewage sludge requires biodrying to reach an energy density suitable for co-firing. These inputs provide stable demand but have lower projected growth than biomass residues.
The waste pre-processing for alternative fuels and raw materials market size for biomass and agricultural waste is projected to grow at a 9.3% CAGR through 2031. Agricultural residues can broaden the feedstock base for cement producers in Asia-Pacific and Latin America. A 2025 study found that biomass and agricultural fuels could provide up to 70% of coal's energy content and showed low HCl and dioxin emissions under the tested conditions. Holcim Mexico commissioned a biomass facility in Colima during August 2026. The facility dries 220 tonnes per day of sugar bagasse with recovered kiln heat before grinding it for co-firing. China's T/CIECCPA 129-2026 standard sets requirements for calorific value, moisture, ash composition, and particle size for biomass fuels used in cement kilns. Such requirements favor facilities that can manage seasonal variation in agricultural inputs. They also shift biomass supply toward engineered fuel specifications rather than untreated residue delivery.
Complete Report Scope:
- By Waste Type
- Municipal Solid Waste (MSW)
- Industrial Waste
- Commercial Waste
- Construction and Demolition Waste
- Sewage Sludge
- Waste Tires
- Biomass and Agricultural Waste
- Other Waste Types
- By Pre-processing Technology
- Mechanical Sorting and Segregation
- Shredding and Size Reduction
- Screening and Classification
- Magnetic and Eddy-Current Separation
- Air and Ballistic Separation
- Optical and Sensor-Based Sorting
- Mechanical-Biological Treatment and Biodrying
- Drying and Moisture Conditioning
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Italy
- Spain
- United Kingdom
- Poland
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Vietnam
- Thailand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Morocco
- Rest of Middle East and Africa
- North America
Geography Analysis
Europe accounted for 37.4% of the waste pre-processing for alternative fuels and raw materials market share in 2025. The region has established rules and commercial arrangements for waste co-processing. Regulation 2026/1703 restricts mixed municipal waste exports for recovery and redirects residual material to domestic outlets. Austria, Belgium, and Germany have some of the highest cement substitution rates. Poland, Spain, and Italy remain below Europe's 58% average alternative fuel rate, leaving room for new processing capacity. Paprec and Vicat opened the EUR 15.4 million ALTereNATIVE plant in France during July 2026. The facility illustrates the regional supply-chain model that links processing capacity with a local cement offtaker.
Asia-Pacific is projected to grow at a 9.5% CAGR through 2031. The waste pre-processing for alternative fuels and raw materials market is supported by increasing waste volumes and cement capacity across China, India, Indonesia, and Vietnam, although supply quality still depends on local collection and segregation systems. KHD commissioned a second Pyrorotor system at Conch Group's Baoshan plant during December 2025. The installation processes shredded biomass and municipal solid waste at 18 tonnes per hour under high-moisture conditions. Indonesia's program for waste-to-energy projects can expand the formal infrastructure needed for prepared fuels. India generates 150,000 tonnes of municipal solid waste each day, but segregation gaps and variable feedstock quality limit near-term cement use. The region's opportunity depends on improving collection, sorting, and quality control before material reaches cement plants.
South America and the Middle East and Africa are smaller regions with meaningful potential. Geocycle planned USD 125 million of Latin American investment through 2030, supported by 14 facilities that processed nearly 1 million tonnes of waste during 2025. This model combines cement operations and waste processing within one supply chain. Saudi Arabia and the UAE support policy frameworks for waste as an alternative fuel through the Cement and Concrete Breakthrough initiative. Morocco also offers potential as cement production and municipal solid waste volumes grow. Research found that locally sourced agricultural waste ashes could reduce the carbon footprint of African cement by up to 40%. This can link fuel preparation with alternative raw material use in future projects.
- Andusia Holdings Limited
- Beauparc Utilities Holdings Limited
- Biffa plc
- CEMEX, S.A.B. de C.V.
- EEW Energy from Waste GmbH
- Enva Group Limited
- FCC Environment (UK) Limited
- Geminor AS
- Geocycle (Deutschland) GmbH
- Heidelberg Materials AG
- Holcim Ltd.
- Indaver NV
- Paprec Group S.A.S. (Paprec)
- PreZero International GmbH
- Ragn-Sells AB
- REMONDIS SE & Co. KG
- Renewi plc (Renewi)
- SUEZ S.A.
- Veolia Environnement SA
- Vicat SA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Fossil-Fuel Substitution and Cement Decarbonization
- 4.2.2 Landfill Diversion and Circular-Economy Mandates
- 4.2.3 Demand for Consistent High-Calorific Fuels
- 4.2.4 Expansion of Waste-to-Energy and CHP Capacity
- 4.2.5 AI-Enabled Sorting and Digital Fuel Traceability
- 4.2.6 Integration of Alternative Raw Materials With Fuel Pre-Processing
- 4.3 Market Restraints
- 4.3.1 Feedstock Variability and Kiln-Stability Risk
- 4.3.2 High Pre-Processing Capital and Logistics Costs
- 4.3.3 Competition for High-Calorific Residual Waste
- 4.3.4 Fragmented Permitting and Cross-Border Waste Rules
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Waste Type
- 5.1.1 Municipal Solid Waste (MSW)
- 5.1.2 Industrial Waste
- 5.1.3 Commercial Waste
- 5.1.4 Construction and Demolition Waste
- 5.1.5 Sewage Sludge
- 5.1.6 Waste Tires
- 5.1.7 Biomass and Agricultural Waste
- 5.1.8 Other Waste Types
- 5.2 By Pre-processing Technology
- 5.2.1 Mechanical Sorting and Segregation
- 5.2.2 Shredding and Size Reduction
- 5.2.3 Screening and Classification
- 5.2.4 Magnetic and Eddy-Current Separation
- 5.2.5 Air and Ballistic Separation
- 5.2.6 Optical and Sensor-Based Sorting
- 5.2.7 Mechanical-Biological Treatment and Biodrying
- 5.2.8 Drying and Moisture Conditioning
- 5.2.9 Others
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 France
- 5.3.2.3 Italy
- 5.3.2.4 Spain
- 5.3.2.5 United Kingdom
- 5.3.2.6 Poland
- 5.3.2.7 Russia
- 5.3.2.8 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 India
- 5.3.3.3 Japan
- 5.3.3.4 South Korea
- 5.3.3.5 Australia
- 5.3.3.6 Indonesia
- 5.3.3.7 Vietnam
- 5.3.3.8 Thailand
- 5.3.3.9 Rest of Asia-Pacific
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Chile
- 5.3.4.4 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 United Arab Emirates
- 5.3.5.3 Egypt
- 5.3.5.4 South Africa
- 5.3.5.5 Morocco
- 5.3.5.6 Rest of Middle East and Africa
- 5.3.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Andusia Holdings Limited
- 6.4.2 Beauparc Utilities Holdings Limited
- 6.4.3 Biffa plc
- 6.4.4 CEMEX, S.A.B. de C.V.
- 6.4.5 EEW Energy from Waste GmbH
- 6.4.6 Enva Group Limited
- 6.4.7 FCC Environment (UK) Limited
- 6.4.8 Geminor AS
- 6.4.9 Geocycle (Deutschland) GmbH
- 6.4.10 Heidelberg Materials AG
- 6.4.11 Holcim Ltd.
- 6.4.12 Indaver NV
- 6.4.13 Paprec Group S.A.S. (Paprec)
- 6.4.14 PreZero International GmbH
- 6.4.15 Ragn-Sells AB
- 6.4.16 REMONDIS SE & Co. KG
- 6.4.17 Renewi plc (Renewi)
- 6.4.18 SUEZ S.A.
- 6.4.19 Veolia Environnement SA
- 6.4.20 Vicat SA
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

