PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186055

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186055
Digital Travel - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
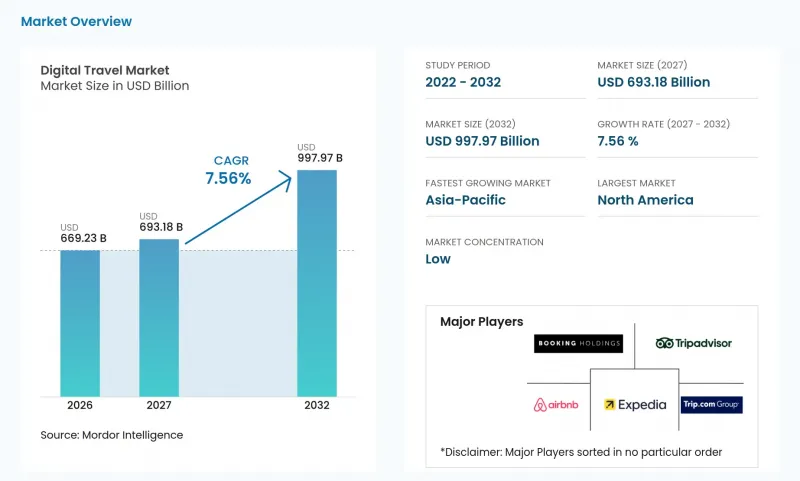
According to Mordor Intelligence, the global digital travel market was valued at USD 669.23 billion in 2026 and is estimated to grow from USD 693.18 billion in 2027 to reach USD 997.97 billion by 2032, at a CAGR of 7.56% during the forecast period (2027-2032).
Global Digital Travel Market Trends and Insights
Smartphone-Led Booking and App Adoption
Mobile booking drives the global digital travel market by integrating travel research, payment, and servicing on a single device. Mobile devices accounted for 70.5% of global online travel traffic, highlighting the audience platforms must convert into bookings. In 2025, Booking.com's mobile app accounted for a share of room nights in the mid-50% range, up from the low-50% range in 2024. This trend is particularly relevant in markets where a unified app can combine rail, intercity bus, accommodation, and air travel in one purchasing flow. Strong onboarding, secure authentication, and fast checkout can reduce customer acquisition costs over time. Applications support market growth by enabling users to move from trip discovery to booking confirmation without a separate payment process.
Expansion of Digital Payments and Embedded Finance
Digital payment flexibility is an increasingly important competitive factor in the global digital travel market. Travel payment research by Nuvei and Edgar, Dunn & Company found that 92% of surveyed travelers considered payment ease important. In comparison, 59% would abandon a booking if their preferred payment method was unavailable and 75% preferred split payments. The research also estimated that payment declines and checkout friction put more than USD 30.00 billion in annual revenue at risk for airlines and online travel agencies. These findings highlight opportunities for digital travel platforms to offer localized payment methods, digital wallets, multi-currency pricing, and installment options. Tailoring checkout experiences to regional preferences and improving failed-transaction recovery can help reduce booking abandonment and strengthen customer confidence.
Customer-Acquisition Cost and Search-Platform Dependence
Customer acquisition remains a restraint in the global digital travel market, as many platforms rely on search engines and metasearch channels for paid demand. Booking Holdings' transformation program generated USD 500.00-550.00 million in annual run-rate savings through improved operating efficiency. Search results that answer travel queries without directing users to booking platforms can reduce referral traffic and increase paid visibility costs. Loyalty programs, direct applications, and post-booking services can reduce dependence on a single traffic source. Smaller regional travel operators may face greater pressure due to limited budgets for traffic acquisition and brand building. The market remains vulnerable when external discovery platforms control customer relationships.
Other drivers and restraints analyzed in the detailed report include:
- AI-Powered Personalization and Dynamic Pricing
- Growth of Mobile-First Travel Demand in Asia-Pacific
- Cybersecurity, Payment Fraud, and Data-Privacy Exposure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Online travel agencies held 45.73% of the global digital travel market in 2026, supported by broad inventory, loyalty tools, and consumer-facing applications. In 2025, Booking Holdings reported USD 186.10 billion in gross bookings and USD 26.90 billion in revenue, while Expedia reported USD 119.60 billion and USD 14.70 billion, respectively. Regional platforms, such as MakeMyTrip in India, combine domestic transportation and lodging for mobile-led audiences.
Corporate travel booking platforms are forecast to register an 8.34% CAGR through 2032, making them the fastest-growing service type. These platforms support connected booking, expense, policy, and traveler-support processes. They provide approved inventory and help firms meet duty-of-care requirements. Direct supplier websites remain relevant as hotels and airlines seek direct traveler relationships. In 2025, hotel websites generated an average booking value of USD 516.00, compared with USD 312.00 through online travel agencies. The market will continue to include intermediary and direct channels, as each serves distinct traveler and supplier needs. Metasearch and travel comparison platforms support price discovery and referral traffic, while other digital travel services, such as trip-planning and itinerary-management tools, add value before and after booking.
Complete Report Scope:
- By Service Type
- Online Travel Agencies (OTAs)
- Metasearch and Travel Comparison Platforms
- Direct Travel Booking Platforms
- Corporate Travel Booking Platforms
- Other Digital Travel Services
- By Booking Type
- Accommodation Booking
- Air Ticket Booking
- Ground Transportation Booking
- Tour, Activity and Experience Booking
- Others
- By Platform
- Mobile Applications
- Websites / Browser-Based Platforms
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Geography Analysis
North America accounted for 33.53% of the global digital travel market in 2026, making it the largest regional market. Established online travel agencies, loyalty programs, direct supplier channels, and B2B platform investments characterize the mature market. Supplier-direct booking channels and card-linked travel portals compete with online travel agencies, increasing the importance of loyalty, service quality, and direct traffic. Platforms must demonstrate value beyond search and transaction services.
Europe remains a major digital travel market, supported by strong platform use and a demanding regulatory environment. Online travel planning is substantial across the United Kingdom, Germany, France, Spain, and Italy. In November 2025, eDreams ODIGEO reported 7.70 million Prime subscribers, up 18%. Data privacy requirements and airline distribution disputes continue to shape platform operations.
Asia-Pacific is forecast to grow at an 8.85% CAGR from 2027 to 2032, making it the fastest-growing region. China, India, Japan, South Korea, and Southeast Asia support growth through rising travel demand and mobile adoption. In FY2025, Trip.com Group reported USD 8.90 billion in net revenue, up 17%, while international platform bookings grew 60% year over year. Local payments, cross-border travel, language support, and mobile-led service expectations will shape the market.
- Booking Holdings Inc.
- Expedia Group, Inc.
- Airbnb, Inc.
- Trip.com Group Limited
- Tripadvisor, Inc.
- MakeMyTrip Limited
- eDreams ODIGEO S.A.
- Despegar.com, Corp.
- Amadeus IT Group, S.A.
- Sabre Corporation
- Travelport Limited
- Klook
- GetYourGuide
- Traveloka Group
- Yatra Online Limited
- Seera Group
- Wego Pte Ltd
- Hopper Inc.
- Webjet Group Limited
- Tongcheng Travel Holdings Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Executive Summary
3 Market Landscape
- 3.1 Market Overview
- 3.2 Market Drivers
- 3.2.1 Smartphone-Led Booking and App Adoption
- 3.2.2 Expansion of Digital Payments and Embedded Finance
- 3.2.3 AI-Powered Personalization and Dynamic Pricing
- 3.2.4 Growth of Mobile-First Travel Demand in Asia-Pacific
- 3.2.5 Expansion of Multimodal and NDC-Based Travel Distribution
- 3.2.6 Social, Experience-Led, and Creator-Influenced Travel Discovery
- 3.3 Market Restraints
- 3.3.1 Customer-Acquisition Cost and Search-Platform Dependence
- 3.3.2 Cybersecurity, Payment Fraud, and Data-Privacy Exposure
- 3.3.3 Fragmented Supplier Technology and Servicing Complexity
- 3.3.4 Travel Affordability, Currency Volatility, and Price Sensitivity
- 3.4 Regulatory Landscape
- 3.5 Technological Outlook
- 3.6 Porter's Five Forces Analysis
- 3.6.1 Threat of New Entrants
- 3.6.2 Bargaining Power of Suppliers
- 3.6.3 Bargaining Power of Buyers
- 3.6.4 Threat of Substitutes
- 3.6.5 Competitive Rivalry
4 Digital Travel Supply & Development Intelligence
- 4.1 Digital Travel Landscape & Development Trends
- 4.2 Digital Travel Platforms and Service Offerings
5 Digital Travel Performance Intelligence
- 5.1 Online Booking Volume and Transaction Trends
- 5.2 Digital Travel Revenue and Average Booking Value
6 Consumer Behavior Analysis
- 6.1 Traveler Preferences and Digital Travel Demand Patterns
- 6.2 Online Booking Behavior and Channel Preferences
- 6.3 Travel Spending Trends and Emerging Digital Preferences
7 Market Size & Growth Forecasts (USD, Value)
- 7.1 By Service Type
- 7.1.1 Online Travel Agencies (OTAs)
- 7.1.2 Metasearch and Travel Comparison Platforms
- 7.1.3 Direct Travel Booking Platforms
- 7.1.4 Corporate Travel Booking Platforms
- 7.1.5 Other Digital Travel Services
- 7.2 By Booking Type
- 7.2.1 Accommodation Booking
- 7.2.2 Air Ticket Booking
- 7.2.3 Ground Transportation Booking
- 7.2.4 Tour, Activity and Experience Booking
- 7.2.5 Others
- 7.3 By Platform
- 7.3.1 Mobile Applications
- 7.3.2 Websites / Browser-Based Platforms
- 7.4 By Geography
- 7.4.1 North America
- 7.4.1.1 United States
- 7.4.1.2 Canada
- 7.4.1.3 Mexico
- 7.4.2 South America
- 7.4.2.1 Brazil
- 7.4.2.2 Peru
- 7.4.2.3 Chile
- 7.4.2.4 Argentina
- 7.4.2.5 Rest of South America
- 7.4.3 Europe
- 7.4.3.1 United Kingdom
- 7.4.3.2 Germany
- 7.4.3.3 France
- 7.4.3.4 Spain
- 7.4.3.5 Italy
- 7.4.3.6 BENELUX (Belgium, Netherlands, and Luxembourg)
- 7.4.3.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 7.4.3.8 Rest of Europe
- 7.4.4 Asia-Pacific
- 7.4.4.1 India
- 7.4.4.2 China
- 7.4.4.3 Japan
- 7.4.4.4 Australia
- 7.4.4.5 South Korea
- 7.4.4.6 South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- 7.4.4.7 Rest of Asia-Pacific
- 7.4.5 Middle East and Africa
- 7.4.5.1 United Arab Emirates
- 7.4.5.2 Saudi Arabia
- 7.4.5.3 South Africa
- 7.4.5.4 Nigeria
- 7.4.5.5 Rest of Middle East and Africa
- 7.4.1 North America
8 North America Market Size & Growth Forecasts (USD, Value) 2022- 2032
- 8.1 By Service Type
- 8.2 By Booking Type
- 8.3 By Platform
- 8.4 By Country
9 South America Market Size & Growth Forecasts (USD, Value) 2022- 2032
- 9.1 By Service Type
- 9.2 By Booking Type
- 9.3 By Platform
- 9.4 By Country
10 Europe Market Size & Growth Forecasts (USD, Value) 2022- 2032
- 10.1 By Service Type
- 10.2 By Booking Type
- 10.3 By Platform
- 10.4 By Country
11 Asia-Pacific Market Size & Growth Forecasts (USD, Value) 2022- 2032
- 11.1 By Service Type
- 11.2 By Booking Type
- 11.3 By Platform
- 11.4 By Country
12 Middle East and Africa Market Size & Growth Forecasts (USD, Value) 2022- 2032
- 12.1 By Service Type
- 12.2 By Booking Type
- 12.3 By Platform
- 12.4 By Country
13 Competitive Landscape
- 13.1 Market Concentration
- 13.2 Strategic Moves
- 13.3 Market Share Analysis
- 13.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 13.4.1 Booking Holdings Inc.
- 13.4.2 Expedia Group, Inc.
- 13.4.3 Airbnb, Inc.
- 13.4.4 Trip.com Group Limited
- 13.4.5 Tripadvisor, Inc.
- 13.4.6 MakeMyTrip Limited
- 13.4.7 eDreams ODIGEO S.A.
- 13.4.8 Despegar.com, Corp.
- 13.4.9 Amadeus IT Group, S.A.
- 13.4.10 Sabre Corporation
- 13.4.11 Travelport Limited
- 13.4.12 Klook
- 13.4.13 GetYourGuide
- 13.4.14 Traveloka Group
- 13.4.15 Yatra Online Limited
- 13.4.16 Seera Group
- 13.4.17 Wego Pte Ltd
- 13.4.18 Hopper Inc.
- 13.4.19 Webjet Group Limited
- 13.4.20 Tongcheng Travel Holdings Limited
14 Market Opportunities & Future Outlook
- 14.1 White-Space and Unmet-Need Assessment
- 14.2 Market Opportunities
- 14.2.1 AI-Driven Travel Personalization and Automated Booking
- 14.2.2 Expansion of Digital Travel Platforms in Emerging Markets
- 14.3 Future Outlook
15 Research Methodology

