PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187426

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187426
GCC Aircraft MRO - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
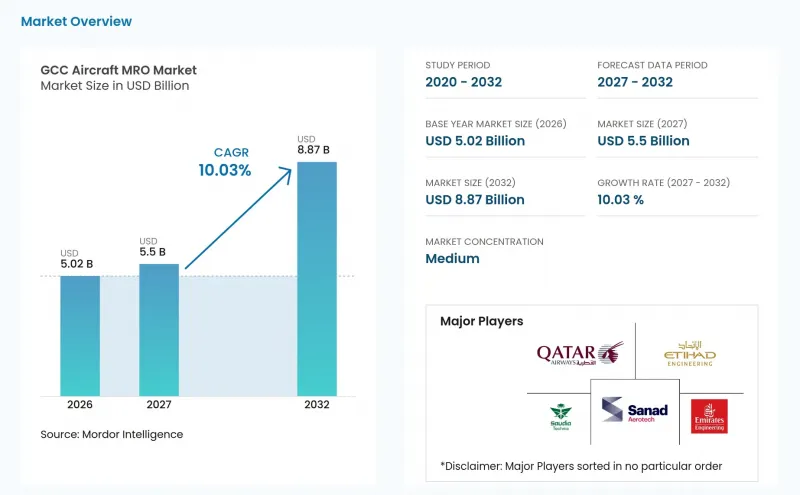
According to Mordor Intelligence, the GCC aircraft MRO market size was valued at USD 5.02 billion in 2026 and is forecast to grow from USD 5.50 billion in 2027 to USD 8.87 billion by 2032, registering a 10.03% CAGR between 2027 and 2032.
GCC Aircraft MRO Market Trends and Insights
Saudi and UAE Fleet Expansion Accelerating MRO Demand
Fleet expansion and modernization initiatives in Saudi Arabia and the UAE are expected to create long-term maintenance opportunities for GCC aircraft MRO providers. Saudia received its first LEAP-1A-powered A321XLR in May 2026, as part of its order for 15 aircraft. In July 2026, flynas confirmed orders for an additional 20 A321neo and five A330-900 aircraft. In the UAE, Emirates received 18 aircraft between January and September 2026, including 11 A350s and seven B777 freighters. Emirates is also expanding its widebody fleet and plans to develop a USD 5.1 billion, 1.1-million-square-meter engineering complex at Dubai South. Upon completion in mid-2030, the facility will be capable of servicing 28 widebody aircraft simultaneously. These fleet additions and MRO capacity investments are expected to increase demand for airframe, engine, component, and heavy-maintenance services across the GCC.
Saudi Vision 2030 and UAE Aviation Hub Investments Driving MRO Localization
Saudi Arabia and the UAE are expanding domestic aircraft maintenance capabilities through infrastructure investments and technical partnerships. In February 2026, Saudi Arabia's General Authority for Military Industries (GAMI) and GE Aerospace signed an agreement to strengthen F110 engine repair capabilities through specialized equipment and technical training. In May 2026, Emirates began construction of its USD 5.1 billion engineering complex at Dubai South, which is designed to accommodate 28 widebody aircraft simultaneously when completed in mid-2030. In July 2026, the UAE-based AMMROC signed an agreement with Airbus Defense and Space to explore expanded maintenance capabilities for C295 and A330 MRTT military aircraft. These developments will support the localization of commercial and military maintenance activities, improve access to specialized technical capabilities, and position GCC providers to capture a greater share of regional maintenance expenditure.
Shortage of GACA and GCAA-Licensed Aircraft Maintenance Professionals
The limited availability of licensed engineers, type-rated technicians, and specialized maintenance personnel may constrain the expansion of GCC aircraft MRO operations. Boeing's 2026 Pilot and Technician Outlook projected a global requirement for 728,000 new commercial aircraft maintenance technicians between 2026 and 2045, reflecting substantial long-term recruitment and training needs. In July 2026, the UAE's AMMROC launched its Ruwad AMMROC program to train and employ 100 Emirati military aircraft maintenance technicians by 2030. These initiatives highlight the importance of developing specialized technical capabilities as maintenance facilities expand. However, personnel must acquire practical experience, aircraft-specific qualifications, and relevant authorizations before undertaking certain maintenance responsibilities. Therefore, shortages of qualified personnel may restrict hangar utilization, delay engine and component maintenance, and increase recruitment costs for GCC MRO providers.
Other drivers and restraints analyzed in the detailed report include:
- Expanding GCC LEAP, GTF, GEnx, and Trent Fleets Increasing Engine Shop Visits
- Desert Heat, Sand Exposure, and Intensive Regional Operations Increasing Component Maintenance
- Global Engine Shop-Slot Shortages Delaying GCC Fleet Maintenance
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Engine MRO held 41.30% of the GCC aircraft MRO market share in 2026. The segment reflects the region's widebody fleet composition and operating conditions that reduce time on wing for LEAP, GE90, GEnx, Trent 700, and Trent XWB engines. Sanad expanded its relationship with Rolls-Royce Trent 700 in February 2026. The agreement covers up to 612 shop visits through 2031 and includes AED 125 million (USD 34.04 million) for tools and automation. This capability allows Abu Dhabi to pursue engine work from Africa and South Asia, as well as domestic demand. Engine work also attracts supporting investment in test cells, tooling, repair approvals, and skilled labor. Those requirements favor established providers with OEM relationships and a large capital base.
Modifications and upgrades are forecast to record a 12.88% CAGR through 2032. Emirates is undertaking a USD 5 billion cabin retrofit program for 219 widebody aircraft. Its program had completed 100 aircraft by July 2026 after 4.40 million collective work hours at Dubai hangars. The B777X delivery delays are directing cabin investment toward existing aircraft rather than new aircraft interiors. This preserves demand for GCC aircraft MRO services, including refurbishment and interior modification work. Airframe MRO is also becoming more demanding as composite-intensive narrowbodies enter heavy-check cycles. Line and component work remain steady, with desert conditions increasing wear on avionics, landing gear, and hydraulic systems. Approval requirements keep complex component repair concentrated among providers with approved maintenance data.
Fixed-wing aircraft held 91.50% revenue share in 2026. Commercial and military fixed-wing fleets dominate the aircraft bases across the 6 GCC states. Regional maintenance infrastructure has also been built primarily around widebody and narrowbody airframes. Emirates Engineering's Dubai South complex will be designed to service 28 widebody aircraft simultaneously after its expected mid-2030 completion. The facility demonstrates the scale of fixed-wing capacity that operators expect to need. Heavy checks on large aircraft require large hangars, special tooling, and a substantial certified workforce. This makes capacity expansion costly and raises barriers for smaller regional shops. Therefore, fleet growth continues to support large, integrated maintenance campuses.
Rotary-wing MRO is projected to advance at a 12.04% CAGR through 2032. Demand comes from defense fleets, offshore energy activity, tourism projects, and search-and-rescue operations. AMMROC became the first Sikorsky-authorized Black Hawk helicopter blade depot outside the US in February 2025. Gulf Helicopters also signed a GE Aerospace TrueChoice agreement in November 2025 for CT7-2E1 engines powering its Leonardo AW189 aircraft. These authorizations build GCC aircraft MRO market capability through OEM-approved service scopes. Mission-critical helicopter operations require frequent inspections and dependable turnaround times. Gulf operating conditions can further increase inspection needs. This supports MRO spending per helicopter above the level associated with narrowbody commercial aircraft.
Complete Report Scope:
- By MRO Type
- Engine
- Airframe Heavy Maintenance
- Component
- Line and Routine Checks
- Modifications and Upgrades
- By Aircraft Type
- Fixed-Wing
- Rotary-Wing
- By Application
- Commercial Aviation
- Passenger
- Cargo/Freighter
- Military Aviation
- General Aviation
- Commercial Aviation
- By Service Provider
- Airline-affiliated MRO
- Independent Third-party MRO
- OEM-Captive MRO
- Military Depots
- By Geography
- United Arab Emirates
- Saudi Arabia
- Qatar
- Oman
- Kuwait
- Bahrain
List of Companies Covered in this Report:
- Emirates Engineering (Emirates Group)
- Etihad Airways Engineering L.L.C.
- Saudia Technic
- Sanad Aerotech (Sanad Group)
- RTX Corporation
- Safran SA
- GE Aerospace
- Lufthansa Technik AG
- Advanced Military Maintenance, Repair and Overhaul Center (AMMROC)
- Global Aerospace Logistics LLC
- The Helicopter Company
- Pannesma Co. Ltd.
- AeroGulf Services Company LLC
- Oman Air Engineering (Oman Air)
- Qatar Airways Group Q.C.S.C.
- AMAC Aerospace AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Saudi Arabian and UAE fleet expansion accelerating MRO demand
- 4.2.2 Saudi Vision 2030 and UAE aviation hub investments driving MRO localization
- 4.2.3 Expanding GCC LEAP, GTF, GEnx, and Trent fleets increasing engine shop visits
- 4.2.4 GCC airline fleet growth driving third-party MRO outsourcing
- 4.2.5 Desert heat, sand exposure, and intensive regional operations increasing component maintenance
- 4.2.6 GCC aviation hubs accelerating predictive maintenance adoption
- 4.3 Market Restraints
- 4.3.1 High MRO infrastructure investments and lengthy GACA-GCAA certification processes
- 4.3.2 Shortage of GACA and GCAA-licensed aircraft maintenance professionals
- 4.3.3 Global engine shop-slot shortages delaying GCC fleet maintenance
- 4.3.4 OEM-controlled engine technologies and parts limiting GCC MRO independence
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By MRO Type
- 5.1.1 Engine
- 5.1.2 Airframe Heavy Maintenance
- 5.1.3 Component
- 5.1.4 Line and Routine Checks
- 5.1.5 Modifications and Upgrades
- 5.2 By Aircraft Type
- 5.2.1 Fixed-Wing
- 5.2.2 Rotary-Wing
- 5.3 By Application
- 5.3.1 Commercial Aviation
- 5.3.1.1 Passenger
- 5.3.1.2 Cargo/Freighter
- 5.3.2 Military Aviation
- 5.3.3 General Aviation
- 5.3.1 Commercial Aviation
- 5.4 By Service Provider
- 5.4.1 Airline-affiliated MRO
- 5.4.2 Independent Third-party MRO
- 5.4.3 OEM-Captive MRO
- 5.4.4 Military Depots
- 5.5 By Geography
- 5.5.1 United Arab Emirates
- 5.5.2 Saudi Arabia
- 5.5.3 Qatar
- 5.5.4 Oman
- 5.5.5 Kuwait
- 5.5.6 Bahrain
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Emirates Engineering (Emirates Group)
- 6.4.2 Etihad Airways Engineering L.L.C.
- 6.4.3 Saudia Technic
- 6.4.4 Sanad Aerotech (Sanad Group)
- 6.4.5 RTX Corporation
- 6.4.6 Safran SA
- 6.4.7 GE Aerospace
- 6.4.8 Lufthansa Technik AG
- 6.4.9 Advanced Military Maintenance, Repair and Overhaul Center (AMMROC)
- 6.4.10 Global Aerospace Logistics LLC
- 6.4.11 The Helicopter Company
- 6.4.12 Pannesma Co. Ltd.
- 6.4.13 AeroGulf Services Company LLC
- 6.4.14 Oman Air Engineering (Oman Air)
- 6.4.15 Qatar Airways Group Q.C.S.C.
- 6.4.16 AMAC Aerospace AG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

