PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187652

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187652
Singapore E-commerce - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the Singapore e-commerce market size was valued at USD 6.17 billion in 2026 and estimated to grow from USD 6.84 billion in 2027 to reach USD 11.25 billion by 2032, at a CAGR of 10.46% during the forecast period (2027-2032).
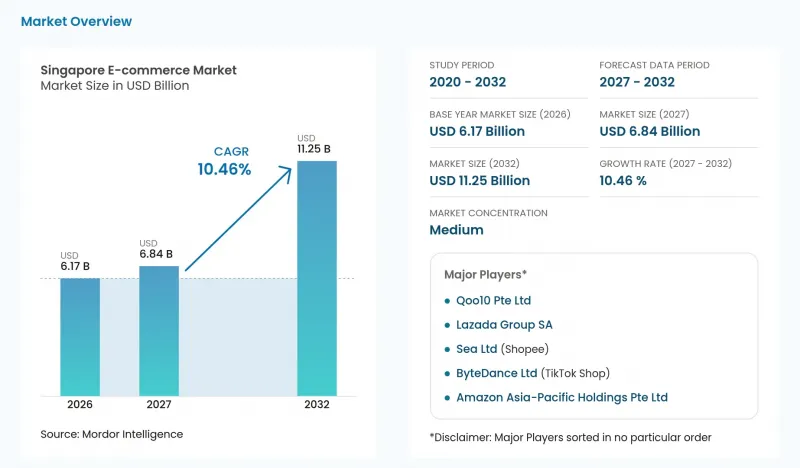
This report is segmented by Business Model (B2C and B2B), Product Category for B2C E-commerce (Consumer Electronics, Fashion and Apparel, and more), Payment Mode for B2C E-commerce (Mobile Wallets, Credit/ Debit Cards, and more), and Device (Smartphone, Desktop / Laptop, and more). The market forecasts are provided in terms of value (USD), based on availability.
Singapore E-commerce Market Trends and Insights
Rising digital-wallet penetration
Wallet acceptance is a distribution choice as well as a checkout feature because it determines which existing payment flows a merchant can serve. Global Payments data put digital wallets at 40% of Singapore e-commerce spend in 2025. For a buyer intending to pay through a wallet, an unsupported checkout can create a choice between changing payment methods and abandoning that order. Adding wallet acceptance can therefore widen usable demand at the point of payment without relying on a separate increase in shopping interest. The near-term commercial opening is access to wallet-funded purchases already occurring online, making checkout coverage relevant before further customer recruitment.
Phased mandatory nationwide e-invoice adoption for GST-registered B2B firms
The phased e-invoicing requirement gives business sellers a defined timetable for connecting transaction records with tax reporting. Since April 1, 2026, businesses applying for voluntary GST registration have been required to submit invoice data directly to IRAS through InvoiceNow, regardless of incorporation date or business structure. Overseas entities and businesses liable to register wholly under the Reverse Charge regime are exempt. Singapore also announced that remaining GST-registered businesses would be required to submit invoice data directly to IRAS through InvoiceNow in phases from April 2028 through April 2031. From April 2028, new compulsory registrants join the requirement, while existing businesses enter from lower to higher annual-supplies bands based on accounting periods ending in 2025. The scheduled widening can support B2B online sales workflows by adding counterparties able to exchange invoices digitally, with the highest band entering in April 2031.
Escalating parcel-locker congestion
Parcel-locker capacity constrains the delivery format an operator can promise to condominium residents. Shopee's Parcel Santa guidance says SingPost first attempts delivery to the condominium locker. When that locker is full, the guidance sends parcels that fit to the letterbox and larger parcels to the doorstep instead. For that parcel, the fallback removes the locker handoff from the delivery offer.
Other drivers and restraints analyzed in the detailed report include:
- Same-day island-wide fulfillment race
- AI-powered live-stream commerce boom
- Surge in e-commerce scams and compliance costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
B2C accounted for an 87.48% share of the Singapore e-commerce market size in 2026, making it the largest segment. Within retail trade, online retail sales represented an estimated 15.7% of Singapore retail trade sales in August 2026. The August estimate exceeded the 15.2% recorded in July 2026. With most retail trade sales that month made through other channels, online ordering works as an extension of existing retail businesses.
B2B is forecast to be the fastest-growing segment, at a CAGR of 11.95% during 2027-2032. Singapore's Electronic Transactions Act supports electronic signatures for business sales and procurement agreements, subject to party choice and statutory exclusions. For buyers and suppliers choosing an eligible electronic agreement, the framework can connect online order formation with contract execution through an electronic process. For a B2B seller designing an online order flow, the practical first step is to identify which agreement types qualify for electronic signing.
Consumer electronics was the largest segment, accounting for 46.63% of B2C e-commerce sales in 2026. Airwallex and Statista's January 2025 survey covered 1,000 Singapore-based shoppers who had bought internationally online in the previous 12 months. Of these respondents, 56% said they bought electronics from international sellers. For online sellers, the result identifies an electronics buyer group whose purchases connect Singapore demand with foreign supply. A Singapore electronics retailer targeting these shoppers needs a proposition that can compete with the international sellers they already use.
The food and beverages segment is forecast to be the fastest-growing segment, at a CAGR of 12% during 2027-2032. In February 2026, foodpanda reported that monthly grocery order frequency among its Singapore shoppers had increased by 7% since 2023. It also reported 8% more products in each Singapore grocery order in 2025 than in 2024. These measures point to different operating demands, as repeat ordering makes service availability relevant while larger item counts change the work attached to each basket. For a grocery operator facing both patterns, faster delivery alone would leave the additional picking and packing required by larger baskets unaddressed.
Complete Report Scope:
- By Business Model
- B2B
- B2C
- By Product Category for B2C E-commerce
- Beauty and Personal Care
- Consumer Electronics
- Fashion and Apparel
- Food and Beverages
- Furniture and Home
- Toys, DIY and Media
- Other Product Categories for B2C E-commerce
- By Payment Mode for B2C E-commerce
- Credit/ Debit Cards
- Mobile Wallets
- Other Payment Modes for B2C E-commerce
- By Device
- Smartphone
- Desktop / Laptop
- Other Device Types for B2C E-commerce
List of Companies Covered in this Report:
- Sea Ltd (Shopee)
- Lazada Group SA
- Amazon Asia-Pacific Holdings Pte Ltd
- Qoo10 Pte Ltd
- ByteDance Ltd (TikTok Shop)
- Adevinta ASA (Gumtree SG)
- Carousell Pte Ltd
- FairPrice Online Pte Ltd
- RedMart Pte Ltd
- Zalora South East Asia Pte Ltd
- Shein Singapore Pte Ltd
- Elementary Innovation Pte Ltd (Temu)
- Sephora Digital SEA Pte Ltd
- iHerb LLC
- Courts Asia Ltd
- Ikano Pte Ltd (IKEA Singapore)
- Decathlon Singapore Pte Ltd
- Love, Bonito Pte Ltd
- Charles & Keith
- Apple South Asia Pte Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising digital-wallet penetration
- 4.2.2 Phased mandatory nationwide e-invoice adoption for GST-registered B2B firms
- 4.2.3 Same-day island-wide fulfillment race
- 4.2.4 AI-powered live-stream commerce boom
- 4.2.5 Government carbon-reduction logistics grants
- 4.2.6 Cross-border China-Singapore free-trade corridors
- 4.3 Market Restraints
- 4.3.1 Escalating parcel-locker congestion
- 4.3.2 Surge in e-commerce scams and compliance costs
- 4.3.3 Manpower shortages in last-mile delivery
- 4.3.4 Data-sovereignty rules limiting cloud scaling
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Business Model
- 5.1.1 B2B
- 5.1.2 B2C
- 5.2 By Product Category for B2C E-commerce
- 5.2.1 Beauty and Personal Care
- 5.2.2 Consumer Electronics
- 5.2.3 Fashion and Apparel
- 5.2.4 Food and Beverages
- 5.2.5 Furniture and Home
- 5.2.6 Toys, DIY and Media
- 5.2.7 Other Product Categories for B2C E-commerce
- 5.3 By Payment Mode for B2C E-commerce
- 5.3.1 Credit/ Debit Cards
- 5.3.2 Mobile Wallets
- 5.3.3 Other Payment Modes for B2C E-commerce
- 5.4 By Device
- 5.4.1 Smartphone
- 5.4.2 Desktop / Laptop
- 5.4.3 Other Device Types for B2C E-commerce
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Sea Ltd (Shopee)
- 6.4.2 Lazada Group SA
- 6.4.3 Amazon Asia-Pacific Holdings Pte Ltd
- 6.4.4 Qoo10 Pte Ltd
- 6.4.5 ByteDance Ltd (TikTok Shop)
- 6.4.6 Adevinta ASA (Gumtree SG)
- 6.4.7 Carousell Pte Ltd
- 6.4.8 FairPrice Online Pte Ltd
- 6.4.9 RedMart Pte Ltd
- 6.4.10 Zalora South East Asia Pte Ltd
- 6.4.11 Shein Singapore Pte Ltd
- 6.4.12 Elementary Innovation Pte Ltd (Temu)
- 6.4.13 Sephora Digital SEA Pte Ltd
- 6.4.14 iHerb LLC
- 6.4.15 Courts Asia Ltd
- 6.4.16 Ikano Pte Ltd (IKEA Singapore)
- 6.4.17 Decathlon Singapore Pte Ltd
- 6.4.18 Love, Bonito Pte Ltd
- 6.4.19 Charles & Keith
- 6.4.20 Apple South Asia Pte Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

