PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187792

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187792
India Engineering, Procurement, And Construction Management (EPCM) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the India engineering, procurement, and construction management (EPCM) market size is expected to increase from USD 75.04 billion in 2026 to USD 81.28 billion in 2027 and reach USD 120.1 billion by 2032, growing at a CAGR of 8.12% over 2027-2032.
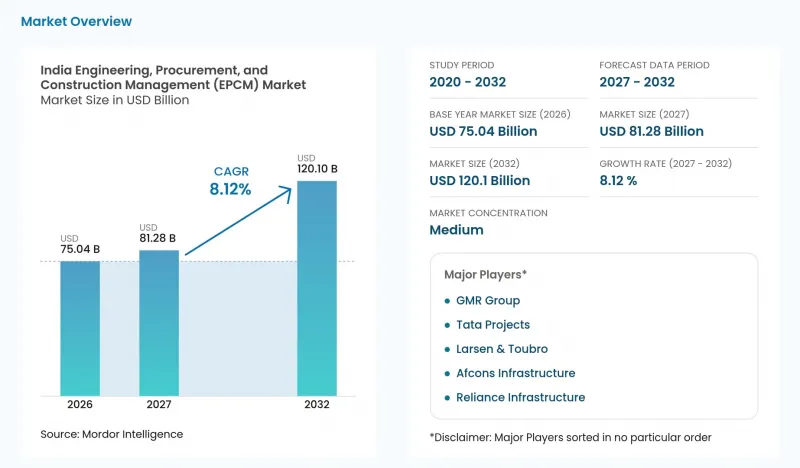
This report is segmented by Service (Construction Management Services, Engineering Services, and more), Sector (Infrastructure, Commercial, and more), Investment Source (Public Sector and Private Sector), and Geography (West India, South India, and more). The market forecasts are provided in terms of value (USD), based on availability.
India Engineering, Procurement, And Construction Management (EPCM) Market Trends and Insights
Government infrastructure mega-capex outlay (Budget FY27)
Public capital programs create service demand when fiscal priorities acquire a defined project scope and delivery model. India's FY 2026-27 Union Budget proposed public capital expenditure about 9% above FY 2025-26 Budget Estimates. Separately, on April 10, 2026, the Department of Economic Affairs' PPP Appraisal Committee gave final approval to a greenfield regional expressway north of Hyderabad, in Telangana, under the hybrid annuity model. The Ministry of Road Transport and Highways was the project sponsor. Approval-stage assignments give EPCM providers a route into public programs before full construction deployment. Public sponsors' decisions on pre-construction service packages therefore determine when a budget priority becomes a billable management assignment.
Rapid scale-up of renewable & green-hydrogen giga-projects
Renewable deployment and refinery hydrogen procurement create complementary sources of project-execution work. India added 24.56 GW of renewable-power capacity, including large hydropower, from April through September 2026. In August 2026, the Ministry of New and Renewable Energy announced green-hydrogen production capacity awards totaling 30,000 metric tons per year for 4 Indian refinery locations. The ministry described build-own-operate implementation through private developers, placing project investment with those developers. Those developers are potential buyers of engineering and management services as awarded hydrogen supply capacity moves toward project execution.
Land-acquisition & environmental-clearance bottlenecks
Land readiness can prevent a highway award from translating into a continuously available construction site. In an April 3, 2025, parliamentary reply, the Ministry of Road Transport and Highways reported that 683 National Highway projects begun since April 1, 2014, had exceeded their original schedules. Land acquisition and statutory clearances were among several causes identified alongside utility shifting, contractor problems and other impediments. For construction managers, these dependencies make the sequence of usable work fronts more important than the nominal award date. Interrupted deployment on inaccessible stretches can slow the conversion of awarded engineering and supervision work into sustained service revenue.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated digital twin & BIM mandates in public tenders
- Surge in data-center & hyperscale industrial parks
- Volatile steel-cement pricing compressing EPC margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Construction management services accounted for a 56.07% share of the India engineering, procurement, and construction management (EPCM) market size in 2026. NBCC (India) Limited was executing 38,000 units across 25 Amrapali projects in Noida and Greater Noida in FY 2025-26, with more than 32,550 houses completed and handover in process. For this largest segment, the distinction between physical completion and handover shows why management can extend beyond coordinating active building works. Management teams can therefore plan resource release around completed handovers, aligning the end of their assignment with the transfer of homes to occupants.
Other services are forecast to be the fastest-growing segment, with a CAGR of 9.78% over 2027-2032. On November 24, 2025, NBCC signed an agreement appointing it as project management consultant and executing agency for the Nagpur Metropolitan Region Development Authority's Naveen Nagpur project. Its broader appointment included financial feasibility studies, tendering management, design coordination and construction-program oversight. The combination creates room for separately defined advisory and coordination deliverables within a wider implementation assignment, allowing providers to earn from preparing a project for execution as well as managing its subsequent delivery.
Complete Report Scope:
- By Service
- Engineering Services
- Procurement Services
- Construction Management Services
- Other Services
- By Sector
- Residential
- Commercial
- Infrastructure
- By Investment Source
- Public Sector
- Private Sector
- By Geography
- North India
- West India
- South India
- East & North-East India
- Central India
List of Companies Covered in this Report:
- Larsen & Toubro
- Tata Projects
- Reliance Infrastructure
- GMR Group
- Afcons Infrastructure
- Hindustan Construction Company
- NCC Ltd
- IVRCL
- KEC International
- Gammon India
- Simplex Infrastructures
- Patel Engineering Ltd
- Megha Engineering & Infrastructures
- Salasar Techno Engineering
- Kalpataru Projects International
- Dilip Buildcon
- BHEL
- Shapoorji Pallonji
- Ashoka Buildcon
- PNC Infratech
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government infrastructure mega-capex outlay (Budget FY27)
- 4.2.2 Rapid scale-up of renewable & green-hydrogen giga-projects
- 4.2.3 Accelerated digital twin & BIM mandates in public tenders
- 4.2.4 Surge in data-center & hyperscale industrial parks
- 4.2.5 ESG-linked financing lowering cost of capital for EPCM projects
- 4.2.6 Entry of global OEM-led "design-for-India" modular solutions
- 4.3 Market Restraints
- 4.3.1 Land-acquisition & environmental-clearance bottlenecks
- 4.3.2 Volatile steel-cement pricing compressing EPC margins
- 4.3.3 Acute shortage of mid-senior project managers/QA-QC talent
- 4.3.4 Working-capital squeeze from elongated public-sector receivables
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service
- 5.1.1 Engineering Services
- 5.1.2 Procurement Services
- 5.1.3 Construction Management Services
- 5.1.4 Other Services
- 5.2 By Sector
- 5.2.1 Residential
- 5.2.2 Commercial
- 5.2.3 Infrastructure
- 5.3 By Investment Source
- 5.3.1 Public Sector
- 5.3.2 Private Sector
- 5.4 By Geography
- 5.4.1 North India
- 5.4.2 West India
- 5.4.3 South India
- 5.4.4 East & North-East India
- 5.4.5 Central India
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Larsen & Toubro
- 6.4.2 Tata Projects
- 6.4.3 Reliance Infrastructure
- 6.4.4 GMR Group
- 6.4.5 Afcons Infrastructure
- 6.4.6 Hindustan Construction Company
- 6.4.7 NCC Ltd
- 6.4.8 IVRCL
- 6.4.9 KEC International
- 6.4.10 Gammon India
- 6.4.11 Simplex Infrastructures
- 6.4.12 Patel Engineering Ltd
- 6.4.13 Megha Engineering & Infrastructures
- 6.4.14 Salasar Techno Engineering
- 6.4.15 Kalpataru Projects International
- 6.4.16 Dilip Buildcon
- 6.4.17 BHEL
- 6.4.18 Shapoorji Pallonji
- 6.4.19 Ashoka Buildcon
- 6.4.20 PNC Infratech
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

