PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119747

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119747
Malaysia Data Center Server - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Malaysia data center server market size was valued at USD 2.22 billion in 2025 and estimated to grow from USD 2.59 billion in 2026 to reach USD 5.53 billion by 2031, at a CAGR of 16.42% during the forecast period (2026-2031).
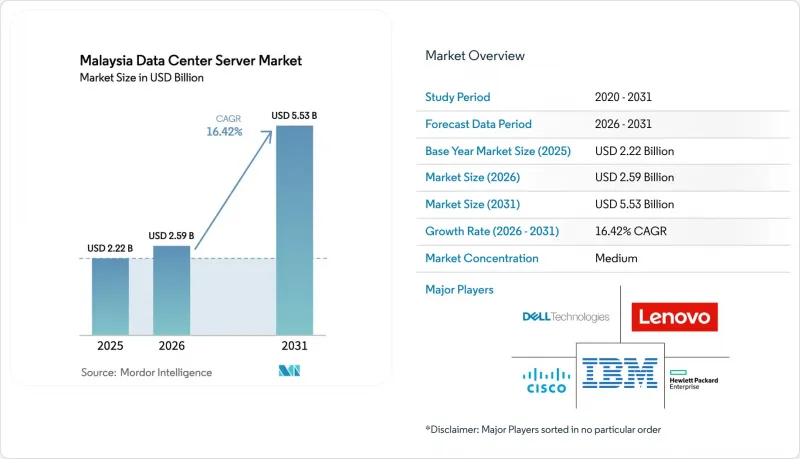
This report is Segmented by Data Center Tier(Tier 1 and 2, Tier 3, Tier 4), Form Factor(Half-Height Blades, Full-Height Blades and More), Application (Virtualisation and Private Cloud, High-Performance Computing and More), Data Center Type(Hyperscalers Provider and More), End User Industry(BFSI and More). The Market Sizes and Forecasts are Provided in Terms of Value (USD) for all the Above Segments.
Malaysia Data Center Server Market Trends and Insights
Surge in Hyperscale & Colocation Data-Center Investments
Major cloud providers pledged more than USD 15 billion in 2024 alone, led by Google's USD 2 billion first Malaysian region in Greater Kuala Lumpur and Microsoft's three-site rollout scheduled for Q2 2025.Johor's comparative land affordability and close distance to Singapore accelerate campus-scale builds such as Vantage's 256 MW Cyberjaya complex and Princeton Digital Group's 150 MW AI-ready JH1 site. The resulting spike in rack demand concentrates orders for liquid-cooled GPU servers optimized for AI inference, reinforcing the Malaysia data center server market.
Government Cloud-First & Digital-Economy Incentives
The MyDIGITAL blueprint targets a 22.6% GDP share from digital activities by 2025 and requires 80% of public-sector workloads to migrate to hybrid cloud environments. Conditional approvals worth RM 12-15 billion allow hyperscalers to build locally, while the Cloud Framework Agreement steers procurement toward domestic partners. Ministries upgrading from legacy three-tier stacks to hyper-converged architectures report faster data access and stronger resiliency, cementing ongoing server refresh cycles.
Expansion of Internet Infrastructure and New Submarine Cables
Malaysia's participation in SEA-ME-WE 6 and other cable systems strengthens its interconnection profile, creating server demand for transit traffic and CDN nodes.Telekom Malaysia's fiber expansion and DE-CIX's peering fabric enhance route diversity and drive purchases of high-throughput network servers needed for traffic aggregation
Other drivers and restraints analyzed in the detailed report include:
- Rising Adoption of Cloud, AI/ML and IoT-Driven Workloads
- 2027 Electricity-Tariff Reform Cutting Industrial Subsidies
- High CapEx for Facility & Server Procurement
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tier 3 facilities dominated the Malaysia data center server market share at 70.92% in 2025, supported by banking, telecom, and public-sector workloads that demand high availability. Parallelly, Tier 4 sites are outpacing overall growth at an 18.33% CAGR, reflecting hyperscaler insistence on five-nines uptime for AI training clusters. Vantage's Cyberjaya and Princeton Digital's JH1 campuses exemplify the Tier 4 blueprint, featuring redundant power and chilled-water loops to sustain racks exceeding 70 kW.
The Malaysia data center server market is thus bifurcating: Tier 1-2 footprints meet edge and disaster-recovery needs, whereas Tier 3-4 facilities capture long-term, mission-critical demand. Tier 4's momentum also aligns with the 2026 green-tax credit that rewards high-efficiency hardware, nudging enterprises toward the latest processor generations and cooling techniques.
Half-height blades held 62.54% revenue in 2025 courtesy of their familiarity, balanced thermals, and integration ease into legacy racks. Yet quarter-height micro-blades are expanding at a 16.61% CAGR, propelled by 5G backhaul rollouts and regional MEC nodes that require compact, ruggedised servers. Intel's 5G Digital School venture in Penang showcases micro-blade edge clusters providing AI-enabled educational content with minimal latency.
Within hyperscale halls, full-height blades and GPU trays dominate AI training, but operators simultaneously procure micro-blades for latency-sensitive inference tasks. Consequently, server vendors increasingly market unified chassis able to host mixed-blade heights, lowering spares inventories and accelerating deployment-an advantage in Malaysia data center server market procurement cycles.
Complete Report Scope:
- By Data-Center Tier
- Tier 1 and 2
- Tier 3
- Tier 4
- By Form Factor
- Half-height Blades
- Full-height Blades
- Quarter-height / Micro-blades
- By Application / Workload
- Virtualisation and Private Cloud
- High-Performance Computing (HPC)
- Artificial Intelligence/Machine Learning and Data Analytics
- Storage-centric
- Edge / IoT Gateways
- By Data Center Type
- Hyperscalers/Cloud Service Provider
- Colocation Facilities
- Enterprise and Edge
- By End-use Industry
- BFSI
- IT and Telecom
- Healthcare and Life-Sciences
- Manufacturing and Industry 4.0
- Energy and Utilities
- Government and Defence
- Other End Users
List of Companies Covered in this Report:
- Dell Technologies
- Hewlett Packard Enterprise
- Cisco Systems
- Huawei Technologies
- Lenovo Group
- Super Micro Computer
- IBM Corp.
- Nvidia Corp.
- Inspur Information
- Fujitsu Ltd.
- NEC Corp.
- Oracle Corp.
- Atos SE
- Quanta Cloud Technology (QCT)
- ASUS (Enterprise Server BU)
- Kingston Technology
- Seagate Technology (Server platforms)
- Hyve Solutions
- Wistron (Wiwynn)
- Gigabyte Technology
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in hyperscale?and?colocation data-center investments
- 4.2.2 Expansion of internet infrastructure and new submarine cables
- 4.2.3 Government cloud-first and Digital Economy incentives (Malaysia Digital, MyDIGITAL)
- 4.2.4 Rising adoption of cloud, AI/ML and IoT-driven workloads
- 4.2.5 Entry of sovereign-fund-backed edge micro-hubs in Tier-2 cities
- 4.2.6 Introduction of 2026 green-tax credit for high-efficiency servers
- 4.3 Market Restraints
- 4.3.1 High CapEx for facility and server procurement
- 4.3.2 FX-linked cost risk from imported hardware
- 4.3.3 2027 electricity-tariff reform cutting industrial subsidies
- 4.3.4 Land scarcity in Greater Kuala Lumpur inflating real-estate costs
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook (liquid cooling, ARM-based servers, DPUs)
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macroeconomic Factors on the Market
5 MARKET SIZE and GROWTH FORECASTS (VALUE)
- 5.1 By Data-Center Tier
- 5.1.1 Tier 1 and 2
- 5.1.2 Tier 3
- 5.1.3 Tier 4
- 5.2 By Form Factor
- 5.2.1 Half-height Blades
- 5.2.2 Full-height Blades
- 5.2.3 Quarter-height / Micro-blades
- 5.3 By Application / Workload
- 5.3.1 Virtualisation and Private Cloud
- 5.3.2 High-Performance Computing (HPC)
- 5.3.3 Artificial Intelligence/Machine Learning and Data Analytics
- 5.3.4 Storage-centric
- 5.3.5 Edge / IoT Gateways
- 5.4 By Data Center Type
- 5.4.1 Hyperscalers/Cloud Service Provider
- 5.4.2 Colocation Facilities
- 5.4.3 Enterprise and Edge
- 5.5 By End-use Industry
- 5.5.1 BFSI
- 5.5.2 IT and Telecom
- 5.5.3 Healthcare and Life-Sciences
- 5.5.4 Manufacturing and Industry 4.0
- 5.5.5 Energy and Utilities
- 5.5.6 Government and Defence
- 5.5.7 Other End Users
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Dell Technologies
- 6.4.2 Hewlett Packard Enterprise
- 6.4.3 Cisco Systems
- 6.4.4 Huawei Technologies
- 6.4.5 Lenovo Group
- 6.4.6 Super Micro Computer
- 6.4.7 IBM Corp.
- 6.4.8 Nvidia Corp.
- 6.4.9 Inspur Information
- 6.4.10 Fujitsu Ltd.
- 6.4.11 NEC Corp.
- 6.4.12 Oracle Corp.
- 6.4.13 Atos SE
- 6.4.14 Quanta Cloud Technology (QCT)
- 6.4.15 ASUS (Enterprise Server BU)
- 6.4.16 Kingston Technology
- 6.4.17 Seagate Technology (Server platforms)
- 6.4.18 Hyve Solutions
- 6.4.19 Wistron (Wiwynn)
- 6.4.20 Gigabyte Technology
7 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

