PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119754

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119754
Europe Data Center Server - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
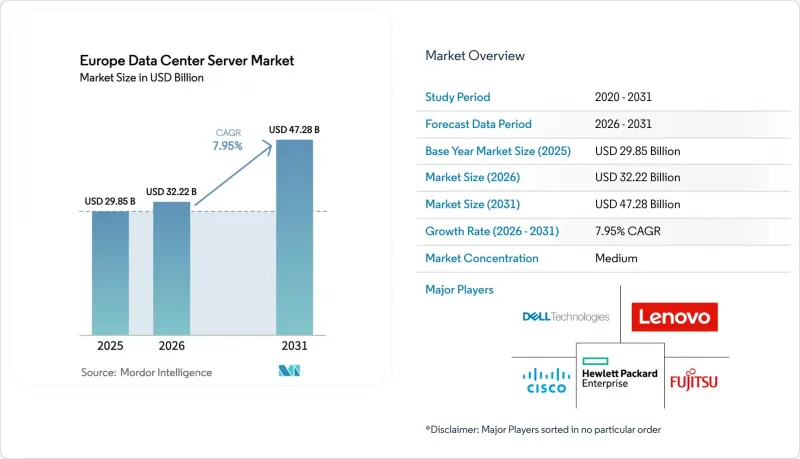
According to Mordor Intelligence, the Europe data center server market size is expected to grow from USD 29.85 billion in 2025 to USD 32.22 billion in 2026 and is forecast to reach USD 47.28 billion by 2031 at 7.95% CAGR over 2026-2031.
This report is Segmented by Data Center Tier(Tier 1 and 2, and More), Form Factor(Half-Height Blades, Full-Height Blades and More), Application(virtualisation and Private Cloud, High-Performance Computing and More), Data Center Type(Hyperscalers Provider and More), End User Industry(BFSI and More)and by Country. The Market Sizes and Forecasts are Provided in Terms of Value (USD) for all the Above Segments.
Europe Data Center Server Market Trends and Insights
Cloud computing & X-as-a-Service adoption
Hyperscalers are building region-specific availability zones, driving sustained demand for rack-scale servers. Microsoft confirmed three new data centers in Northern France, while AWS formed a standalone European Sovereign Cloud entity to satisfy residency rules aws.amazon.com. Dutch operators estimate that data centers now add 7.6% to the national GDP due to such activity. Enterprise case studies, such as Uniper's migration of 10,000 employees to Azure, resulting in 50% fewer IT incidents, illustrate tangible operational gains.
5G rollout & edge nodes
Operators deploy micro-data-centers at base-station sites to meet sub-20 ms latency targets under the EU Edge Observatory program. Ericsson's private 5G network at Calpak's Greek solar-heater plant shows manufacturing use cases, while German Edge Cloud powers Rittal's Industry 4.0 factory with 250+ networked machines.
Escalating CapEx for new facilities
Land costs for 50-acre plots in tier-1 hubs climbed 23% in 2025, while power-allocation queues exceed 36 months.Vantage Data Centers tapped a EUR 720 million (USD 829.16 million) securitization to fund four German builds, showcasing creative financing. Labor scarcity also inflates budgets, prompting developers to pivot toward Poland and Spain where costs remain 15-20% lower.
Other drivers and restraints analyzed in the detailed report include:
- Hyperscale refresh toward GPU/AI servers
- EU Green Deal incentives for liquid cooling
- Supply-chain squeeze on advanced GPUs/CPUs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tier 3 facilities accounted for 71.62% of Europe data center server market share in 2025, a testament to their cost-to-resilience balance. Financial institutions accelerated upgrades after recent outages, adopting Tier 3 for transaction-critical workloads. DZ BANK deployed Hitachi Vantara EverFlex to secure always-on storage, reinforcing this preference. The Europe data center server market size for Tier 4 is projected to expand 9.98% annually as AI and sovereign-cloud operators demand fault-tolerant uptime. Government supercomputer projects, such as Serbia's Eviden contract, validate the rising appeal of Tier 4.
Edge rollouts sustain limited use of Tier 1/2 suites for development environments where proximity matters more than redundancy. However, stricter EU directives on incident reporting could gradually shift even peripheral sites toward Tier 3 certification, underpinning a structural uplift in specification requirements across the Europe data center server market.
Half-height blades retained 63.85% revenue in 2025, anchoring legacy virtualization estates. Lenovo's ThinkSystem V4 line, built on Intel Xeon 6, refreshes this mainstream segment. Europe data center server market size for quarter-height blades is rising fastest at 8.35% CAGR as operators outfit micro-edge nodes inside retail outlets and cell towers.
Full-height blades remain vital for GPU clusters; Cisco's UCS C845A packs eight NVIDIA GPUs within 4 RU, meeting tight rack-power budgets. Modular reference architectures such as NVIDIA MGX allow operators to drop new accelerator cards without replacing rails, extending asset life and lowering TCO.
Complete Report Scope:
- By Data-Center Tier
- Tier 1 and 2
- Tier 3
- Tier 4
- By Form Factor
- Half-height Blades
- Full-height Blades
- Quarter-height / Micro-blades
- By Application / Workload
- Virtualisation and Private Cloud
- High-Performance Computing (HPC)
- Artificial Intelligence/Machine Learning and Data Analytics
- Storage-centric
- Edge / IoT Gateways
- By Data Center Type
- Hyperscalers/Cloud Service Provider
- Colocation Facilities
- Enterprise and Edge
- By End-use Industry
- BFSI
- IT and Telecom
- Healthcare and Life-Sciences
- Manufacturing and Industry 4.0
- Energy and Utilities
- Government and Defence
- By Geography
- Austria
- Belgium
- Denmark
- France
- Germany
- Ireland
- Italy
- Netherlands
- Norway
- Rest of Europe
List of Companies Covered in this Report:
- Dell Technologies
- Hewlett Packard Enterprise
- Lenovo Group
- Cisco Systems
- Fujitsu
- Huawei Technologies
- Inspur Group
- International Business Machines (IBM)
- Quanta Computer
- Super Micro Computer
- Atos SE
- Advanced Micro Devices (AMD)
- Intel Corporation
- Nvidia Corp.
- Foxconn / Hon Hai (including QCT)
- Gigabyte Technology
- MiTAC / TYAN
- ASRock Rack
- Inventec
- Kingston Technology
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Adoption of cloud computing and X-as-a-Service
- 4.2.2 Rapid commercial roll-out of 5G and edge nodes
- 4.2.3 Hyperscale refresh cycle toward GPU/AI servers
- 4.2.4 EU Green Deal incentives for liquid-cooled racks
- 4.2.5 Sovereign AI / EU Data Act pushing in-region compute
- 4.2.6 Rise of modular, prefabricated micro-data-centers
- 4.3 Market Restraints
- 4.3.1 Escalating CapEx for new facilities
- 4.3.2 Volatile electricity and carbon prices
- 4.3.3 Supply-chain squeeze on advanced GPUs/CPUs
- 4.3.4 Stricter waste-heat reuse and PUE regulations
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape (GDPR, EU Data Act, Eco-design)
- 4.6 Technological Outlook (AI accelerators, CXL, liquid cooling)
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Assessment of Macroeconomic Factors on the Market
5 MARKET SIZE and GROWTH FORECASTS (VALUE)
- 5.1 By Data-Center Tier
- 5.1.1 Tier 1 and 2
- 5.1.2 Tier 3
- 5.1.3 Tier 4
- 5.2 By Form Factor
- 5.2.1 Half-height Blades
- 5.2.2 Full-height Blades
- 5.2.3 Quarter-height / Micro-blades
- 5.3 By Application / Workload
- 5.3.1 Virtualisation and Private Cloud
- 5.3.2 High-Performance Computing (HPC)
- 5.3.3 Artificial Intelligence/Machine Learning and Data Analytics
- 5.3.4 Storage-centric
- 5.3.5 Edge / IoT Gateways
- 5.4 By Data Center Type
- 5.4.1 Hyperscalers/Cloud Service Provider
- 5.4.2 Colocation Facilities
- 5.4.3 Enterprise and Edge
- 5.5 By End-use Industry
- 5.5.1 BFSI
- 5.5.2 IT and Telecom
- 5.5.3 Healthcare and Life-Sciences
- 5.5.4 Manufacturing and Industry 4.0
- 5.5.5 Energy and Utilities
- 5.5.6 Government and Defence
- 5.6 By Geography
- 5.6.1 Austria
- 5.6.2 Belgium
- 5.6.3 Denmark
- 5.6.4 France
- 5.6.5 Germany
- 5.6.6 Ireland
- 5.6.7 Italy
- 5.6.8 Netherlands
- 5.6.9 Norway
- 5.6.10 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves (MandA, JVs, Funding)
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Dell Technologies
- 6.4.2 Hewlett Packard Enterprise
- 6.4.3 Lenovo Group
- 6.4.4 Cisco Systems
- 6.4.5 Fujitsu
- 6.4.6 Huawei Technologies
- 6.4.7 Inspur Group
- 6.4.8 International Business Machines (IBM)
- 6.4.9 Quanta Computer
- 6.4.10 Super Micro Computer
- 6.4.11 Atos SE
- 6.4.12 Advanced Micro Devices (AMD)
- 6.4.13 Intel Corporation
- 6.4.14 Nvidia Corp.
- 6.4.15 Foxconn / Hon Hai (including QCT)
- 6.4.16 Gigabyte Technology
- 6.4.17 MiTAC / TYAN
- 6.4.18 ASRock Rack
- 6.4.19 Inventec
- 6.4.20 Kingston Technology
7 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

