PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186153

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186153
Information And Communications Technology (ICT) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the information and communications technology (ICT) market size is expected to increase from USD 6.31 trillion in 2026 to USD 6.68 trillion in 2027 and reach USD 9.09 trillion by 2032, growing at a CAGR of 6.35% over 2027-2032.
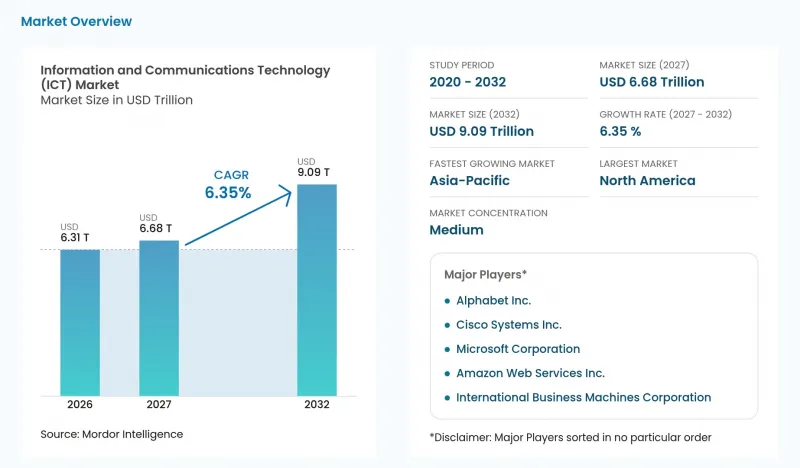
This report is segmented by Type (IT Services and more), Enterprise Size (Large Enterprises and more), Deployment Model (Cloud and more), End-User Industry Vertical (Government and Public Administration and more), and Geography (North America and more). The market forecasts are provided in terms of value (USD), based on availability.
Global Information And Communications Technology (ICT) Market Trends and Insights
Proliferation of Edge Computing and IoT Data Streams
Vodafone Business reported 244 million IoT connections for FY2026. The scale of that connection base illustrates the reach of commercial IoT, while operational uses of device data create an additional opening for edge systems. In September 2025, Nokia and Future Technologies Venture deployed Nokia Edge, private wireless, devices and applications at Maher Terminals' Port Elizabeth facility in New Jersey. The terminal handles 2 million containers annually, and the deployment provides real-time asset tracking and live telemetry. Linking these functions creates a need for coordinated connectivity and local data processing within container-handling operations. The resulting sales opportunity spans the application and connectivity layers required to turn asset signals into usable operational information.
Surge in AI-Optimized Cloud Infrastructure Investments
AI-related cloud expansion creates different requirements for compute assets and the physical capacity supporting service delivery. For the quarter ended June 30, 2026, Microsoft reported USD 41 billion in company-wide capital expenditure, including higher component pricing. Roughly two-thirds went to short-lived assets, primarily CPUs and GPUs supporting solutions using both AI and non-AI infrastructure. The remaining expenditure went to long-lived assets. This mix connects infrastructure investment to compute provisioning as well as durable capacity, creating distinct delivery horizons within the same cloud business. Vendors selling CPUs and GPUs face a shorter replacement cycle than builders of the data-center sites funded from the long-lived share of the same budget.
Escalating Semiconductor Supply-Chain Vulnerabilities
Component availability can prevent strong customer interest from becoming delivered ICT systems. Hewlett Packard Enterprise Company said memory and wafer-capacity constraints limited its ability to fulfill higher customer demand in fiscal Q3 2026. It identified constrained DDR5, DDR4 and NAND supply, with the named memory constraints persisting since the beginning of 2026. HPE tied DDR4 to the older generation and NAND to the flash-drive space, showing exposure across different component uses. For systems suppliers, this breadth makes shipment conversion sensitive to component availability even when finished-system demand is favorable. HPE's ability to turn higher demand into revenue depends on obtaining constrained memory and wafer capacity.
Other drivers and restraints analyzed in the detailed report include:
- Rapid 5G Stand-Alone Core Deployments Accelerating Use Cases
- Regulatory Push for Digital Sovereignty and Secure Cloud Regions
- Mounting Energy Costs of Hyperscale Data Centers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
IT services accounted for a 32.95% share of the information and communications technology (ICT) market size in 2026, making it the largest segment by type. IBM reported USD 21.1 billion in Consulting revenue for the year ended December 31, 2025. Its Consulting work spans Strategy and Technology alongside Intelligent Operations, combining technology change with operational capabilities. By combining those scopes, IBM can earn revenue from running client operations as well as designing change, extending its commercial role beyond the completion of an individual implementation.
IT software is forecast to be the fastest-growing segment, with a 7.35% CAGR over 2027-2032. Salesforce reported USD 10.8 billion in subscription and support revenue in the quarter ended July 31, 2026, up 12% year over year and including USD 440 million from Informatica. Microsoft 365 Commercial cloud revenue increased 14% on a reported basis in the quarter ended June 30, 2026. Salesforce's 12% growth includes the USD 440 million Informatica contribution, so part of that expansion comes from the Informatica portfolio rather than from existing offerings alone. Microsoft 365 Commercial cloud growth of 14% on a reported basis shows a separate large software subscription base expanding at a similar pace.
Large enterprises represented a 61.4% information and communications technology (ICT) market share in 2026, making them the largest enterprise-size segment. Eurostat found that 84.67% of EU enterprises with 250 or more employees or self-employed persons used paid cloud computing services in 2025. In March 2025, UPS agreed to a 10-year collaboration with NTT DATA to modernize its IT infrastructure and data centers. The agreement called for NTT DATA to purchase and operate one UPS mission-critical data center and enable workload colocation using public-cloud and on-premises solutions. For a buyer of this size, the 10-year term turns the contract into a continuing operating relationship rather than a one-time modernization project.
Small and medium enterprises are forecast to be the fastest-growing segment, with a 6.75% CAGR over 2027-2032. In 2025, 52% of EU SMEs bought cloud services. Separately, 74% of UK SME employers used technologies or web-based software for sales or business management in 2025, up 5 percentage points from 2024. Paid cloud and operational software use describe complementary entry points linking external computing services to everyday business tasks. Service packages tied to those sales and management tasks offer a concrete expansion path, with additional capabilities introduced as the scope of use develops.
Complete Report Scope:
- By Type
- Hardware
- Computer Hardware
- Networking Equipment
- Peripherals
- IT Software
- IT Services
- Managed Services
- Business Process Services
- Business Consulting Services
- Cloud Services
- IT Infrastructure
- IT Security
- Communication Services
- Hardware
- By Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
- By Deployment Model
- On-Premise
- Cloud
- Hybrid
- By End-User Industry Vertical
- Government and Public Administration
- BFSI
- Energy and Utilities
- Retail, E-commerce and Logistics
- Manufacturing and Industry 4.0
- Healthcare and Life Sciences
- Oil and Gas (Up/Mid/Down-stream)
- Gaming and Esports
- Other Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America accounted for 39.4% of the information and communications technology (ICT) market size in 2026, making it the largest geography. CBRE reported H1 2026 net absorption of 1,456.2 MW across its primary North American data-center markets, up 11.7% year over year, as hyperscale and AI occupiers competed for limited contiguous power blocks. This combination makes the availability of usable power blocks relevant to supplying the region's computing demand alongside the provision of ICT equipment. Providers that can secure power for new capacity hold the clearer route to North American demand, because occupiers are competing for limited contiguous power blocks.
Asia-Pacific is forecast to be the fastest-growing geography, with an 8.15% CAGR over 2027-2032. In August 2026, Singapore's GovTech reported that more than 70% of eligible government systems ran on its Government on Commercial Cloud platform. GovTech operates a standardized, secure environment for agencies using commercial cloud infrastructure. The platform also supports cloud-native AI, linking the shared environment to additional computing capabilities. For public-sector cloud providers, a shared government platform creates a route to serve eligible systems and cloud-native AI within the same agency environment.
Across South America, Europe, and the Middle East and Africa, demand combines local cloud supply with governance choices and uneven connectivity reach. Microsoft opened Chile Central in June 2025 with 3 independent locations in Santiago Metropolitan Region, while Colombia's 2026 public-cloud framework set conditions for state-entity purchases. In Europe, the Netherlands' July 2025 strategy prioritized shared government cloud technology, while EU business AI use reached 20% in 2025 from 13% in 2024. In the Middle East and Africa, e& UAE's May 2025 commercial standalone-slicing launch for businesses contrasted with 36% population Internet use in ITU's Africa region in 2025. These differences favor service designs matched to local procurement channels and connectivity reach, with advanced capabilities and wider access creating distinct routes to revenue.
- Microsoft Corporation
- Alphabet Inc.
- Amazon Web Services Inc.
- International Business Machines Corporation
- Cisco Systems Inc.
- Oracle Corporation
- Dell Technologies Inc.
- SAP SE
- Hewlett Packard Enterprise Company
- Accenture plc
- Tata Consultancy Services Limited
- Capgemini SE
- Fujitsu Limited
- Huawei Technologies Co. Ltd.
- NEC Corporation
- Salesforce Inc.
- Adobe Inc.
- Infosys Limited
- Wipro Limited
- Tencent Holdings Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of Edge Computing and IoT Data Streams
- 4.2.2 Surge in AI-Optimized Cloud Infrastructure Investments
- 4.2.3 Rapid 5G Stand-Alone Core Deployments Accelerating Use Cases
- 4.2.4 Regulatory Push for Digital Sovereignty and Secure Cloud Regions
- 4.2.5 Growing Preference for Consumption-Based IT Services Models
- 4.2.6 National Digital Public Infrastructure Programs in Emerging Economies
- 4.3 Market Restraints
- 4.3.1 Escalating Semiconductor Supply-Chain Vulnerabilities
- 4.3.2 Mounting Energy Costs of Hyperscale Data Centers
- 4.3.3 Skills Gap in Advanced Cybersecurity and AIOps
- 4.3.4 Fragmented Standards for Interoperable Industry 4.0 Solutions
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Key Use-Cases
- 4.10 Government Projects and Initiatives
- 4.11 Ecosystem Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Hardware
- 5.1.1.1 Computer Hardware
- 5.1.1.2 Networking Equipment
- 5.1.1.3 Peripherals
- 5.1.2 IT Software
- 5.1.3 IT Services
- 5.1.3.1 Managed Services
- 5.1.3.2 Business Process Services
- 5.1.3.3 Business Consulting Services
- 5.1.3.4 Cloud Services
- 5.1.4 IT Infrastructure
- 5.1.5 IT Security
- 5.1.6 Communication Services
- 5.1.1 Hardware
- 5.2 By Enterprise Size
- 5.2.1 Small and Medium Enterprises
- 5.2.2 Large Enterprises
- 5.3 By Deployment Model
- 5.3.1 On-Premise
- 5.3.2 Cloud
- 5.3.3 Hybrid
- 5.4 By End-User Industry Vertical
- 5.4.1 Government and Public Administration
- 5.4.2 BFSI
- 5.4.3 Energy and Utilities
- 5.4.4 Retail, E-commerce and Logistics
- 5.4.5 Manufacturing and Industry 4.0
- 5.4.6 Healthcare and Life Sciences
- 5.4.7 Oil and Gas (Up/Mid/Down-stream)
- 5.4.8 Gaming and Esports
- 5.4.9 Other Verticals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Nigeria
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 Alphabet Inc.
- 6.4.3 Amazon Web Services Inc.
- 6.4.4 International Business Machines Corporation
- 6.4.5 Cisco Systems Inc.
- 6.4.6 Oracle Corporation
- 6.4.7 Dell Technologies Inc.
- 6.4.8 SAP SE
- 6.4.9 Hewlett Packard Enterprise Company
- 6.4.10 Accenture plc
- 6.4.11 Tata Consultancy Services Limited
- 6.4.12 Capgemini SE
- 6.4.13 Fujitsu Limited
- 6.4.14 Huawei Technologies Co. Ltd.
- 6.4.15 NEC Corporation
- 6.4.16 Salesforce Inc.
- 6.4.17 Adobe Inc.
- 6.4.18 Infosys Limited
- 6.4.19 Wipro Limited
- 6.4.20 Tencent Holdings Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

