PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187227

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187227
Philippines Freight And Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the Philippines freight and logistics market size is projected to expand from USD 16.2 billion in 2026 and USD 17.16 billion in 2027 to USD 22.41 billion by 2032, registering a CAGR of 5.48% between 2027 and 2032.
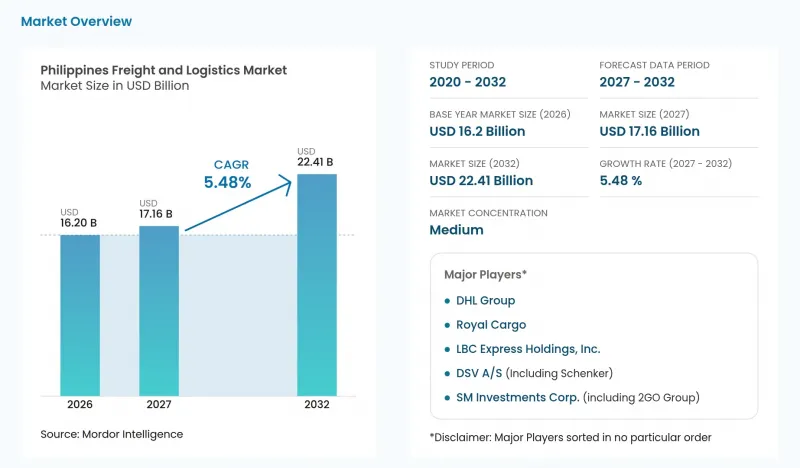
This report is segmented by End-User Industry (Wholesale and Retail Trade, Manufacturing, and more) and Logistics Function (Freight Transport, Freight Forwarding, and more). The market forecasts are provided in terms of value (USD), based on availability.
Philippines Freight And Logistics Market Trends and Insights
Surge in B2C E-Commerce Parcel Volumes
Online consumer activity is strengthening the demand base for parcel delivery in the Philippines. Google, Temasek, and Bain estimate Philippine e-commerce GMV rose from USD 20 billion in 2024 to USD 24 billion in 2025, a 20% increase. Their 2025 report also records Philippine video-commerce transaction volume growing 35% year over year while sellers and stores increased 90%. Rising e-commerce transaction activity and a wider base of sellers and stores strengthen demand for last-mile fulfillment. CEP operators therefore face stronger volume potential, with service density and delivery economics determining how much online growth converts into profitable parcels.
Build Better More Infrastructure Pipeline
Public works are enlarging the physical pipeline that can support freight connectivity. DBM proposed FY2027 Build Better More spending 13.8% above the FY2026 GAA, with funding tied partly to ongoing locally funded and foreign-assisted flagship projects. DBM also reported that the flagship pipeline expanded from 186 to 207 projects worth approximately USD 176.7 billion. The PPP Center reported 251 projects in the Philippine PPP pipeline at the end of 2025 after 13 awards during the year. Carriers and warehouse developers can target corridors according to the stage of the proposed works. Logistics gains depend on procurement and completion, making staged capacity commitments more appropriate than expansion based on pipeline size alone.
Chronic Road Congestion in Metro Manila
Road congestion in Metro Manila constrains freight productivity even when port schedules hold. TomTom's 2025 index recorded Manila at 57% congestion and 143 hours lost during rush hour. In June 2026, trucks often completed only 2 container movements daily versus 3 to 4 previously as terminal waiting, unpredictable congestion, and stricter cutoffs reduced productivity. PHLPost opened EMS hubs in Manila, Makati, and Pasay in January 2025 to reduce handling and improve cost efficiency. Decentralized dispatch can ease exposure for one network, but delays, storage charges, and missed cutoffs continue to raise the cost of serving dense urban routes.
Other drivers and restraints analyzed in the detailed report include:
- Manufacturing Reshoring within ASEAN
- Growth in Temperature-Controlled Food and Pharma Flows
- High Domestic Shipping Costs Across Islands
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wholesale and Retail Trade accounted for a 31.1% share of the Philippines Freight And Logistics Market size in 2026 and is forecast to grow fastest at a 6.1% CAGR during 2027-2032. Philippine Seven's 7-Eleven network reached 4,491 Philippine stores by December 31, 2025, up from 4,130 in 2024. Fourth-quarter same-store sales grew 3.1%, while full-year same-store sales fell 0.9%. Wholesale and retail trade, including motor-vehicle and motorcycle repair, grew 5.2% in 2025 and was the largest contributor to economic expansion. The expanded store network creates a larger distribution footprint despite weaker full-year same-store sales.
The DBCC midterm update reported wholesale and retail trade growth of 5.7% in the first half of 2025 versus 5.2% in the second half of 2024. The later 4.6% fourth-quarter reading shows growth easing into year-end rather than accelerating. In July 2025, Philippine Seven announced distribution centers in Zamboanga City and Ormoc City to support 500 planned new stores, mostly in Visayas and Mindanao. That regional distribution plan makes access to southern outlets a more concrete logistics opportunity than capacity expansion predicated on continually accelerating national trade growth.
Complete Report Scope:
- By End-User Industry
- Agriculture, Fishing, and Forestry
- Construction
- Manufacturing
- Oil and Gas, Mining, and Quarrying
- Wholesale and Retail Trade
- Others
- By Logistics Function
- Courier, Express, and Parcel (CEP)
- By Destination Type
- Domestic
- International
- By Destination Type
- Freight Forwarding
- By Mode of Transport
- Air
- Sea and Inland Waterways
- Others
- By Mode of Transport
- Freight Transport
- By Mode of Transport
- Air
- Pipelines
- Rail
- Road
- Sea and Inland Waterways
- By Mode of Transport
- Warehousing and Storage
- By Temperature Control
- Non-Temperature-Controlled
- Temperature-Controlled
- By Temperature Control
- Other Services
- Courier, Express, and Parcel (CEP)
List of Companies Covered in this Report:
- SM Investments Corp. (including 2GO Group)
- A.P. Moller - Maersk
- AAI Worldwide Logistics
- Air21 Global Inc.
- AP Cargo
- CMA CGM Group (Including CEVA Logistics)
- DHL Group
- DSV A/S (Including Schenker)
- Fast Logistics
- FedEx
- JRS Business Corporation
- Kuehne+Nagel
- LBC Express Holdings, Inc.
- LF Global Logistics Solutions, Inc.
- Mitsui O.S.K. Lines, Ltd.
- Ninja Van Group (Including Ninja Van Philippines)
- NYK (Nippon Yusen Kaisha) Line
- Orient Freight
- Royal Cargo
- United Parcel Service of America, Inc. (UPS)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in B2C E-Commerce Parcel Volumes
- 4.2.2 Build Better More Infrastructure Pipeline
- 4.2.3 Manufacturing Reshoring within ASEAN
- 4.2.4 Growth in Temperature-Controlled Food and Pharma Flows
- 4.2.5 Expansion of Digital Freight-Matching Platforms
- 4.2.6 Nickel-Ore Exports For EV Battery Supply Chains
- 4.3 Market Restraints
- 4.3.1 Chronic Road Congestion in Metro Manila
- 4.3.2 High Domestic Shipping Costs Across Islands
- 4.3.3 Typhoon-Induced Supply-Chain Disruptions
- 4.3.4 Limited Uptake of Cargo Insurance Among SMEs
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Demographics
- 4.9 GDP Distribution by Economic Activity
- 4.10 GDP Growth by Economic Activity
- 4.11 Inflation
- 4.12 Economic Performance and Profile
- 4.12.1 Trends in E-Commerce Industry
- 4.12.2 Trends in Manufacturing Industry
- 4.13 Transport and Storage Sector GDP
- 4.14 Export Trends
- 4.15 Import Trends
- 4.16 Fuel Price
- 4.17 Trucking Operational Costs
- 4.18 Trucking Fleet Size by Type
- 4.19 Logistics Performance
- 4.20 Modal Share
- 4.21 Maritime Fleet Load Carrying Capacity
- 4.22 Liner Shipping Connectivity
- 4.23 Port Calls and Performance
- 4.24 Freight Pricing Trends
- 4.25 Freight Tonnage Trends
- 4.26 Infrastructure
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By End-User Industry
- 5.1.1 Agriculture, Fishing, and Forestry
- 5.1.2 Construction
- 5.1.3 Manufacturing
- 5.1.4 Oil and Gas, Mining, and Quarrying
- 5.1.5 Wholesale and Retail Trade
- 5.1.6 Others
- 5.2 By Logistics Function
- 5.2.1 Courier, Express, and Parcel (CEP)
- 5.2.1.1 By Destination Type
- 5.2.1.1.1 Domestic
- 5.2.1.1.2 International
- 5.2.1.1 By Destination Type
- 5.2.2 Freight Forwarding
- 5.2.2.1 By Mode of Transport
- 5.2.2.1.1 Air
- 5.2.2.1.2 Sea and Inland Waterways
- 5.2.2.1.3 Others
- 5.2.2.1 By Mode of Transport
- 5.2.3 Freight Transport
- 5.2.3.1 By Mode of Transport
- 5.2.3.1.1 Air
- 5.2.3.1.2 Pipelines
- 5.2.3.1.3 Rail
- 5.2.3.1.4 Road
- 5.2.3.1.5 Sea and Inland Waterways
- 5.2.3.1 By Mode of Transport
- 5.2.4 Warehousing and Storage
- 5.2.4.1 By Temperature Control
- 5.2.4.1.1 Non-Temperature-Controlled
- 5.2.4.1.2 Temperature-Controlled
- 5.2.4.1 By Temperature Control
- 5.2.5 Other Services
- 5.2.1 Courier, Express, and Parcel (CEP)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 SM Investments Corp. (including 2GO Group)
- 6.4.2 A.P. Moller - Maersk
- 6.4.3 AAI Worldwide Logistics
- 6.4.4 Air21 Global Inc.
- 6.4.5 AP Cargo
- 6.4.6 CMA CGM Group (Including CEVA Logistics)
- 6.4.7 DHL Group
- 6.4.8 DSV A/S (Including Schenker)
- 6.4.9 Fast Logistics
- 6.4.10 FedEx
- 6.4.11 JRS Business Corporation
- 6.4.12 Kuehne+Nagel
- 6.4.13 LBC Express Holdings, Inc.
- 6.4.14 LF Global Logistics Solutions, Inc.
- 6.4.15 Mitsui O.S.K. Lines, Ltd.
- 6.4.16 Ninja Van Group (Including Ninja Van Philippines)
- 6.4.17 NYK (Nippon Yusen Kaisha) Line
- 6.4.18 Orient Freight
- 6.4.19 Royal Cargo
- 6.4.20 United Parcel Service of America, Inc. (UPS)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

