PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187251

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187251
Thailand Freight And Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
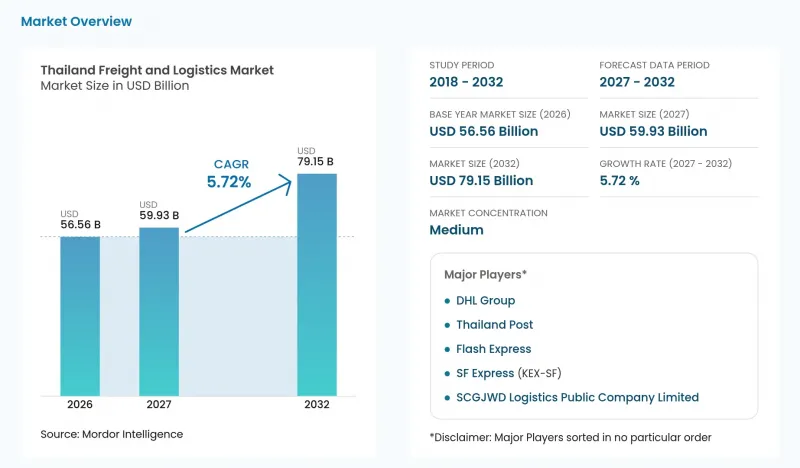
According to Mordor Intelligence, the Thailand freight and logistics market size was valued at USD 56.56 billion in 2026 and estimated to grow from USD 59.93 billion in 2027 to reach USD 79.15 billion by 2032, at a CAGR of 5.72% during the forecast period (2027-2032).
This report is segmented by End User Industry (Manufacturing, Wholesale and Retail Trade, and more) and Logistics Function (Freight Transport, Freight Forwarding, and more). The market forecasts are provided in terms of value (USD), based on availability.
Thailand Freight And Logistics Market Trends and Insights
E-Commerce Boom and Last-Mile Delivery Acceleration
Online merchants need a practical handover point between completed orders and the parcel network that carries goods to customers. Thailand's platform e-commerce GMV grew 51.8% to USD 35.5 billion in 2025 from USD 23.4 billion in 2024. J&T Express Thailand opened a parcel drop-off point at BITEC Bangna in Bangkok on July 11, 2025, at a venue connecting online retailers, small and medium enterprises, and exhibition organizers. On June 25, 2026, KEX Express (Thailand) and Big C planned to expand their jointly operated parcel drop-off and pick-up network to more than 1,700 locations nationwide, citing online merchant parcel demand. Parcel acceptance connects this expanding online sales base with physical collection, giving carriers a merchant-facing entry point into the onward delivery relationship.
Government Mega-Projects (EEC, 2025-26 Plan, Land Bridge)
Port development programs create logistics opportunities in phases, with civil infrastructure preceding the services that depend on new terminal capacity. At Map Ta Phut Industrial Port in Rayong, Gulf MTP LNG Terminal, the private partner, completed Stage 1 infrastructure works for the Phase 3 gas-terminal project on March 31, 2025. EECO prioritizes multimodal transport infrastructure in Chachoengsao, Chon Buri and Rayong, including expansions at Laem Chabang and Map Ta Phut ports. The wider port program provides the freight-relevant opportunity, while the gas-terminal infrastructure milestone concerns a distinct industrial use. Because EECO's port priorities are planned and Map Ta Phut gas terminal operations are scheduled for 2029, port-related freight demand from this driver is expected to build gradually across the forecast period.
Persistently High Logistics Cost (~13-14 % of GDP)
Thailand's logistics burden combines transport expenses with the cost of holding and administering goods, limiting room for added distribution charges. The Office of the National Economic and Social Development Council (NESDC) estimated Thailand's logistics costs at 13.5% of GDP in 2024. The ratio had eased from a preliminary 14.2% in 2023. In 2025, PTG Energy subsidiary PTG Logistics used B100 biodiesel-powered trucks in a backhaul project that reduced fuel consumption by approximately 34,400 liters, or 14% versus its previous transportation model. Estimated transportation costs were 6.5% of GDP against a 13.5% total in 2024, leaving over half the burden outside haulage and limiting haulage savings' effect on shippers' logistics bills.
Other drivers and restraints analyzed in the detailed report include:
- Manufacturing Re-Shoring and China+1 Inflows
- Digitalization (AI/TMS, IoT Visibility, Smart Warehousing)
- Fuel-Price Volatility and Carbon-Pricing Exposure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Manufacturing accounted for a 32.22% share of the Thailand freight and logistics market size in 2026. The largest segment includes high-volume food production, with Thai manufacturers producing 306,222 metric tons of canned fruit and vegetables from April to June 2026, at between 95,753 and 112,686 metric tons a month. Output of that kind recurs every month, so its dispatch is a continuing requirement independent of whether the manufacturer starts another investment project.
Wholesale and retail trade is forecast to be the fastest-growing segment, at a CAGR of 6.25% during 2027-2032. By November 27, 2025, CJ Logistics had commenced operating a 67,000-square-meter center in Wang Noi, Ayutthaya, supplying ambient, chilled, and frozen products to CP AXTRA's Makro stores nationwide. By January 28, 2026, Mowi (Thailand) had established salmon pin-boning within CP AXTRA's temperature-controlled Wang Noi distribution center, with nationwide Makro distribution through a CJ Logistics-operated cold-chain model. This arrangement connects a specialist processing operation with a separate logistics provider's distribution, making the shared center a link between product preparation and store supply. Mowi's salmon products reached Makro stores nationwide through the CJ Logistics-operated cold-chain model, so a processing tenant added product flow to the same operator's store-supply network.
Complete Report Scope:
- By End User Industry
- Agriculture, Fishing, and Forestry
- Construction
- Manufacturing
- Oil and Gas, Mining and Quarrying
- Wholesale and Retail Trade
- Others
- By Logistics Function
- Courier, Express, and Parcel (CEP)
- By Destination Type
- Domestic
- International
- By Destination Type
- Freight Forwarding
- By Mode of Transport
- Air
- Sea and Inland Waterways
- Others
- By Mode of Transport
- Freight Transport
- By Mode of Transport
- Air
- Pipelines
- Rail
- Road
- Sea and Inland Waterways
- By Mode of Transport
- Warehousing and Storage
- By Temperature Control
- Non-Temperature Controlled
- Temperature Controlled
- By Temperature Control
- Other Services
- Courier, Express, and Parcel (CEP)
List of Companies Covered in this Report:
- A.P. Moller - Maersk
- CMA CGM Group (Including CEVA Logistics)
- DHL Group
- DSV A/S (Including DB Schenker)
- FedEx
- Flash Express
- J&T Express
- SCGJWD Logistics Public Company Limited
- Kuehne+Nagel
- LEO Global Logistics Public Co., Ltd.
- Nippon Express Holdings
- Profreight Group Co., Ltd.
- SCG Logistics, Ltd.
- SF Express (KEX-SF)
- Sub Sri Thai Public Co., Ltd.
- Thailand Post
- Toyota Tsusho (Thailand) Co., Ltd.
- Triple i Logistics Public Co., Ltd.
- United Parcel Service of America, Inc. (UPS)
- WICE Logistics Public Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-Commerce Boom and Last-Mile Delivery Acceleration
- 4.2.2 Government Mega-Projects (EEC, 2025-26 Plan, Land Bridge)
- 4.2.3 Manufacturing Re-Shoring and China+1 Inflows
- 4.2.4 Digitalization (AI/TMS, IoT Visibility, Smart Warehousing)
- 4.2.5 Green-Logistics Mandates and Rail Electrification Push
- 4.2.6 Cross-Border CLMV Trade and Trans-Asian Rail Link Uptake
- 4.3 Market Restraints
- 4.3.1 Persistently High Logistics Cost (~13-14 % of GDP)
- 4.3.2 Fuel-Price Volatility and Carbon-Pricing Exposure
- 4.3.3 Parcel-Carrier Margin Squeeze by E-Commerce Platforms
- 4.3.4 U.S. Tariff Risks on Thai Exports (Autos, Electronics)
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Demographics
- 4.9 GDP Distribution by Economic Activity
- 4.10 GDP Growth by Economic Activity
- 4.11 Inflation
- 4.12 Economic Performance and Profile
- 4.12.1 Trends in E-Commerce Industry
- 4.12.2 Trends in Manufacturing Industry
- 4.13 Transport and Storage Sector GDP
- 4.14 Export Trends
- 4.15 Import Trends
- 4.16 Fuel Price
- 4.17 Trucking Operational Costs
- 4.18 Trucking Fleet Size by Type
- 4.19 Major Truck Suppliers
- 4.20 Logistics Performance
- 4.21 Modal Share
- 4.22 Maritime Fleet Load Carrying Capacity
- 4.23 Liner Shipping Connectivity
- 4.24 Port Calls and Performance
- 4.25 Freight Pricing Trends
- 4.26 Freight Tonnage Trends
- 4.27 Infrastructure
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By End User Industry
- 5.1.1 Agriculture, Fishing, and Forestry
- 5.1.2 Construction
- 5.1.3 Manufacturing
- 5.1.4 Oil and Gas, Mining and Quarrying
- 5.1.5 Wholesale and Retail Trade
- 5.1.6 Others
- 5.2 By Logistics Function
- 5.2.1 Courier, Express, and Parcel (CEP)
- 5.2.1.1 By Destination Type
- 5.2.1.1.1 Domestic
- 5.2.1.1.2 International
- 5.2.1.1 By Destination Type
- 5.2.2 Freight Forwarding
- 5.2.2.1 By Mode of Transport
- 5.2.2.1.1 Air
- 5.2.2.1.2 Sea and Inland Waterways
- 5.2.2.1.3 Others
- 5.2.2.1 By Mode of Transport
- 5.2.3 Freight Transport
- 5.2.3.1 By Mode of Transport
- 5.2.3.1.1 Air
- 5.2.3.1.2 Pipelines
- 5.2.3.1.3 Rail
- 5.2.3.1.4 Road
- 5.2.3.1.5 Sea and Inland Waterways
- 5.2.3.1 By Mode of Transport
- 5.2.4 Warehousing and Storage
- 5.2.4.1 By Temperature Control
- 5.2.4.1.1 Non-Temperature Controlled
- 5.2.4.1.2 Temperature Controlled
- 5.2.4.1 By Temperature Control
- 5.2.5 Other Services
- 5.2.1 Courier, Express, and Parcel (CEP)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 A.P. Moller - Maersk
- 6.4.2 CMA CGM Group (Including CEVA Logistics)
- 6.4.3 DHL Group
- 6.4.4 DSV A/S (Including DB Schenker)
- 6.4.5 FedEx
- 6.4.6 Flash Express
- 6.4.7 J&T Express
- 6.4.8 SCGJWD Logistics Public Company Limited
- 6.4.9 Kuehne+Nagel
- 6.4.10 LEO Global Logistics Public Co., Ltd.
- 6.4.11 Nippon Express Holdings
- 6.4.12 Profreight Group Co., Ltd.
- 6.4.13 SCG Logistics, Ltd.
- 6.4.14 SF Express (KEX-SF)
- 6.4.15 Sub Sri Thai Public Co., Ltd.
- 6.4.16 Thailand Post
- 6.4.17 Toyota Tsusho (Thailand) Co., Ltd.
- 6.4.18 Triple i Logistics Public Co., Ltd.
- 6.4.19 United Parcel Service of America, Inc. (UPS)
- 6.4.20 WICE Logistics Public Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

