PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187321

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187321
Thailand Foodservice - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the Thailand foodservice market size was valued at USD 38.1 billion in 2026 and estimated to grow from USD 41 billion in 2027 to reach USD 57.24 billion by 2032, at a CAGR of 6.9% during the forecast period (2027-2032).
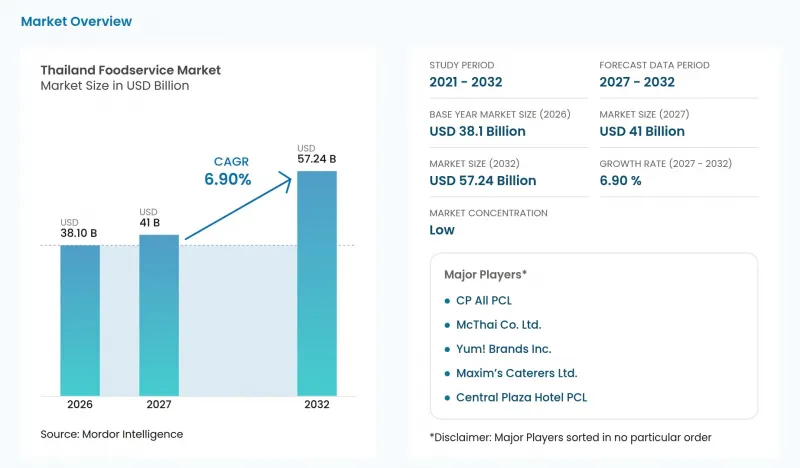
This report is segmented by Foodservice Type (Quick Service Restaurants, Full Service Restaurants, and more), Outlet (Independent Outlets and Chained Outlets), Locations (Standalone, Retail, and more), and Service Type (Dine-in, Takeaway, and more). The market forecasts are provided in terms of value (USD), based on availability.
Thailand Foodservice Market Trends and Insights
Surging demand for convenience and ready-to-eat
Convenience-led demand can favor familiar full meals when speed must be combined with affordability and everyday availability. LINE MAN Wongnai reported more than 65 million rice-and-curry orders in Thailand in 2025, up 8% year over year. The platform said convenience, speed, affordability, and everyday meal availability met consumer needs during cost control. Those characteristics link convenience to routine meal provision, rather than only to occasional or premium restaurant purchases. For participating rice-and-curry shops, the commercial attraction is a channel in which the complete meal itself can become the repeat purchase proposition. Pricing a complete meal for routine spending fits this demand better than charging a premium for speed alone.
Expansion of international/QSR and specialty restaurant brands
Restaurant-brand expansion can increase foodservice demand by giving customers additional occasions to choose a prepared meal from a recognizable concept. MK Restaurant Group opened 24 restaurant outlets in Thailand in 2025, including 15 Bonus Suki restaurants. The portfolio additions also included 2 Yayoi Japanese restaurants and 3 Laem Charoen Seafood restaurants. The group said its Bonus Suki buffet concept, which began operating in the second half of 2025, continued expanding its branch network in Q1 2026. That continuation connects the new format to repeated site deployment, extending its commercial relevance beyond an isolated launch. A repeatable buffet concept gives specialty operators a way to add coverage without making each new site depend on a different dining proposition.
Rising costs of imported ingredients and packaging materials
Israeli airstrikes on Iran, US air operations, and Iranian retaliation across the Persian Gulf began on February 28, 2026. KASIKORN Research Center reported that higher energy prices were gradually raising Thai restaurant and beverage businesses' raw-material and packaging costs in 2026. The center reported selling-price increases of 10% to 20% compared with levels before the conflict. S&P Syndicate's February 2026 outlook also identified imported raw-material price volatility as a prospective margin pressure during 2026. With S&P Syndicate expecting weakened consumer purchasing power, further input increases leave operators less room to protect margins through menu prices.
Other drivers and restraints analyzed in the detailed report include:
- Emergence of plant-based and flexitarian food trends
- Rise of food truck, pop-up, and alternative dining models
- Stringent government food safety and labeling regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Quick service restaurants accounted for a 50.59% share of the Thailand foodservice market size in 2026. KFC Thailand General Manager Sasipinthu Chandrasak reported 1,242 KFC outlets across all 77 provinces in October 2026. A network of that reach can serve local meal occasions through established outlets, rather than depend on customers traveling to a single dining destination. The footprint makes geographic access a substantial part of the segment's commercial proposition alongside the food itself. That reach broadens the potential meal base, but also makes maintaining a consistent service proposition across provincial outlets a central operating task.
Cloud kitchens are forecast to be the fastest-growing segment, with a CAGR of 24.4% during 2027-2032. Delivery-focused production separates food preparation from the provision of a dining room, allowing capacity to be organized around cooking and dispatch. For a kitchen operator, the relevant catchment is the area from which orders can arrive and completed meals can reach customers. By January 6, 2026, LINE MAN Wongnai and private-sector partners had opened a temporary cloud kitchen in Hat Yai, Songkhla, where small flood-affected restaurant operators could prepare and sell food while their shops were repaired. Temporary shared kitchens can restore preparation capacity before dining premises reopen, but the replacement site still has to reach the operator's customers.
Independent outlets represented a 73.65% Thailand foodservice market share in 2026. Their ownership structure allows a restaurant proposition to be shaped around a particular operator and local catchment rather than a common chain identity. For an owner-operated business, that flexibility can connect menu choices, service style, and the use of premises within one commercial decision. Without a shared chain brand, an independent outlet's revenue rests on its own repeat customers, so service consistency matters more to it than reach.
Chained outlets are forecast to be the fastest-growing segment, at a CAGR of 7.4% during 2027-2032. Thai Beverage operated 862 food outlets across Thailand on September 30, 2025, following 35 net new store openings compared with the prior year. In this model, the commercial unit is a network that can add or remove locations while maintaining a wider operating presence. At 35 net additions on an estate of 862 outlets, growth in this example was incremental, making the existing network important alongside new-site selection.
Complete Report Scope:
- By Foodservice Type
- Cafe and Bars
- By Cuisine
- Bars and Pubs
- Cafe
- Juice/Smoothie/Desserts Bars
- Specialist Coffee and Tea Shops
- By Cuisine
- Cloud Kitchen
- Full Service Restaurants
- By Cuisine
- Asian
- European
- Latin American
- Middle Eastern
- North American
- Other FSR Cuisines
- By Cuisine
- Quick Service Restaurants
- By Cuisine
- Bakeries
- Burger
- Ice Cream
- Meat-based Cuisines
- Pizza
- Other QSR Cuisines
- By Cuisine
- Cafe and Bars
- By Outlet
- Chained Outlets
- Independent Outlets
- By Locations
- Leisure
- Lodging
- Retail
- Standalone
- Travel
- By Service Type
- Dine-in
- Takeaway
- Delivery
List of Companies Covered in this Report:
- Central Plaza Hotel PCL
- CP All PCL
- Yum! Brands Inc.
- Maxim's Caterers Ltd.
- McThai Co. Ltd.
- Minor International PCL
- MK Restaurant Group PCL
- Panthera Group Co. Ltd.
- Prime Road Power PCL
- PTT Oil & Retail Business PCL
- Thai Beverage PCL
- Global Franchise Architects Co.
- Zen Corporation Group PCL
- Starbucks Coffee
- Black Canyon (Thailand)
- S&P Syndicate PCL
- Oishi Holding Co. Ltd.
- Au Bon Pain (Thailand)
- The Pizza Company
- After You PCL
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging demand for convenience and ready-to-eat
- 4.2.2 Expansion of international/QSR and specialty restaurant brands
- 4.2.3 Emergence of plant-based and flexitarian food trends
- 4.2.4 Rise of food truck, pop-up, and alternative dining models
- 4.2.5 Strong cafe and coffee culture-expanding beyond metropolitan areas
- 4.2.6 Proliferation of high-quality bakery and dessert brands
- 4.3 Market Restraints
- 4.3.1 Rising costs of imported ingredients and packaging materials
- 4.3.2 Stringent government food safety and labeling regulations
- 4.3.3 Supply chain vulnerability to climate/weather shocks
- 4.3.4 Fragmented supplier landscape and distribution inefficiencies
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 KEY INDUSTRY TRENDS
- 4.8.1 Number of Outlets
- 4.8.2 Average Order Value
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Foodservice Type
- 5.1.1 Cafe and Bars
- 5.1.1.1 By Cuisine
- 5.1.1.1.1 Bars and Pubs
- 5.1.1.1.2 Cafe
- 5.1.1.1.3 Juice/Smoothie/Desserts Bars
- 5.1.1.1.4 Specialist Coffee and Tea Shops
- 5.1.1.1 By Cuisine
- 5.1.2 Cloud Kitchen
- 5.1.3 Full Service Restaurants
- 5.1.3.1 By Cuisine
- 5.1.3.1.1 Asian
- 5.1.3.1.2 European
- 5.1.3.1.3 Latin American
- 5.1.3.1.4 Middle Eastern
- 5.1.3.1.5 North American
- 5.1.3.1.6 Other FSR Cuisines
- 5.1.3.1 By Cuisine
- 5.1.4 Quick Service Restaurants
- 5.1.4.1 By Cuisine
- 5.1.4.1.1 Bakeries
- 5.1.4.1.2 Burger
- 5.1.4.1.3 Ice Cream
- 5.1.4.1.4 Meat-based Cuisines
- 5.1.4.1.5 Pizza
- 5.1.4.1.6 Other QSR Cuisines
- 5.1.4.1 By Cuisine
- 5.1.1 Cafe and Bars
- 5.2 By Outlet
- 5.2.1 Chained Outlets
- 5.2.2 Independent Outlets
- 5.3 By Locations
- 5.3.1 Leisure
- 5.3.2 Lodging
- 5.3.3 Retail
- 5.3.4 Standalone
- 5.3.5 Travel
- 5.4 By Service Type
- 5.4.1 Dine-in
- 5.4.2 Takeaway
- 5.4.3 Delivery
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Central Plaza Hotel PCL
- 6.4.2 CP All PCL
- 6.4.3 Yum! Brands Inc.
- 6.4.4 Maxim's Caterers Ltd.
- 6.4.5 McThai Co. Ltd.
- 6.4.6 Minor International PCL
- 6.4.7 MK Restaurant Group PCL
- 6.4.8 Panthera Group Co. Ltd.
- 6.4.9 Prime Road Power PCL
- 6.4.10 PTT Oil & Retail Business PCL
- 6.4.11 Thai Beverage PCL
- 6.4.12 Global Franchise Architects Co.
- 6.4.13 Zen Corporation Group PCL
- 6.4.14 Starbucks Coffee
- 6.4.15 Black Canyon (Thailand)
- 6.4.16 S&P Syndicate PCL
- 6.4.17 Oishi Holding Co. Ltd.
- 6.4.18 Au Bon Pain (Thailand)
- 6.4.19 The Pizza Company
- 6.4.20 After You PCL
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

