PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187752

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187752
Singapore Foodservice - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the Singapore foodservice market size was valued at USD 34.24 billion in 2026 and estimated to grow from USD 40.55 billion in 2027 to reach USD 91.52 billion by 2032, at a CAGR of 17.68% during the forecast period (2027-2032).
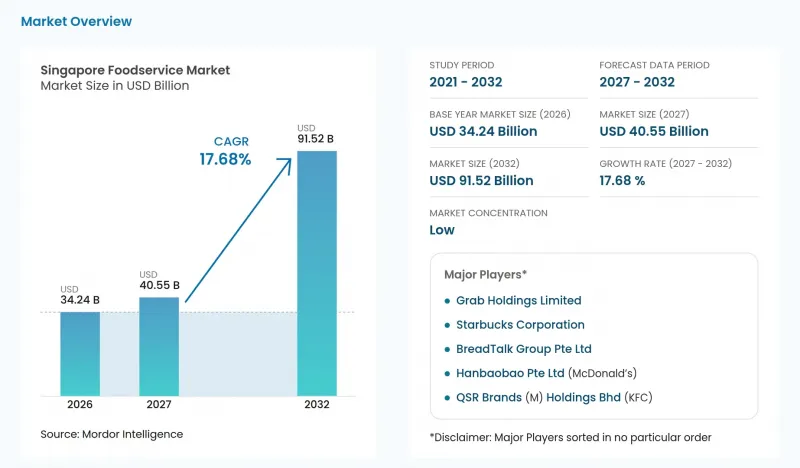
This report is segmented by Service Type (Dine-In, Takeaway, and Delivery), Foodservice Type (Quick Service Restaurants, Full Service Restaurants, Cafes and Bars, and Cloud Kitchen), Outlet (Independent Outlet and Chained Outlet), and Location (Standalone, Retail, Lodging, Leisure, and Travel). The market forecasts are provided in terms of value (USD), based on availability.
Singapore Foodservice Market Trends and Insights
Growing demand for specialty beverages and a robust coffee culture
Coffee-chain expansion can make prepared beverages a more accessible purchase and create additional occasions for foodservice spending between meals. Luckin Coffee opened 30 net new stores in Singapore during 2025. That expansion gives the operator more locations from which to compete for routine beverage purchases and build a recognizable service offer. For beverage operators, the commercial value of additional locations depends on making coffee convenient enough to become a repeat purchase. Each added store's contribution to demand depends on attracting occasions that nearby outlets were not already serving.
Increasing preference for social and post-work gatherings
A shared meal can give a social gathering a practical destination, creating foodservice demand around the group rather than an individual eating schedule. Srisun Express operator Elan Goven said in August 2026 that she thought people generally had begun making a more deliberate effort to socialize and spend time together. For restaurants, the opportunity is to accommodate that joint occasion through seating and service that let companions eat together.
Challenges in adhering to regulations and navigating licensing complexities
A food-shop opening can lose trading time when its licensing submission requires correction before approval. For food-shop license applications, the Singapore Food Agency (SFA) says rectifications or clarifications may slow processing, and incomplete applications are rejected and must be resubmitted. The distinction matters commercially because a correctable query and a rejected application create different paths to reaching the point of serving customers. Operators preparing a new outlet therefore face a sequencing risk, with the start of revenue dependent on satisfying the submission requirements. This conditional barrier can make an opening timetable less dependable and extend the period before a foodservice investment begins earning sales.
Other drivers and restraints analyzed in the detailed report include:
- Rising use of digital payments and contactless transaction methods
- Demand for unique dining experiences and social engagement
- Workforce shortages and elevated employee turnover
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dine-in accounted for a 64.88% share of the Singapore foodservice market size in 2026, making it the largest segment by service type. In early July 2025, Amanda Chia and Alex Ng opened Beth, a 55-seat restaurant on Casuarina Road. Later that month, CNA Lifestyle reported that customers were waiting about an hour for a table. The example highlights a capacity trade-off for dine-in operators, because a queue demonstrates interest while the number of customers served depends on how the venue uses its tables and service capacity.
Delivery is forecast to be the fastest-growing segment by service type, at a CAGR of 19.4% during 2027-2032. On April 8, 2025, Grab said GrabFood for One was available in Singapore, offering solo diners one-person meals with no small-order fees and a fixed, low delivery fee. That structure lets a customer order a solo meal without increasing the basket merely to avoid a small-order fee.
Quick-service restaurants represented a 66.9% Singapore foodservice market share in 2026, making them the largest segment by foodservice type. McDonald's Singapore had more than 150 restaurants islandwide in June 2025. That network illustrates the breadth through which a standardized meal format can reach customers, giving the operator multiple points of service rather than depending on one dining destination.
Cloud kitchens are forecast to be the fastest-growing segment by foodservice type, at a CAGR of 19.35% during 2027-2032. KitchenBASE reports 10 operating commercial kitchen facilities in Singapore that it describes as meeting Food Shop License and Food Processing License needs. Turning that premises provision into a delivery business requires enough meal orders to use preparation and dispatch capacity productively.
Complete Report Scope:
- By Service Type
- Dine-In
- Takeaway
- Delivery
- By Foodservice Type
- Cafes and Bars
- By Cuisine
- Bars and Pubs
- Cafes
- Juice/Smoothie/Desserts Bars
- Specialist Coffee and Tea Shops
- By Cuisine
- Cloud Kitchen
- Full Service Restaurants
- By Cuisine
- Asian
- European
- Latin American
- Middle Eastern
- North American
- Other Full Service Restaurants Cuisines
- By Cuisine
- Quick Service Restaurants
- By Cuisine
- Bakeries
- Burger
- Ice Cream
- Meat-based Cuisines
- Pizza
- Other Quick Service Restaurants Cuisines
- By Cuisine
- Cafes and Bars
- By Outlet
- Chained Outlet
- Independent Outlet
- By Location
- Leisure
- Lodging
- Retail
- Standalone
- Travel
List of Companies Covered in this Report:
- BreadTalk Group Pte Ltd
- Crystal Jade Culinary Concepts Holding
- DFI Retail Group Holdings Limited
- Doctor's Associates LLC (Subway)
- Fidelis Express Holdings Pte. Ltd. (Pizza Express)
- Foodpanda (Delivery Hero SE)
- Grab Holdings Limited
- Hanbaobao Pte Ltd (McDonald's)
- Jollibee Foods Corporation
- Nando's Chickenland Singapore Pte Ltd
- Paradise Group Holdings Pte Ltd
- QSR Brands (M) Holdings Bhd (KFC)
- Restaurant Brands International Inc.
- Sakae Holdings Ltd
- No Signboard Holdings Ltd
- Starbucks Corporation
- Paradise Group
- Tung Lok Restaurants (2000) Ltd
- FairPrice Group (Kopitiam)
- 4Fingers Singapore Pte Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand for specialty beverages and a robust coffee culture
- 4.2.2 Increasing preference for social and post-work gatherings
- 4.2.3 Rising use of digital payments and contactless transaction methods
- 4.2.4 Demand for unique dining experiences and social engagement
- 4.2.5 Shifting consumer preferences and expanding menu offerings
- 4.2.6 Expansion of the tourism and hospitality sector
- 4.3 Market Restraints
- 4.3.1 Challenges in adhering to regulations and navigating licensing complexities
- 4.3.2 Workforce shortages and elevated employee turnover
- 4.3.3 Brand cannibalization in multi-brand groups
- 4.3.4 Increasing raw material costs and disruptions in the supply chain
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Industry Trend Analysis
- 4.8.1 Number of Outlets
- 4.8.2 Average Order Value
- 4.8.3 Menu Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Dine-In
- 5.1.2 Takeaway
- 5.1.3 Delivery
- 5.2 By Foodservice Type
- 5.2.1 Cafes and Bars
- 5.2.1.1 By Cuisine
- 5.2.1.1.1 Bars and Pubs
- 5.2.1.1.2 Cafes
- 5.2.1.1.3 Juice/Smoothie/Desserts Bars
- 5.2.1.1.4 Specialist Coffee and Tea Shops
- 5.2.1.1 By Cuisine
- 5.2.2 Cloud Kitchen
- 5.2.3 Full Service Restaurants
- 5.2.3.1 By Cuisine
- 5.2.3.1.1 Asian
- 5.2.3.1.2 European
- 5.2.3.1.3 Latin American
- 5.2.3.1.4 Middle Eastern
- 5.2.3.1.5 North American
- 5.2.3.1.6 Other Full Service Restaurants Cuisines
- 5.2.3.1 By Cuisine
- 5.2.4 Quick Service Restaurants
- 5.2.4.1 By Cuisine
- 5.2.4.1.1 Bakeries
- 5.2.4.1.2 Burger
- 5.2.4.1.3 Ice Cream
- 5.2.4.1.4 Meat-based Cuisines
- 5.2.4.1.5 Pizza
- 5.2.4.1.6 Other Quick Service Restaurants Cuisines
- 5.2.4.1 By Cuisine
- 5.2.1 Cafes and Bars
- 5.3 By Outlet
- 5.3.1 Chained Outlet
- 5.3.2 Independent Outlet
- 5.4 By Location
- 5.4.1 Leisure
- 5.4.2 Lodging
- 5.4.3 Retail
- 5.4.4 Standalone
- 5.4.5 Travel
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BreadTalk Group Pte Ltd
- 6.4.2 Crystal Jade Culinary Concepts Holding
- 6.4.3 DFI Retail Group Holdings Limited
- 6.4.4 Doctor's Associates LLC (Subway)
- 6.4.5 Fidelis Express Holdings Pte. Ltd. (Pizza Express)
- 6.4.6 Foodpanda (Delivery Hero SE)
- 6.4.7 Grab Holdings Limited
- 6.4.8 Hanbaobao Pte Ltd (McDonald's)
- 6.4.9 Jollibee Foods Corporation
- 6.4.10 Nando's Chickenland Singapore Pte Ltd
- 6.4.11 Paradise Group Holdings Pte Ltd
- 6.4.12 QSR Brands (M) Holdings Bhd (KFC)
- 6.4.13 Restaurant Brands International Inc.
- 6.4.14 Sakae Holdings Ltd
- 6.4.15 No Signboard Holdings Ltd
- 6.4.16 Starbucks Corporation
- 6.4.17 Paradise Group
- 6.4.18 Tung Lok Restaurants (2000) Ltd
- 6.4.19 FairPrice Group (Kopitiam)
- 6.4.20 4Fingers Singapore Pte Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

