PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187324

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187324
Malaysia Construction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the Malaysia construction market size is projected to expand from USD 41.2 billion in 2026 and USD 44.77 billion in 2027 to USD 66.15 billion by 2032, registering a CAGR of 8.12% between 2027 and 2032.
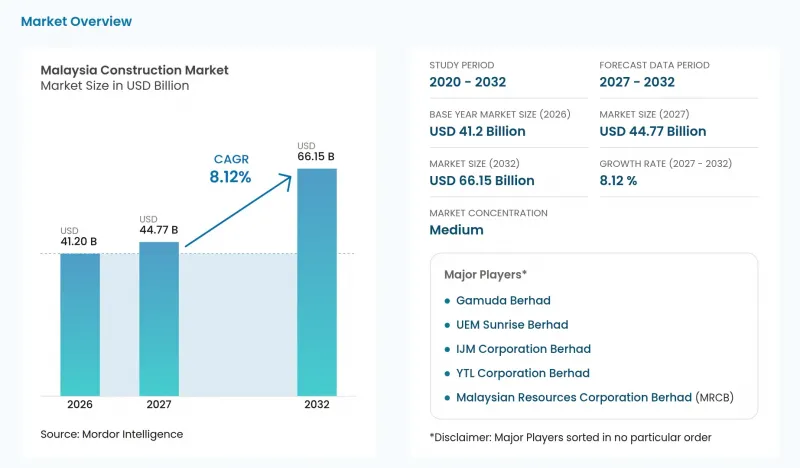
This report is segmented by Sector (Residential, Infrastructure, and more), Construction Type (New Construction and Renovation), Construction Method (Conventional On-Site and Modern Methods of Construction), Investment Source (Private and Public), and Geography (Rest of Malaysia, Selangor, and more). The market forecasts are provided in terms of value (USD), based on availability.
Malaysia Construction Market Trends and Insights
Government mega-infrastructure pipeline (ECRL, MRT 3, Pan-Borneo, Penang LRT)
The government rail pipeline combines commissioning work with construction extending into the forecast period. Malaysia Rail Link reported that East Coast Rail Link (ECRL) Phase 1, covering Kota Bharu to Gombak, was 98.16% complete as of September 2026. That month, the owner said testing and commissioning were progressing well as it worked toward opening the railway as early as mid-December 2026. For Penang's Mutiara Line, SRS Consortium's civil Package 1 took effect on June 23, 2025, after contractual conditions were fulfilled, followed by MRT Corp's July 15 Notice to Proceed. MRT Corp said construction began in 2025, with operations expected in December 2031. This longer delivery horizon provides a construction opportunity for civil and rail-systems contractors beyond the testing and commissioning work associated with ECRL Phase 1.
Public-private partnership funding & Budget-2025 flood-mitigation allocations
Flood-protection funding supports construction demand through a mix of continuing schemes and planned starts across several states. Budget 2026 allocated funding for 43 high-priority Flood Mitigation Plan projects, including 12 new projects announced to commence in 2026. The named new schemes included Sungai Mengkibol in Johor, Sungai Nyiur in Penang and Sungai Buloh Phase 2 in Selangor. This spread gives civil contractors with a focused state footprint potential access to a national funding priority. On October 9, 2026, the Budget 2027 speech reported 6 flood-mitigation projects completed and 82 under implementation according to schedule. Commercial access therefore depends on readiness to deliver an individual river scheme, alongside the scale of the overall allocation.
Escalating cement & steel costs
Material inflation can constrain construction commitments through both higher input costs and uneven exposure across locations. In September 2026, the Department of Statistics Malaysia (DOSM) reported that its cement unit price index was 0.6% to 7.4% higher year over year across covered areas in Peninsular Malaysia, Sabah and Sarawak. Its steel unit price index was 0.1% to 5.1% higher year over year in most areas of those territories during the same month. The differing ranges make a single national escalation allowance an imperfect basis for pricing material-intensive work. For a contractor committing to a project price, an underestimate can reduce the earnings available from delivery. For an owner seeking price certainty, that exposure can instead appear in a higher construction quote.
Other drivers and restraints analyzed in the detailed report include:
- Affordable-housing push for urban middle-income households
- Surge in FDI-led industrial & logistics facilities
- Skilled-labor shortages and rising wage floor
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Residential accounted for a 43.83% share of the Malaysia construction market size in 2026, making it the largest segment. DOSM reported that residential-building construction work done increased 8.7% year over year in Q2 2026. In December 2025, the Ministry of Housing and Local Government (KPKT) reported that 366 new urban homes had been built for low-income households under the 12th Malaysia Plan. That month, Haily Group's wholly owned Haily Construction subsidiary accepted Arkitek N. Kang's award on Setia Indah's behalf at Taman Setia Tropika, Johor Bahru, covering 108 affordable 2-story townhouses at Residensi Lili, 203 2-story terrace houses at Summera Grove and external infrastructure. Residential contractors can therefore serve program-funded urban homes and differentiated developer commissions within a growing category, supporting distinct offerings across housing tiers and separate client channels.
Infrastructure is the fastest-growing segment, with a projected 9.3% CAGR between 2027 and 2032. DOSM reported that civil engineering construction work done increased 2.7% year over year in value in Q2 2026. IJM Construction accepted New Pantai Expressway's design-and-build award for a fully elevated 15-kilometer highway extension, including ramps, in southern Kuala Lumpur on November 5, 2025, with construction scheduled to start in Q4 2025 and finish within 48 months, extending the delivery pipeline into the forecast period. Commercial construction includes Sunway Square in Bandar Sunway, completed in 2025 for Sunway South Quay Sdn Bhd with office and commercial space, a cinema, private educational institutions and a performing-arts center. This mix gives the contractor a multi-use coordination brief, where commercial value comes from delivering different occupancy requirements within one building.
New construction represented a 75.53% Malaysia construction market share in 2026 and is the fastest-growing segment, with a projected 8.26% CAGR between 2027 and 2032. In January 2025, MRT Mutiara Sdn Bhd, an MRT Corporation subsidiary, awarded Gamuda's 60%-owned SRS Consortium the first civil works package for Penang's Mutiara Line. The package covered a 23.7-kilometer elevated viaduct, 19 above-ground stations and one provisional station on Island A of the Penang South Reclamation. The design-and-build package combines linear structures with station delivery, placing coordination of those civil elements within a single construction brief. For new-build contractors, such scope rewards the ability to manage repeated structures and differentiated station works as one delivery program.
Renovation has an institutional buyer route through KPKT's Tabung Penyelenggaraan Perumahan Malaysia (TPPM) program, which supports repair and maintenance of privately owned low- and lower-middle-cost stratified housing outside Kuala Lumpur. Joint management bodies (JMBs) or management corporations (MCs) submit completed applications to the local-authority Commissioner of Buildings for review and verification before referral to the National Housing Department for KPKT consideration. The July 2026 guide provides for 100% financing of maintenance costs and requires the local authority's technical division to verify preliminary project costs. Final approval and funding depend on available allocations, with priority for schemes with an established JMB or MC, and local authorities or federal or state government agencies implement approved projects. For repair contractors, this creates an institutional buyer channel even when the properties being restored are privately owned.
Complete Report Scope:
- By Sector
- Residential
- Apartments / Condominiums
- Villas / Landed Houses
- Commercial
- Office
- Retail
- Industrial & Logistics
- Others
- Infrastructure
- Transportation Infrastructure
- Roadways
- Railways
- Airways
- Others
- Energy & Utilities
- Others
- Transportation Infrastructure
- Residential
- By Construction Type
- New Construction
- Renovation
- By Construction Method
- Conventional On-Site
- Modern Methods of Construction
- By Investment Source
- Public
- Private
- By Geography
- Selangor
- Johor
- Wilayah Persekutuan
- Rest of Malaysia
List of Companies Covered in this Report:
- Gamuda Berhad
- IJM Corporation Berhad
- YTL Corporation Berhad
- Malaysian Resources Corporation Berhad (MRCB)
- UEM Sunrise Berhad
- WCT Holdings Berhad
- Sunway Construction Group Berhad
- Sime Darby Property Berhad
- Mah Sing Group Berhad
- S P Setia Berhad
- Crest Builder Holdings Berhad
- Kerjaya Prospek Group Berhad
- TRC Synergy Berhad
- Hock Seng Lee Berhad
- Kimlun Corporation Berhad
- Gadang Holdings Berhad
- Econpile Holdings Berhad
- LFE Corporation Berhad
- Pentamaster Corporation Berhad (for industrial facilities)
- China Communications Construction Co. Ltd. (Malaysia unit)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government mega-infrastructure pipeline (ECRL, MRT 3, Pan-Borneo, Penang LRT)
- 4.2.2 Public-private partnership funding & Budget-2025 flood-mitigation allocations
- 4.2.3 Affordable-housing push for urban middle-income households
- 4.2.4 Surge in FDI-led industrial & logistics facilities
- 4.2.5 Hyperscale data-center & 5G infrastructure build-out
- 4.2.6 Johor-Singapore SEZ catalyzing cross-border projects
- 4.3 Market Restraints
- 4.3.1 Escalating cement & steel costs
- 4.3.2 Skilled-labor shortages and rising wage floor
- 4.3.3 Land-acquisition & permitting delays
- 4.3.4 Diesel-subsidy rationalization inflating haulage costs
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Government Initiatives & Vision
- 4.9 Pricing (Construction Materials) and Construction Cost (Materials, Labour, Equipment) Analysis
- 4.10 Comparison of Key Industry Metrics of Malaysia with Other Countries
- 4.11 Key Upcoming/Ongoing Projects (with a focus on Mega Projects)
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Sector
- 5.1.1 Residential
- 5.1.1.1 Apartments / Condominiums
- 5.1.1.2 Villas / Landed Houses
- 5.1.2 Commercial
- 5.1.2.1 Office
- 5.1.2.2 Retail
- 5.1.2.3 Industrial & Logistics
- 5.1.2.4 Others
- 5.1.3 Infrastructure
- 5.1.3.1 Transportation Infrastructure
- 5.1.3.1.1 Roadways
- 5.1.3.1.2 Railways
- 5.1.3.1.3 Airways
- 5.1.3.1.4 Others
- 5.1.3.2 Energy & Utilities
- 5.1.3.3 Others
- 5.1.3.1 Transportation Infrastructure
- 5.1.1 Residential
- 5.2 By Construction Type
- 5.2.1 New Construction
- 5.2.2 Renovation
- 5.3 By Construction Method
- 5.3.1 Conventional On-Site
- 5.3.2 Modern Methods of Construction
- 5.4 By Investment Source
- 5.4.1 Public
- 5.4.2 Private
- 5.5 By Geography
- 5.5.1 Selangor
- 5.5.2 Johor
- 5.5.3 Wilayah Persekutuan
- 5.5.4 Rest of Malaysia
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Gamuda Berhad
- 6.4.2 IJM Corporation Berhad
- 6.4.3 YTL Corporation Berhad
- 6.4.4 Malaysian Resources Corporation Berhad (MRCB)
- 6.4.5 UEM Sunrise Berhad
- 6.4.6 WCT Holdings Berhad
- 6.4.7 Sunway Construction Group Berhad
- 6.4.8 Sime Darby Property Berhad
- 6.4.9 Mah Sing Group Berhad
- 6.4.10 S P Setia Berhad
- 6.4.11 Crest Builder Holdings Berhad
- 6.4.12 Kerjaya Prospek Group Berhad
- 6.4.13 TRC Synergy Berhad
- 6.4.14 Hock Seng Lee Berhad
- 6.4.15 Kimlun Corporation Berhad
- 6.4.16 Gadang Holdings Berhad
- 6.4.17 Econpile Holdings Berhad
- 6.4.18 LFE Corporation Berhad
- 6.4.19 Pentamaster Corporation Berhad (for industrial facilities)
- 6.4.20 China Communications Construction Co. Ltd. (Malaysia unit)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

