PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187723

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187723
Singapore Construction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
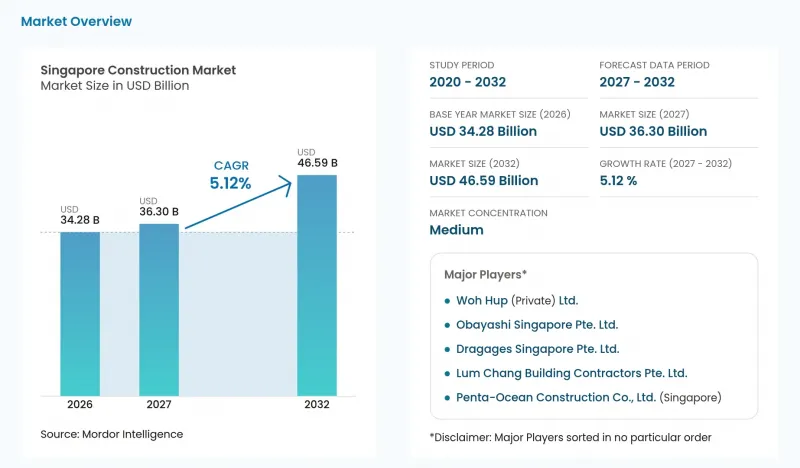
According to Mordor Intelligence, the Singapore construction market size was valued at USD 34.28 billion in 2026 and estimated to grow from USD 36.3 billion in 2027 to reach USD 46.59 billion by 2032, at a CAGR of 5.12% during the forecast period (2027-2032).
Singapore Construction Market Trends and Insights
Public-sector "Green Mark" procurement encouraging embodied-carbon assessment
The Building and Construction Authority (BCA) sets carbon requirements that can make certified performance part of construction specifications. Buildings on qualifying Government Land Sales land sold from December 2, 2022, in specified Jurong Lake District and Marina South areas must attain the Whole Life Carbon Badge. This accompanies Green Mark Platinum Super Low Energy and other badge requirements. For new buildings and existing buildings undergoing additions and alterations with new substructures, Green Mark Version 7 separately rewards calculations using the Building Embodied Carbon Calculator and reductions against concrete, steel and glass embodied-carbon baselines. This makes material selection and supporting carbon calculations part of the same commercial proposition. Contractors able to connect proposed material choices to the assessment can compete on documented carbon performance.
Tuas Port & Changi T5 megaprojects anchoring civil-infrastructure pipeline
Major transport projects support construction demand through work packages at different stages of delivery. In January 2026, BCA expected additional Changi Terminal 5 construction packages to support Singapore's construction demand that year. Separately, the Maritime and Port Authority of Singapore's notice effective September 23, 2026, to March 22, 2027, covered soil investigation, dredging, reclamation and caisson installation at Tuas Terminal Phase 2. The notice specified jack-up and crane barges for soil investigation and dredgers for seabed works. These marine activities create demand for specialist equipment and seabed expertise, extending the megaproject opportunity beyond construction of terminal buildings.
Tight foreign-worker quotas inflating labor costs
Construction staffing is constrained by both workforce ratios and skill composition. Singapore's Ministry of Manpower (MOM) permits 5 construction Work Permit holders per local employee earning the Local Qualifying Salary. Employers must also maintain at least 10% Higher-Skilled permit holders before hiring new Basic-Skilled workers or renewing existing Basic-Skilled permits. From January 2028, new recruits brought in without the Skills Evaluation Certificate (Knowledge) are scheduled to receive a 6-month period at the prevailing Basic-Skilled levy. Employers would face a higher levy afterward if those workers fail the local test within that period. Rapid crew expansion therefore depends on qualifying local headcount and the required skill mix, with additional cost exposure when uncertified recruits miss the testing deadline.
Other drivers and restraints analyzed in the detailed report include:
- Housing & Development Board's accelerated BTO program
- Hyperscale-data-center moratorium lift triggering new capacity awards
- Scarce land driving vertical-construction complexity & risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Residential accounted for a 46.51% share of the Singapore construction market size in 2026, making it the largest segment. By March 31, 2026, HDB had built a cumulative 1,293,335 residential units across 24 towns and 3 estates. On January 8, 2026, HDB reported 127 housing projects under construction across Singapore, up from 110 in 2025. That active workload added near-term delivery requirements to an extensive established public-housing base. Serving numerous HDB projects gives residential builders a route to scale through repeated delivery for a common public client.
Infrastructure is the fastest-growing segment in the Singapore construction market, with a forecast CAGR of 5.55% during 2027-2032. On September 30, 2026, the Land Transport Authority (LTA) awarded 3 Tuas Road Viaduct Phase 2 civil contracts linking Tuas South and Tuas Port, with construction expected to start in early 2027. The scope combines viaducts, road improvements, drainage and supporting infrastructure, creating several connected civil-work requirements. With construction expected from early 2027 and progressive completion from 2032, the awards create a civil-work pipeline extending across the 2027-2032 forecast period.
New construction represented a 62.21% Singapore construction market share in 2026 and was the largest segment. On December 1, 2025, Alexandra Hospital appointed a joint venture of Shimizu Corporation, Ssangyong Engineering & Construction Co. Ltd. and Kimly Construction Pte. Ltd. as a main contractor. A separate award went to Rich Construction Company Pte. Ltd., with the main contractors assigned different campus zones. The 13.3-hectare redevelopment comprises 2 towers for inpatient and outpatient facilities linked by a planned community boulevard bridge. A campus split between 2 main-contractor groups across different zones gives the client 2 delivery teams to align on a single hospital program.
Renovation / retrofit is the fastest-growing segment in the Singapore construction market, with a forecast CAGR of 5.55% during 2027-2032. In HDB's Home Improvement Programme, construction works for about 409,000 flats were completed and works for 83,000 were at various stages of progress as of March 31, 2026. The program addresses spalling concrete, waste discharge stacks and existing toilets, linking demand to specific maintenance needs inside homes. Separately, 105 Neighbourhood Renewal Programme projects were in progress on the same date, with town councils implementing precinct- and block-level improvements. The commercial opening combines repairs inside flats with improvements to shared estate spaces, giving renewal contractors distinct dwelling-level and neighborhood-level work streams within the existing housing system.
Complete Report Scope:
- By Sector
- Residential
- Apartments / Condominiums
- Villas and Landed Houses
- Commercial
- Office
- Retail
- Industrial and Logistics
- Others
- Infrastructure
- Transportation Infrastructure (Roadways, Railways, Airways, others)
- Energy & Utilities
- Others
- Residential
- By Construction Type
- New Construction
- Renovation / Retrofit
- By Construction Method
- Conventional On-Site
- Modern Methods of Construction
- By Investment Source
- Public
- Private
- Public-Private Partnership (PPP)
- By Geography
- Core Central Region (CCR)
- Rest of Central Region (RCR)
- Outside Central Region (OCR)
List of Companies Covered in this Report:
- Woh Hup (Private) Ltd.
- Obayashi Singapore Pte. Ltd.
- Dragages Singapore Pte. Ltd.
- Penta-Ocean Construction Co., Ltd. (Singapore)
- Lum Chang Building Contractors Pte. Ltd.
- Tiong Seng Contractors (Pte.) Ltd.
- Gammon Pte. Ltd.
- Samsung C&T Corp. (Singapore)
- Lendlease Singapore Pte. Ltd.
- Kajima Overseas Asia (Singapore) Pte. Ltd.
- China Construction (South Pacific) Dev. Co. Pte. Ltd.
- Ssangyong Engineering & Construction Co., Ltd. (Singapore)
- Hock Lian Seng Infrastructure Pte. Ltd.
- Koon Construction & Transport Co. Pte. Ltd.
- Straits Construction Singapore Pte. Ltd.
- Takenaka Corp. (Singapore Office)
- Civil Tech Pte. Ltd.
- BHCC Construction Pte. Ltd.
- United Engineers Ltd.
- Chip Eng Seng Contractors (1988) Pte. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Public-sector "Green Mark" procurement encouraging embodied-carbon assessment
- 4.2.2 Tuas Port & Changi T5 megaprojects anchoring civil-infrastructure pipeline
- 4.2.3 Housing & Development Board's accelerated BTO program
- 4.2.4 Hyperscale-data-center moratorium lift triggering new capacity awards
- 4.2.5 Mandatory Integrated Digital Delivery (IDD) on Government Land Sales sites raising BIM-prefab adoption
- 4.2.6 Neighbourhood Renewal Programme boosting brownfield retrofits
- 4.3 Market Restraints
- 4.3.1 Tight foreign-worker quotas inflating labor costs
- 4.3.2 Scarce land driving vertical-construction complexity & risk
- 4.3.3 Volatile imported-material prices (re-export hub exposure)
- 4.3.4 Rising workplace-safety compliance penalties
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Government Initiatives & Vision
- 4.9 Pricing (Construction Materials) & Construction Cost Analysis
- 4.10 Comparison of Key Industry Metrics of Singapore with Other Countries
- 4.11 Key Upcoming/Ongoing Projects (focus on mega projects)
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Sector
- 5.1.1 Residential
- 5.1.1.1 Apartments / Condominiums
- 5.1.1.2 Villas and Landed Houses
- 5.1.2 Commercial
- 5.1.2.1 Office
- 5.1.2.2 Retail
- 5.1.2.3 Industrial and Logistics
- 5.1.2.4 Others
- 5.1.3 Infrastructure
- 5.1.3.1 Transportation Infrastructure (Roadways, Railways, Airways, others)
- 5.1.3.2 Energy & Utilities
- 5.1.3.3 Others
- 5.1.1 Residential
- 5.2 By Construction Type
- 5.2.1 New Construction
- 5.2.2 Renovation / Retrofit
- 5.3 By Construction Method
- 5.3.1 Conventional On-Site
- 5.3.2 Modern Methods of Construction
- 5.4 By Investment Source
- 5.4.1 Public
- 5.4.2 Private
- 5.4.3 Public-Private Partnership (PPP)
- 5.5 By Geography
- 5.5.1 Core Central Region (CCR)
- 5.5.2 Rest of Central Region (RCR)
- 5.5.3 Outside Central Region (OCR)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Woh Hup (Private) Ltd.
- 6.4.2 Obayashi Singapore Pte. Ltd.
- 6.4.3 Dragages Singapore Pte. Ltd.
- 6.4.4 Penta-Ocean Construction Co., Ltd. (Singapore)
- 6.4.5 Lum Chang Building Contractors Pte. Ltd.
- 6.4.6 Tiong Seng Contractors (Pte.) Ltd.
- 6.4.7 Gammon Pte. Ltd.
- 6.4.8 Samsung C&T Corp. (Singapore)
- 6.4.9 Lendlease Singapore Pte. Ltd.
- 6.4.10 Kajima Overseas Asia (Singapore) Pte. Ltd.
- 6.4.11 China Construction (South Pacific) Dev. Co. Pte. Ltd.
- 6.4.12 Ssangyong Engineering & Construction Co., Ltd. (Singapore)
- 6.4.13 Hock Lian Seng Infrastructure Pte. Ltd.
- 6.4.14 Koon Construction & Transport Co. Pte. Ltd.
- 6.4.15 Straits Construction Singapore Pte. Ltd.
- 6.4.16 Takenaka Corp. (Singapore Office)
- 6.4.17 Civil Tech Pte. Ltd.
- 6.4.18 BHCC Construction Pte. Ltd.
- 6.4.19 United Engineers Ltd.
- 6.4.20 Chip Eng Seng Contractors (1988) Pte. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

