PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187327

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187327
Africa Construction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the Africa construction market size is expected to grow from USD 257.6 billion in 2026 to USD 275.9 billion in 2027 and is forecast to reach USD 384.3 billion by 2032 at 6.85% CAGR over 2027-2032.
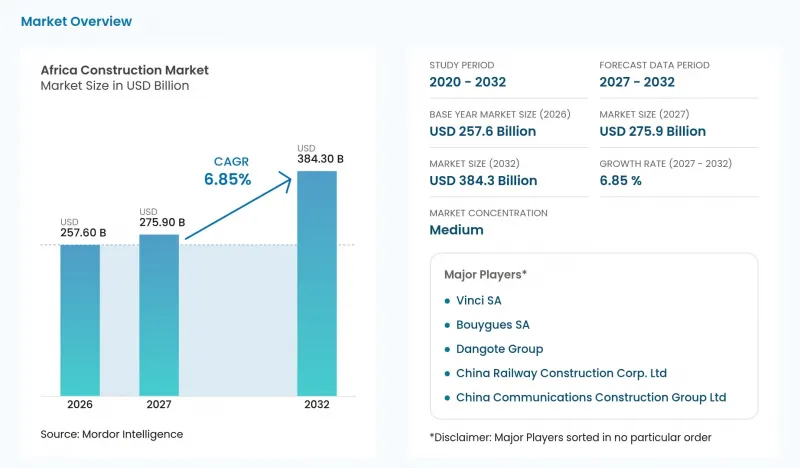
This report is segmented by Sector (Residential, Infrastructure, and more), Construction Type (New Construction and Renovation), Construction Method (Conventional On-Site and Modern Methods of Construction), Investment Source (Public and Private), and Geography (Egypt, Rest of Africa, and more). The market forecasts are provided in terms of value (USD), based on availability.
Africa Construction Market Trends and Insights
Rapid urbanization & housing backlog
Urbanization brings new housing needs into places that also have substantial unmet requirements. In 2025, UN-Habitat reported annual supply of 131,000 new houses in Ethiopia against annual demand of 400,000 houses, with an additional existing backlog. It said continuing urban population growth would add pressure to that housing shortage. UN DESA projected that 7 countries globally, including Nigeria, Egypt and Ethiopia, would collectively add more than 500 million city residents during 2025-2050. That supply covers less than a third of annual demand before the older backlog is counted, so housing output has to rise well above reported delivery before the shortage narrows.
Economic diversification & GDP rebound
The World Bank forecast sub-Saharan African GDP growth of 4.3% in 2026, following an estimated 4.1% in 2025. It linked that outlook to stronger domestic demand and investments associated with the energy transition and digital technologies. Nxtra by Airtel Africa, Airtel Africa's data center arm, began construction at Tatu City near Nairobi, Kenya, on September 9, 2025. The planned 44 MW facility later received a revised completion target of July 2027. The revised target places prospective building revenue before the facility's operating income, so digital-capacity investment creates construction demand ahead of service delivery.
Political-regulatory volatility & contract risk
Contract-payment risk can prevent public construction commitments from becoming completed facilities. In its 2025 Provincial Week report, South Africa's Parliament recorded an unpaid contractor causing major delays to the Baketon Library extension in Springs, with delays dating to 2022. This case connects payment failure directly to construction delivery. For a contractor, an award without dependable payment can require financing work before the corresponding receipts arrive. That exposure can limit the resources available to advance the contracted works, even when the physical scope is defined. A delay that dated to 2022 in the 2025 report shows that unpaid work can leave a contractor carrying its own financing for years.
Other drivers and restraints analyzed in the detailed report include:
- Government-backed infrastructure programs & PPP pipelines
- Expansion of pan-African logistics corridors
- Skilled-labor deficits & productivity gaps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Residential construction accounted for a 37.71% share of the Africa construction market size in 2026, making it the largest segment. Nigeria's housing ministry reported more than 10,000 units commenced across 14 states and the Federal Capital Territory during the Renewed Hope Housing Programme's first 2 years through August 2025. Those starts illustrate a public-program route into residential work extending beyond a single city or flagship development. The ministry counted units commenced rather than delivered, so the program's weight in the sector depends on how many of those starts become completed homes.
Infrastructure is the fastest-growing segment, forecast to expand at 8.7% CAGR during 2027-2032. South Africa's Public Works and Infrastructure Minister Dean Macpherson reported 82 infrastructure projects under construction in August 2026. That active project base places demand beyond the announcement stage. Contractors addressing it need capacity for successive delivery stages, so the near-term opportunity lies in executing ongoing works.
New construction represented a 70.48% Africa construction market share in 2026, making it the largest segment. In South Africa, private-sector residential plans passed by larger municipalities had the highest current-price value among residential, non-residential, and additions-and-alterations categories in January-July 2026. Within that national private-building pipeline, the concentration of approval value in homes provides an application focus for new-build specialists. Plans passed precede construction starts, so this ranking shows where new-build work is likely to originate rather than work already under way.
Renovation is the fastest-growing segment, with an 8.9% CAGR forecast during 2027-2032. On March 12, 2026, Ekiti State's Ministry of Health and Human Services awarded Step Development Limited additional renovation works covering 9 general hospitals, the Government House Clinic and other health-sector buildings. The award creates a route into construction demand through an established public facility estate. For health-sector contractors, a single buyer can combine improvement requirements across several existing buildings into a defined package of work. Follow-on awards can renew demand within the same facility estate, extending the construction relationship beyond the initial improvement package.
Complete Report Scope:
- By Sector
- Residential
- Apartments/Condominiums
- Villas/Landed Houses
- Commercial
- Office
- Retail
- Industrial and Logistics
- Others
- Infrastructure
- Transportation Infrastructure (Roadways, Railways, Airways, others)
- Energy & Utilities
- Others
- Residential
- By Construction Type
- New Construction
- Renovation
- By Construction Method
- Conventional On-Site
- Modern Methods of Construction (Prefabricated, Modular, etc)
- By Investment Source
- Public
- Private
- By Geography
- Nigeria
- South Africa
- Egypt
- Kenya
- Ethiopia
- Rest of Africa
List of Companies Covered in this Report:
- China Communications Construction Group Ltd
- China Railway Construction Corp. Ltd
- Vinci SA
- Dangote Group
- Bouygues SA
- Aveng Ltd
- WBHO (Wilson Bayly Holmes-Ovcon)
- Orascom Construction
- BAM International
- Shapoorji Pallonji Group
- Julius Berger Nigeria PLC
- Sonatrach (Infrastructure arm)
- Consolidated Contractors Company (CCC)
- China National Machinery Industry Corp. (Sinomach)
- Power Construction Corp. of China (PowerChina)
- Shapoorji Pallonji Africa
- Group Five Construction
- Arab Contractors
- Dumez Nigeria PLC
- General Nile Company for Roads & Bridges
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid urbanization & housing backlog
- 4.2.2 Economic diversification & GDP rebound
- 4.2.3 Government-backed infrastructure programs & PPP pipelines
- 4.2.4 Expansion of pan-African logistics corridors
- 4.2.5 Green-building finance inflows (e.g., climate bonds)
- 4.2.6 AfCFTA-linked industrial park developments
- 4.3 Market Restraints
- 4.3.1 Political-regulatory volatility & contract risk
- 4.3.2 Skilled-labor deficits & productivity gaps
- 4.3.3 Hard-currency shortage & capital-controls risk
- 4.3.4 Climatic shocks driving insurance & rebuild costs
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Government Initiatives & Vision
- 4.9 Pricing (Construction Materials) and Construction Cost (Materials, Labour, Equipment) Analysis
- 4.10 Comparison of Key Industry Metrics of Africa with Other Countries
- 4.11 Key Upcoming/Ongoing Projects (with a focus on Mega Projects)
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Sector
- 5.1.1 Residential
- 5.1.1.1 Apartments/Condominiums
- 5.1.1.2 Villas/Landed Houses
- 5.1.2 Commercial
- 5.1.2.1 Office
- 5.1.2.2 Retail
- 5.1.2.3 Industrial and Logistics
- 5.1.2.4 Others
- 5.1.3 Infrastructure
- 5.1.3.1 Transportation Infrastructure (Roadways, Railways, Airways, others)
- 5.1.3.2 Energy & Utilities
- 5.1.3.3 Others
- 5.1.1 Residential
- 5.2 By Construction Type
- 5.2.1 New Construction
- 5.2.2 Renovation
- 5.3 By Construction Method
- 5.3.1 Conventional On-Site
- 5.3.2 Modern Methods of Construction (Prefabricated, Modular, etc)
- 5.4 By Investment Source
- 5.4.1 Public
- 5.4.2 Private
- 5.5 By Geography
- 5.5.1 Nigeria
- 5.5.2 South Africa
- 5.5.3 Egypt
- 5.5.4 Kenya
- 5.5.5 Ethiopia
- 5.5.6 Rest of Africa
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 China Communications Construction Group Ltd
- 6.4.2 China Railway Construction Corp. Ltd
- 6.4.3 Vinci SA
- 6.4.4 Dangote Group
- 6.4.5 Bouygues SA
- 6.4.6 Aveng Ltd
- 6.4.7 WBHO (Wilson Bayly Holmes-Ovcon)
- 6.4.8 Orascom Construction
- 6.4.9 BAM International
- 6.4.10 Shapoorji Pallonji Group
- 6.4.11 Julius Berger Nigeria PLC
- 6.4.12 Sonatrach (Infrastructure arm)
- 6.4.13 Consolidated Contractors Company (CCC)
- 6.4.14 China National Machinery Industry Corp. (Sinomach)
- 6.4.15 Power Construction Corp. of China (PowerChina)
- 6.4.16 Shapoorji Pallonji Africa
- 6.4.17 Group Five Construction
- 6.4.18 Arab Contractors
- 6.4.19 Dumez Nigeria PLC
- 6.4.20 General Nile Company for Roads & Bridges
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

