PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119663

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119663
Vietnam Data Center Construction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Vietnam data center construction market size was valued at USD 0.79 billion in 2025 and estimated to grow from USD 0.86 billion in 2026 to reach USD 1.33 billion by 2031, at a CAGR of 9.03% during the forecast period (2026-2031).
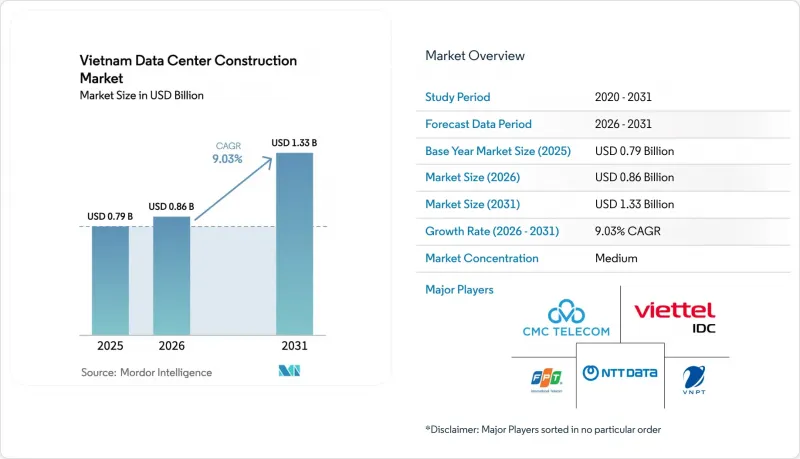
This report Segments the Industry Into Infrastructure (By Electrical Infrastructure, by Mechanical Infrastructure, General Construction), by Tier Type (Tier 1 and 2, Tier 3, Tier 4), by Data Center Type (Colocation, Self-Built Hyperscalers (CSPs) and More). The Market Sizes and Forecasts are Provided in Terms of Value (USD Million) for all the Above Segments.
Vietnam Data Center Construction Market Trends and Insights
Data-Localization Mandate Drives Demand
Vietnam's Decree 53 and the comprehensive Data Law effective July 2025 oblige global platforms to store designated "important" and "core" data onshore. Compliance timelines accelerate facility sourcing, evidenced by Alibaba shifting from state-rented racks to dedicated builds. The government-funded National Data Center, due late-2025, sets common security and redundancy baselines that raise enterprise expectations. Google's plan for its first domestic hyperscale site underlines how sovereignty statutes now dictate footprint strategies. Together these policies create a predictable, captive pipeline for local construction contractors.
Cloud and OTT Traffic Surge Amplifies Infrastructure Needs
Commercial 5G went live nationwide in October 2024 and averaged 247.78 Mbps download by March 2025, enabling UHD streaming and cloud gaming that swell back-end compute demand. Government targets guarantee 200 Mbps fixed speeds for 90% of households by 2025, while enterprises gain symmetric 1 Gbps pipes. Viettel's ongoing 140 MW campus with 60 kW racks epitomizes how service-provider traffic forecasts translate directly into high-density design. Each incremental rise in last-mile capacity multiplies local processing workloads, sustaining utilization rates well above regional averages.
High Import Dependency Raises Costs
Vietnam's semiconductor base still emphasizes design, forcing imports of precision switchgear, chillers, and GPUs, exposing builders to freight surcharges and currency swings. Construction-cost benchmarks issued under Decision 409/QD-BXD cannot offset equipment price escalation when global supply tightens. Schneider Electric's pivot to expand manufacturing in the United States underscores how suppliers are regionalizing, leaving Southeast Asian buyers vulnerable to lead-time gaps
Other drivers and restraints analyzed in the detailed report include:
- Renewable-Energy Access Transforms Economics
- Nationwide 5G Rollout Creates Edge-Compute Demand
- MEP-Skills Shortage Delays Projects
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tier 3 sites retained 60.75% market share in 2025 as most enterprises still balance redundancy and capex prudence. The Vietnam data center construction market size for Tier 3 therefore remained largest, while Tier 4 operations set the fastest 11.7% CAGR trajectory into 2031. Investors interpret frequent power-quality incidents as justification for moving workloads to fully concurrent systems, even when capital costs rise. Viettel's 140 MW Tan Phu Trung campus targets Tier III certification yet benches Tier IV-ready modules for AI clusters, signalling a transitional design mindset.
Higher-tier momentum also mirrors hyperscaler tolerance thresholds; GPU training clusters cannot risk downtime without jeopardizing multi-day job runs. NVIDIA's memorandum with the Vietnamese government to open an AI R&D center imposes Tier 4 baselines on supply-chain partners. As the Vietnam data center construction market broadens, Tier 4 build-to-suit contracts drive premium service revenues, while Tier 1/2 footprints contract toward dev-test and local-edge use cases.
Colocation retained 56.70% share in 2025, anchoring the Vietnam data center construction market. Nonetheless, self-build hyperscale programs clock a 12.9% CAGR as Google, Alibaba, and regional OTT players prioritize full-stack control. Deregulation in 2024 allowing 100% foreign ownership eliminates equity constraints that once steered entrants toward colocation leases.
Joint-venture blueprints remain relevant; STT GDC's alliance with VNG combines local permits and land banks with international best-practice construction. Yet most hyperscalers favor outright greenfield builds to integrate proprietary network fabrics, specialized security, and custom-AI chip clusters. The trend forces colocation incumbents to chase differentiation via edge-site density, sovereign-cloud tiers, or sector-specific compliance wrappers.
Complete Report Scope:
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Type
- Colocation
- Self-build Hyperscalers (CSPs)
- Enterprise and Edge
- By Infrastructure
- By Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
- By Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Service - Design and Consulting, Integration, Support and Maintenance
- By Electrical Infrastructure
List of Companies Covered in this Report:
- Viettel IDC
- VNPT
- FPT Telecom
- CMC Telecom
- NTT GDC Vietnam
- ST Telemedia GDC Vietnam
- Keppel DC Vietnam
- GDS Holdings
- Digital Realty-Mapletree JV
- KDDI Telehouse Vietnam
- Gaw NP Industrial
- CotekCNS
- AECOM
- Obayashi Corp
- Turner Construction
- Rider Levett Bucknall
- Artelia Group
- Firstgreen Engineering
- Arup Vietnam
- Schneider Electric Vietnam
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Data-localization mandate (Decree 53)
- 4.2.2 Cloud and OTT traffic boom
- 4.2.3 Low power tariffs and renewable PPAs
- 4.2.4 Nationwide 5G + fibre backhaul rollout
- 4.2.5 Sub-sea cable expansion (ADC2, SJC2)
- 4.2.6 Green-finance access for "net-zero" DCs
- 4.3 Market Restraints
- 4.3.1 High imported CAPEX / OPEX
- 4.3.2 Skilled MEP commissioning talent gap
- 4.3.3 Grid-instability in hydropower-lean seasons
- 4.3.4 Speculative AI-DC overbuild bubble risk
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 KEY DATA CENTER STATISTICS
- 5.1 Exhaustive Data Center Operators in Vietnam (in MW)
- 5.2 List of Major Upcoming Data Center Projects in Vietnam (2025-2030)
- 5.3 CAPEX and OPEX For Vietnam Data Center Construction
- 5.4 Data Center Power Capacity Absorption In MW, Selected Cities, Vietnam, 2023 and 2024
6 ARTIFICIAL INTELLIGENCE (AI) INCLUSION IN DATA CENTER CONSTRUCTION IN Vietnam
7 REGULATORY and COMPLIANCE FRAMEWORK
8 MARKET SIZE and GROWTH FORECASTS (VALUE)
- 8.1 By Tier Type
- 8.1.1 Tier 1 and 2
- 8.1.2 Tier 3
- 8.1.3 Tier 4
- 8.2 By Data Center Type
- 8.2.1 Colocation
- 8.2.2 Self-build Hyperscalers (CSPs)
- 8.2.3 Enterprise and Edge
- 8.3 By Infrastructure
- 8.3.1 By Electrical Infrastructure
- 8.3.1.1 Power Distribution Solution
- 8.3.1.2 Power Backup Solutions
- 8.3.2 By Mechanical Infrastructure
- 8.3.2.1 Cooling Systems
- 8.3.2.2 Racks and Cabinets
- 8.3.2.3 Servers and Storage
- 8.3.2.4 Other Mechanical Infrastructure
- 8.3.3 General Construction
- 8.3.4 Service - Design and Consulting, Integration, Support and Maintenance
- 8.3.1 By Electrical Infrastructure
9 COMPETITIVE LANDSCAPE
- 9.1 Market Concentration
- 9.2 Strategic Moves
- 9.3 Market Share Analysis
- 9.4 Data Center Infrastructure Investment Based on Megawatt (MW) Capacity, 2024 vs 2030
- 9.5 Data Center Construction Landscape (Key Vendors Listings)
- 9.6 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, Recent Developments)
- 9.6.1 Viettel IDC
- 9.6.2 VNPT
- 9.6.3 FPT Telecom
- 9.6.4 CMC Telecom
- 9.6.5 NTT GDC Vietnam
- 9.6.6 ST Telemedia GDC Vietnam
- 9.6.7 Keppel DC Vietnam
- 9.6.8 GDS Holdings
- 9.6.9 Digital Realty-Mapletree JV
- 9.6.10 KDDI Telehouse Vietnam
- 9.6.11 Gaw NP Industrial
- 9.6.12 CotekCNS
- 9.6.13 AECOM
- 9.6.14 Obayashi Corp
- 9.6.15 Turner Construction
- 9.6.16 Rider Levett Bucknall
- 9.6.17 Artelia Group
- 9.6.18 Firstgreen Engineering
- 9.6.19 Arup Vietnam
- 9.6.20 Schneider Electric Vietnam
10 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 10.1 White-space and Unmet-Need Assessment

