PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121978

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121978
China Diabetes Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the China diabetes devices market size was valued at USD 3.91 billion in 2025 and is estimated to grow from USD 4.18 billion in 2026 to reach USD 6.05 billion by 2031, at a CAGR of 7.67% during the forecast period (2026-2031).
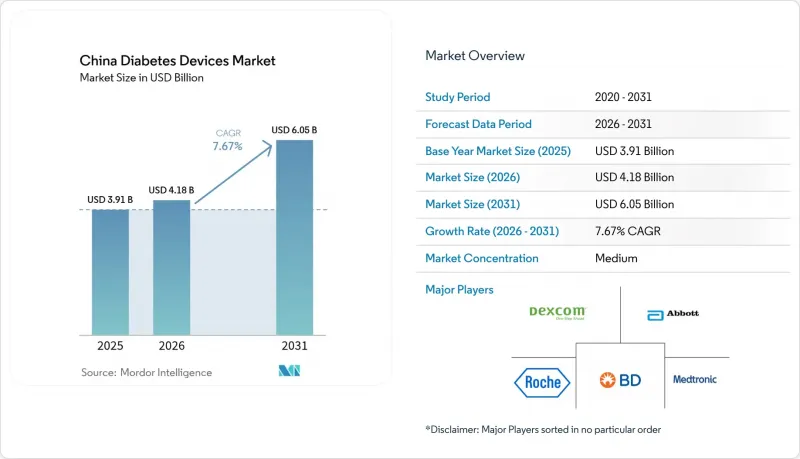
This report is Segmented Into Device Category (Glucose Monitoring Devices, Insulin Delivery Devices, Other Diabetes-Care Devices), Diabetes Type (Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, and Others), and End User (Hospital, Specialty Clinics, Home-Care Settings, Other End Users). The Market Provides the Value (in USD) and (in Units) for the Above-Mentioned Segments.
China Diabetes Devices Market Trends and Insights
Rising Diabetes Prevalence and Earlier Disease Onset
China reported 141 million diagnosed cases in 2025, plus 73.5 million undiagnosed adults, for a total of 49.7% latent prevalence. Age-standardized rates exceed 20% in Beijing, Tianjin, and Shanghai, where diets and sedentary work contribute to earlier onset. Healthy China 2030 now requires fasting glucose checks for every adult above 35, adding 8-10 million newly identified patients each year. Longer disease duration increases the risk of complications, prompting clinicians to monitor continuously to delay microvascular injury. Guangdong and Zhejiang set aside RMB 2.3 billion (USD 316 million) in 2025 for community diabetes programs that bundle subsidized glucometers with education.
Government Reimbursement Expansion for CGM and Insulin Pens
Beijing, Shanghai, Tianjin, Guangdong, Henan, and Yunnan moved CGM sensors and smart pens onto basic medical insurance lists between 2024 and 2025, lowering patient out-of-pocket spending by 40-60%. Eighteen provinces now publish reimbursement device catalogs, signaling nationwide diffusion. The cross-provincial settlement network links 550,400 hospitals and provides real-time claim approval, an advance that eases adoption for migrant workers who often return to hometown clinics for follow-up. Commercial health policies sold in 300 cities add another payor layer that covers sensors at 70-80% co-insurance. Asymmetry remains: Beijing shoulders 80% of CGM costs for Type 1 but only 30% for Type 2, preserving premium price pools for pediatric and pump-dependent users.
High Upfront Cost of Advanced Devices
Fourteen-day CGM packs coupled with transmitters generate annual spending of RMB 24,000-36,000 (USD 3,300-4,950), equal to 86-129% of average disposable income in Tier 3 counties. Pumps priced between RMB 18,000 and RMB 45,000 remain beyond the reach of most Type 2 patients. Reimbursement seldom covers consumables, leaving households to absorb RMB 8,000-15,000 (USD 1,100-2,065) each year. Awareness is low; a 2024 Chinese Diabetes Society survey found that 62% of Type 2 respondents were unaware of CGM availability and 74% believed pumps were hospital-only devices. Volume-based procurement will cut strip prices by up to 80% and could slow CGM conversion. Subscription pilots, such as Yuwell's RMB 99-per-month model, show early promise but remain concentrated in urban Zhejiang.
Other drivers and restraints analyzed in the detailed report include:
- Domestic Manufacturing Cost Advantage Lowering Prices
- E-Commerce Reach into Lower-Tier Cities
- Fragmented and Evolving NMPA Regulatory Pathways
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Glucose monitoring accounted for 59.83% of the China diabetes devices market in 2025, supported by widespread use of SMBG meters among Type 2 patients who test 2-4 times daily. The Chinese diabetes devices market share for monitoring skews toward Sinocare, which produces strips at costs 35-50% under multinational equivalents and holds 30-40% of volumes. Continuous monitoring is climbing quickly after six provinces reimbursed sensors that cut patient costs nearly in half. Sibionics and Yuwell secured 12% combined share within one year by pricing sensors 30-40% below Abbott, whose November 2025 recall opened shelf space for domestic models.
Insulin delivery will grow at an 8.78% CAGR, and its segment will drive the China diabetes devices market as the adoption of Bluetooth pens and patch pumps widens. Pens generated 68% of delivery revenue in 2025 after Jiangsu Delfu demonstrated 21% insulin savings across 150,000 connected units. MicroTech's Equil and Medtrum's A7+ pumps expand the options for patients seeking automated basal adjustment at a lower entry price. Closed-loop systems that use CGM data to fine-tune basal rates are poised to dominate high-acuity Type 1 care once Abbott-Medtronic interoperability is implemented in clinics in 2026.
Complete Report Scope:
- By Device Category
- Glucose Monitoring Devices
- Self-Monitoring Blood Glucose (SMBG) Devices
- Glucometers
- Test Strips
- Lancets
- Continuous Glucose Monitoring (CGM) Devices
- Sensors
- Durables (Receivers & Transmitters)
- Self-Monitoring Blood Glucose (SMBG) Devices
- Insulin Delivery Devices
- Insulin Pens
- Insulin Pumps
- Insulin Syringes
- Jet Injectors
- Other Diabetes-Care Devices
- Glucose Monitoring Devices
- By Diabetes Type
- Type 1 Diabetes
- Type 2 Diabetes
- Gestational & Others
- By End User
- Hospital
- Specialty Clinics
- Home Care Settings
- Other End Users
List of Companies Covered in this Report:
- Abbott Laboratories
- Ascensia
- B. Braun
- Beckton Dickinson
- Dexcom
- Eli Lilly and Company
- Gan & Lee Pharm
- Insulet
- Lepu Medical
- Lifescan
- Medtronic
- MicroPort
- MicroTech Medical Co.
- Novo Nordisk
- Roche
- Sanofi
- Senseonics Holdings
- Sinocare
- SOOIL Development
- Tandem Diabetes Care
- Ypsomed
- Yuwell Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Diabetes Prevalence & Earlier Disease Onset
- 4.2.2 Government Reimbursement Expansion for CGM & Insulin Pens
- 4.2.3 Domestic Manufacturing Cost Advantage Lowering ASPs
- 4.2.4 E-Commerce Reach into Lower-Tier Cities
- 4.2.5 Hospital Digital-Health Upgrades Accelerating Connected-Device Uptake
- 4.2.6 Provincial Volume-Based Procurement Lowering SMBG Kit Costs
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost of Advanced Devices
- 4.3.2 Fragmented & Evolving NMPA Regulatory Pathways
- 4.3.3 Data-Privacy & Cybersecurity Concerns for Cloud-Linked Devices
- 4.3.4 Sensor-Grade Rare-Earth Supply Risks Inflating BOM Costs
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value & Volume)
- 5.1 By Device Category
- 5.1.1 Glucose Monitoring Devices
- 5.1.1.1 Self-Monitoring Blood Glucose (SMBG) Devices
- 5.1.1.1.1 Glucometers
- 5.1.1.1.2 Test Strips
- 5.1.1.1.3 Lancets
- 5.1.1.2 Continuous Glucose Monitoring (CGM) Devices
- 5.1.1.2.1 Sensors
- 5.1.1.2.2 Durables (Receivers & Transmitters)
- 5.1.1.1 Self-Monitoring Blood Glucose (SMBG) Devices
- 5.1.2 Insulin Delivery Devices
- 5.1.2.1 Insulin Pens
- 5.1.2.2 Insulin Pumps
- 5.1.2.3 Insulin Syringes
- 5.1.2.4 Jet Injectors
- 5.1.3 Other Diabetes-Care Devices
- 5.1.1 Glucose Monitoring Devices
- 5.2 By Diabetes Type
- 5.2.1 Type 1 Diabetes
- 5.2.2 Type 2 Diabetes
- 5.2.3 Gestational & Others
- 5.3 By End User
- 5.3.1 Hospital
- 5.3.2 Specialty Clinics
- 5.3.3 Home Care Settings
- 5.3.4 Other End Users
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 Abbott Diabetes Care
- 6.3.2 Ascensia Diabetes Care
- 6.3.3 B. Braun Melsungen AG
- 6.3.4 Becton Dickinson and Company
- 6.3.5 Dexcom Inc.
- 6.3.6 Eli Lilly and Company
- 6.3.7 Gan & Lee Pharm
- 6.3.8 Insulet Corporation
- 6.3.9 Lepu Medical Technology
- 6.3.10 LifeScan
- 6.3.11 Medtronic
- 6.3.12 MicroPort Scientific
- 6.3.13 MicroTech Medical Co.
- 6.3.14 Novo Nordisk A/S
- 6.3.15 Roche Diabetes Care
- 6.3.16 Sanofi S.A.
- 6.3.17 Senseonics Holdings
- 6.3.18 Sinocare Inc.
- 6.3.19 SOOIL Development
- 6.3.20 Tandem Diabetes Care
- 6.3.21 Ypsomed AG
- 6.3.22 Yuwell Medical
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

