PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154864

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154864
South America Diabetes Care Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the South America diabetes care devices market is expected to grow from USD 2.43 billion in 2025 and is estimated to grow from USD 2.57 billion in 2026 to reach USD 3.34 billion by 2031, at a CAGR of 5.56% during the forecast period (2026-2031).
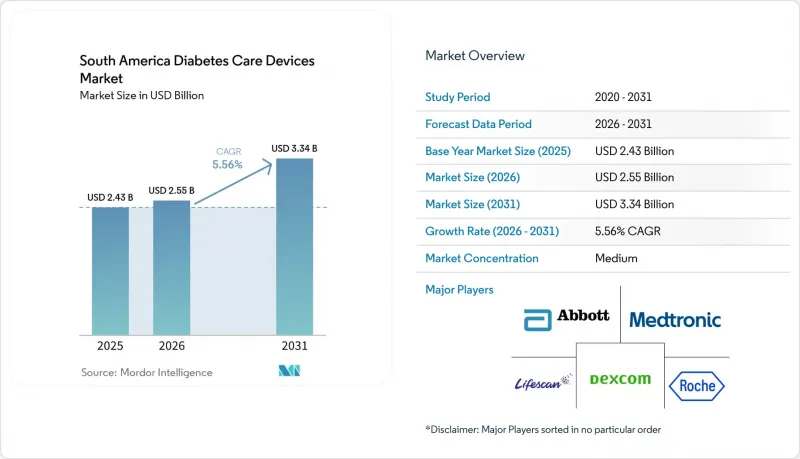
The region had 35.4 million adults living with diabetes in 2024, while 30.4% of those adults remained undiagnosed, leaving a large group outside regular treatment and monitoring pathways. This report is Segmented by Device Type (Monitoring Devices, Management Devices), Diabetes Type (Type 1 Diabetes, Type 2 Diabetes, Gestational & Others), Distribution Channel (Hospital Pharmacies, and More), End-User (Hospital and Clinics, and More), and Country (Brazil, Argentina, Colombia, Chile, Peru, Rest of South America). The Market Forecasts are Provided in Terms of Value (USD).
South America Diabetes Care Devices Market Trends and Insights
Rising Diabetes Prevalence and Diagnosis Rates
The growing number of people living with diabetes provides the basic demand base for the South American diabetes care devices market. The adult diabetes population in South and Central America is projected to rise from 35.4 million in 2024 to 51.5 million by 2050, a 46% increase. Argentina recorded an age-standardized diabetes prevalence of 14% in 2024, followed by Chile at 12.2% and Brazil at 10.6%, supporting demand in markets with more developed private care channels. Gestational diabetes affected 12.5% of pregnancies in the region in 2024, or 967,000 live births, which creates a separate need for monitoring during pregnancy and can increase later awareness of diabetes care. As diagnosis programs reach more people, entry-level glucose meters, strips, lancets, and related support services become more relevant across the South American diabetes care devices market.
Growing Adoption of Continuous and Connected Monitoring
Continuous glucose monitoring is moving beyond specialist use in the leading countries of the South American diabetes care devices market. Abbott launched FreeStyle Libre 2 Plus in Brazil in June 2024 with automatic readings every minute, an 8.2% mean absolute relative difference, and 15-day sensor wear. A 2025 Brazilian study found that flash CGM users on a digital platform were younger than blood glucose meter users, with mean ages of 31.6 years and 36.2 years, respectively. The same study showed that use was concentrated in the higher-income Southeast, which reflects the continued importance of private affordability. Abbott and Medtronic formed a global alliance in August 2024 to link CGM and pump technologies, strengthening the role of interoperable systems in care pathways. These changes support recurring sensor demand and make switching between connected platforms less straightforward for patients and providers.
High Out-of-Pocket Cost and Uneven Reimbursement
Affordability remains a primary constraint on advanced device adoption in the South American diabetes care devices market. Brazilian evidence showed that only 2.5% of flash CGM platform users were located in the lower-income North, while users were concentrated in the Southeast. Brazil's public system covers glucose meters and strips, but most patient groups do not receive public reimbursement for CGM sensors. Imported premium systems are also exposed to currency depreciation, especially in Argentina, where exchange-rate changes can quickly reduce patient affordability. Reimbursement decisions and local purchasing capacity will determine how widely advanced monitoring can move beyond private-pay users.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Home-Based and Remote Diabetes Management
- Public-Health Screening and Diabetes-Program Expansion
- Regulatory Fragmentation and Lengthy Device Registration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Monitoring devices held 61.24% of the South American diabetes care devices market share in 2025. Self-monitoring blood glucose systems, including meters, strips, and lancets, remain the standard approach within Brazil's public procurement system and comparable public networks. Their scale comes from large tenders, familiar prescribing patterns, and the need for low-cost consumables. Continuous glucose monitoring is the fastest-growing device subcategory, with a forecasted CAGR of 6.23% through 2031. New sensor products have made CGM easier to use while retaining clinical accuracy. The South American diabetes care devices market size for monitoring, therefore, remains closely linked to basic products, even as sensor use expands in private care.
Management devices include insulin pumps, disposable pens, reusable pen cartridges, syringes, and jet injectors. Disposable pens and reusable cartridges account for most management-device volume because insulin delivery remains widely needed for insulin-treated patients. Novo Nordisk has manufacturing operations in Brazil that support insulin supply, while Sanofi and Eli Lilly maintain insulin delivery portfolios in the region. Pump adoption starts from a smaller base and is concentrated in specialist centers in Sao Paulo, Buenos Aires, and Santiago.
Type 2 diabetes accounted for 86.33% of demand in 2025 and is projected to grow at a 7.34% CAGR through 2031. This group shapes device volumes in the South American diabetes care devices industry because many patients use strips and meters, while some insulin-treated patients need delivery products. Brazil's November 2024 recommendation to extend insulin analog coverage under SUS can move more Type 2 patients from oral therapy alone toward insulin delivery use. Screening and diagnosis can therefore increase demand for starter monitoring kits and ongoing supplies.
Type 1 diabetes represents a smaller share of patient volume but creates strong demand for CGM sensors, pumps, and closed-loop systems. Gestational diabetes and other conditions also require monitoring when more intensive glycemic control is needed. Gestational diabetes prevalence reached 12.5% in 2024, creating temporary but clinically important device demand during pregnancy.
Complete Report Scope:
- By Device Type
- Monitoring Devices
- Self-Monitoring Blood Glucose (SMBG) Devices
- Glucometers
- Test Strips
- Lancets
- Continuous Glucose Monitoring (CGM) Devices
- Sensors
- Durables (Receivers & Transmitters)
- Self-Monitoring Blood Glucose (SMBG) Devices
- Management Devices
- Insulin Pump Devices
- Insulin Disposable Pens
- Insulin Cartridges in Reusable Pens
- Insulin Syringes & Jet Injectors
- Monitoring Devices
- By Diabetes Type
- Type 1 Diabetes
- Type 2 Diabetes
- Gestational Diabetes & Others
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Other Distribution Channels
- By End-User
- Hospitals and Clinics
- Homecare Settings
- Other End-Users
- By Country
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
List of Companies Covered in this Report:
- Abbott Laboratories
- Arkray
- Ascensia Diabetes Care Holdings AG
- B. Braun
- Beckton Dickinson
- Dexcom
- Eli Lilly and Company
- Roche
- Insulet
- I-Sens
- Lifescan
- Medtronic
- Nipro
- Novo Nordisk
- OMRON
- Sanofi
- Senseonics
- Tandem Diabetes Care
- Terumo
- Ypsomed
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Diabetes Prevalence and Diagnosis Rates
- 4.2.2 Growing Adoption of Continuous and Connected Monitoring
- 4.2.3 Expansion of Home-Based and Remote Diabetes Management
- 4.2.4 Public-Health Screening and Diabetes-Program Expansion
- 4.2.5 Interoperability Between CGM, Smart Pens, Pumps, and Mobile Platforms
- 4.2.6 Increasing Adoption of CGM Among Pediatric and Type 1 Diabetes Patients
- 4.3 Market Restraints
- 4.3.1 High Out-of-Pocket Cost and Uneven Reimbursement
- 4.3.2 Regulatory Fragmentation and Lengthy Device Registration
- 4.3.3 Limited Specialist, Technical-Support, and Connectivity Coverage Outside Major Cities
- 4.3.4 Dependence on Imported Diabetes Care Devices and Currency Volatility
- 4.4 Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Device Type
- 5.1.1 Monitoring Devices
- 5.1.1.1 Self-Monitoring Blood Glucose (SMBG) Devices
- 5.1.1.1.1 Glucometers
- 5.1.1.1.2 Test Strips
- 5.1.1.1.3 Lancets
- 5.1.1.2 Continuous Glucose Monitoring (CGM) Devices
- 5.1.1.2.1 Sensors
- 5.1.1.2.2 Durables (Receivers & Transmitters)
- 5.1.1.1 Self-Monitoring Blood Glucose (SMBG) Devices
- 5.1.2 Management Devices
- 5.1.2.1 Insulin Pump Devices
- 5.1.2.2 Insulin Disposable Pens
- 5.1.2.3 Insulin Cartridges in Reusable Pens
- 5.1.2.4 Insulin Syringes & Jet Injectors
- 5.1.1 Monitoring Devices
- 5.2 By Diabetes Type
- 5.2.1 Type 1 Diabetes
- 5.2.2 Type 2 Diabetes
- 5.2.3 Gestational Diabetes & Others
- 5.3 By Distribution Channel
- 5.3.1 Hospital Pharmacies
- 5.3.2 Retail Pharmacies
- 5.3.3 Online Pharmacies
- 5.3.4 Other Distribution Channels
- 5.4 By End-User
- 5.4.1 Hospitals and Clinics
- 5.4.2 Homecare Settings
- 5.4.3 Other End-Users
- 5.5 By Country
- 5.5.1 Brazil
- 5.5.2 Argentina
- 5.5.3 Colombia
- 5.5.4 Chile
- 5.5.5 Peru
- 5.5.6 Rest of South America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 ARKRAY, Inc.
- 6.3.3 Ascensia Diabetes Care Holdings AG
- 6.3.4 B. Braun Melsungen AG
- 6.3.5 Becton, Dickinson and Company
- 6.3.6 DexCom, Inc.
- 6.3.7 Eli Lilly and Company
- 6.3.8 F. Hoffmann-La Roche Ltd.
- 6.3.9 Insulet Corporation
- 6.3.10 i-SENS, Inc.
- 6.3.11 LifeScan Inc.
- 6.3.12 Medtronic PLC
- 6.3.13 Nipro Corporation
- 6.3.14 Novo Nordisk A/S
- 6.3.15 Omron Healthcare, Inc.
- 6.3.16 Sanofi
- 6.3.17 Senseonics Holdings, Inc.
- 6.3.18 Tandem Diabetes Care, Inc.
- 6.3.19 Terumo Corporation
- 6.3.20 Ypsomed Holding AG
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

