PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116373

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116373
Europe Automotive Engine Oils - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the european automotive engine oils market size in 2026 is estimated at 2.6 billion liters, growing from 2025 value of 2.59 billion liters with 2031 projections showing 2.65 billion liters, growing at 0.35% CAGR over 2026-2031.
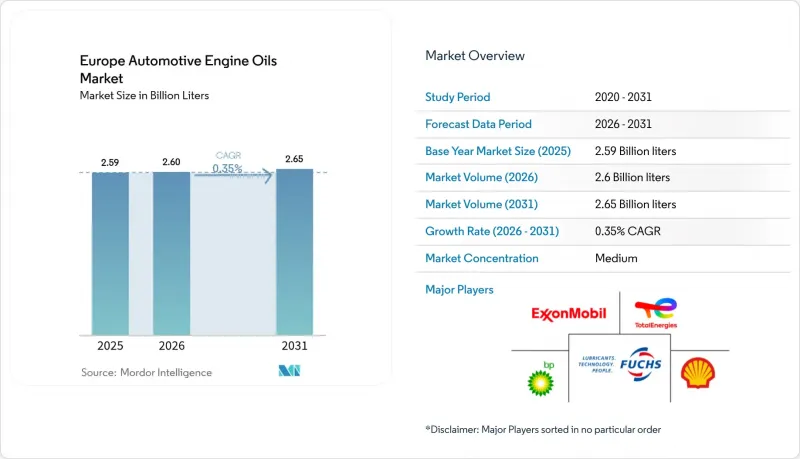
This report is Segmented by Product Type (Passenger Car Motor Oil, Heavy Duty Motor Oil, and Motorcycle Engine Oil), Base Stock (Mineral, Synthetic, Semi-Synthetic, and Bio-Based), and Geography (Germany, United Kingdom, France, Italy, Spain, Nordic Countries, Russia, and Rest of Europe). Market Forecasts are Provided in Terms of Volume (Litres).
Europe Automotive Engine Oils Market Trends and Insights
European Union CO2 and Fuel-Economy Targets Push Low-Viscosity Formulations
Upcoming fleetwide CO2 caps compel automakers to specify ultra-thin 0W-20 and even 0W-16 grades that deliver measurable fuel-efficiency gains. Volkswagen shifted its entire TSI engine family to 0W-20 service fills in 2025, prompting aftermarket workshops to stock advanced synthetics with high Group III and poly-alpha-olefin content. Low-viscosity grades command 20-30% price premiums because heavier 5W-30 and 10W-40 oils cannot meet viscosity-temperature targets. The mandate boosts Europe automotive engine oils market demand for high-performance base stocks and premium additive packages while commoditizing legacy grades.
Aging ICE Vehicle Parc Sustains Oil-Change Volumes
The average German passenger car age climbed to 10.1 years in 2024, and similar trends appear across France, Italy, and Spain. Older engines require more frequent oil changes and tolerate conventional or semi-synthetic formulations, offsetting volume lost to electrification. Independent workshops capture a larger share of this replacement business as vehicles exit warranty coverage, thereby maintaining baseline lubricant demand in the Europe automotive engine oils market even as new-car electrification rises.
Accelerating BEV Penetration Shrinks Long-Term ICE Pool
Battery-electric vehicles captured 14.6% of European new-car registrations in 2024, and the share could exceed 30% of the rolling fleet by 2035. Nordic markets already display lubricant volume contraction, signaling future pressure for suppliers heavily exposed to internal-combustion demand. The contraction risk looms largest for the Europe automotive engine oils market participants lacking diversification into electrification-adjacent fluids.
Other drivers and restraints analyzed in the detailed report include:
- OEM Specification Proliferation Drives Premium Synthetics
- Waste-Oil Regeneration Quotas Spur Re-Refined Base-Oil Demand
- Volatile Crude and Additive Supply Costs Pressure Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger Car Motor Oil held 60.72% of the European automotive engine oils market in 2025. PCMO volumes benefit from a 250 million-unit passenger car fleet, yet growth remains flat as fleet electrification offsets miles-driven recovery. Premium fully synthetic 0W-20 and 0W-16 formulations extend drain intervals to 30,000 kilometers, allowing OEMs to advertise lower ownership costs while still protecting engines. Independent garages lead distribution, but authorized dealer channels retain high-margin factory-fill business where OEM approvals remain non-negotiable.
Motorcycle Engine Oil is expected to post the fastest 0.92% CAGR through 2031. Urban congestion, last-mile delivery, and recreational riding boost two-wheeler demand, especially in Italy, Spain, and France. High-performance motorcycles require JASO MA2 oils with shear stability, wet-clutch compatibility, and thermal resilience, driving premium pricing. Europe automotive engine oils market participants that cultivate dealer networks and sponsor racing events capture brand loyalty among enthusiasts who accept higher per-liter prices.
Complete Report Scope:
- By Product Type
- Passenger Car Motor Oil (PCMO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Heavy Duty Motor Oil (HDMO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Motorcycle Engine Oil (MCO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Passenger Car Motor Oil (PCMO)
- By Base Stock
- Mineral
- Synthetic
- Semi-Synthetic
- Bio-Based
- By Geography
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordic Countries
- Russia
- Rest of Europe
List of Companies Covered in this Report:
- ADDINOL
- BP plc
- Chevron Corporation
- Eni S.p.A.
- Exxon Mobil Corporation
- FUCHS
- Gazprom
- Idemitsu Kosan Co., Ltd.
- LIQUI MOLY
- LUKOIL
- Millers Oils LTD
- MOTOREX
- Motul
- Neste
- PETRONAS Lubricants International
- Phillips 66 Company.
- Ravensberger Schmierstoffvertrieb GmbH
- Repsol
- Shell plc
- TotalEnergies
- Valvoline Global Operations
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 European Union CO2 and fuel-economy targets push low-viscosity formulations
- 4.2.2 Aging ICE vehicle parc sustains oil-change volumes
- 4.2.3 OEM specification proliferation drives premium synthetics
- 4.2.4 Hybrid-vehicle growth needs low-ash, low-viscosity oils
- 4.2.5 Waste-oil regeneration quotas spur re-refined base-oil demand
- 4.3 Market Restraints
- 4.3.1 Accelerating BEV penetration shrinks long-term ICE pool
- 4.3.2 Volatile crude and additive supply costs pressure margins
- 4.3.3 OEM lifetime-fill and sensors extend drain intervals
- 4.4 Value Chain and Distribution Channel Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Industry Rivalry
- 4.6 Regulatory Framework
- 4.7 Automotive Industry Trends
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Passenger Car Motor Oil (PCMO)
- 5.1.1.1 0W-XX
- 5.1.1.2 5W-XX
- 5.1.1.3 10W-XX
- 5.1.1.4 15W-XX
- 5.1.1.5 Monogrades
- 5.1.1.6 Other Grades
- 5.1.2 Heavy Duty Motor Oil (HDMO)
- 5.1.2.1 0W-XX
- 5.1.2.2 5W-XX
- 5.1.2.3 10W-XX
- 5.1.2.4 15W-XX
- 5.1.2.5 Monogrades
- 5.1.2.6 Other Grades
- 5.1.3 Motorcycle Engine Oil (MCO)
- 5.1.3.1 0W-XX
- 5.1.3.2 5W-XX
- 5.1.3.3 10W-XX
- 5.1.3.4 15W-XX
- 5.1.3.5 Monogrades
- 5.1.3.6 Other Grades
- 5.1.1 Passenger Car Motor Oil (PCMO)
- 5.2 By Base Stock
- 5.2.1 Mineral
- 5.2.2 Synthetic
- 5.2.3 Semi-Synthetic
- 5.2.4 Bio-Based
- 5.3 By Geography
- 5.3.1 Germany
- 5.3.2 United Kingdom
- 5.3.3 France
- 5.3.4 Italy
- 5.3.5 Spain
- 5.3.6 Nordic Countries
- 5.3.7 Russia
- 5.3.8 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Production Capacity, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ADDINOL
- 6.4.2 BP plc
- 6.4.3 Chevron Corporation
- 6.4.4 Eni S.p.A.
- 6.4.5 Exxon Mobil Corporation
- 6.4.6 FUCHS
- 6.4.7 Gazprom
- 6.4.8 Idemitsu Kosan Co., Ltd.
- 6.4.9 LIQUI MOLY
- 6.4.10 LUKOIL
- 6.4.11 Millers Oils LTD
- 6.4.12 MOTOREX
- 6.4.13 Motul
- 6.4.14 Neste
- 6.4.15 PETRONAS Lubricants International
- 6.4.16 Phillips 66 Company.
- 6.4.17 Ravensberger Schmierstoffvertrieb GmbH
- 6.4.18 Repsol
- 6.4.19 Shell plc
- 6.4.20 TotalEnergies
- 6.4.21 Valvoline Global Operations
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
8 Key Strategic Questions for CEOs

