PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116389

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116389
Vietnam Automotive Engine Oils - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Vietnam automotive engine oils market size is expected to grow from 145.66 million liters in 2025 to 152.34 million liters in 2026 and is forecast to reach 190.71 million liters by 2031 at 4.59% CAGR over 2026-2031.
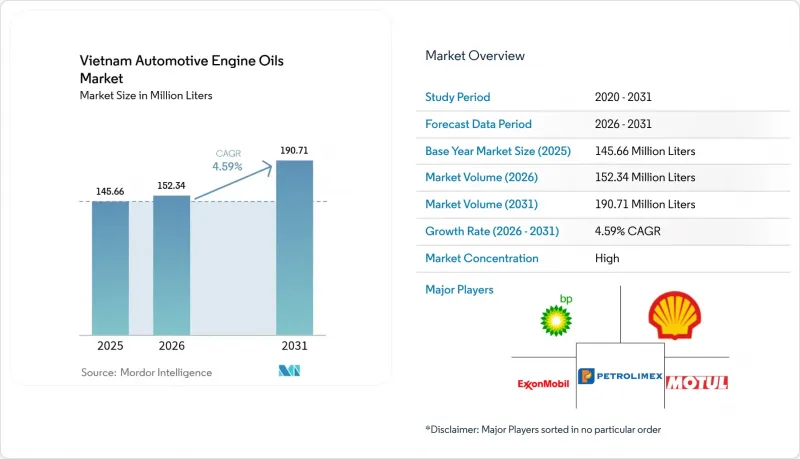
This report is Segmented by Product Type (Passenger Car Motor Oil, Heavy Duty Motor Oil, and Motorcycle Engine Oil), Base Stock (Mineral, Synthetic, Semi-Synthetic, Bio-Based). The Market Forecasts are Provided in Terms of Volume (Liters).
Vietnam Automotive Engine Oils Market Trends and Insights
Surging Motorcycle Parc and Maintenance Frequency
More than 73 million gasoline two-wheelers require oil changes every 3,000-5,000 kilometers, compared with 10,000-15,000 kilometers for cars, so lubricant throughput remains high even as new bike sales soften. Honda's share across motorcycle sales drives standardized servicing, helping branded oils secure repeat volumes. The motorcycle segment generated a significant percent of national lubricant demand in 2024, underscoring its weight in overall consumption. Rural ownership continues to rise thanks to upgraded roads and higher disposable incomes, expanding the replacement cycle. Ageing bikes in peripheral provinces further elevate change frequency, offsetting modest electrification in core cities.
Government Incentives for Domestic Oil Blending Capacity
Authorities encourage local blending to curb import reliance, exemplified by Fuchs' EUR 9 million (USD 10.2 million) plant in Ba Ria-Vung Tau and the USD 1.2 billion Dung Quat refinery upgrade to 7.5 million tons per year. Fiscal perks, streamlined licensing, and land-use support cut operating costs for blenders, letting them target mainstream price points with made-in-Vietnam labels. Partnerships such as ongoing Aramco-Petrolimex talks hint at deeper downstream collaboration that could seed ASEAN export potential. Domestic capacity also helps cushion distributors against freight volatility and foreign-exchange swings, a structural upside for independent retailers.
Growing EV Penetration in Urban Centres
Government targets of 350,000 EVs by 2030 and PVOIL's rollout of 369 charging points begin to erode combustion-engine lubricant volumes, especially among taxi and ride-hail fleets. Two million electric motorcycles already circulate, advancing 30-35% annually, although from a low base. E-fluids for gearboxes and thermal management partially offset the lost engine oil, but lack a comparable volume density. Outside Hanoi and Ho Chi Minh City, limited charging and rural duty cycles preserve internal-combustion dominance until infrastructure matures. Hence, the headwind remains gradual, yet strategic investors already price this shift into long-range capacity plans.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Low-Viscosity Synthetic Grades for Fuel Economy
- E-Commerce Expansion in Lubricant Retailing
- Counterfeit / Grey-Market Engine Oils
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger Car Motor Oil retained a 61.45% slice of the Vietnam automotive engine oils market share in 2025 as the passenger-vehicle fleet rose to 510,000 units. Motorcycle Engine Oil, however, posts the quickest clip at 4.78% CAGR to 2031, propelled by 73 million active bikes requiring changes every 3,000-5,000 kilometres. Heavy-Duty Motor Oil services freight trucks on arterial corridors linking Ho Chi Minh City and Hanoi to export ports, reinforcing steady baseline volume.
The Vietnam automotive engine oils market benefits from 1.6% growth in motorcycle imports to 464,194 units through February 2025, while passenger car imports grew to 172,240 units in 2024. Honda's dominance simplifies compatibility for suppliers, whereas car OEM fragmentation widens product portfolios. High-performance lines such as Motul 300V Road Racing and Yamaha's anti-counterfeit Yamalube enhance segment segmentation and capture price premium.
Complete Report Scope:
- By Product Type
- Passenger Car Motor Oil (PCMO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Heavy Duty Motor Oil (HDMO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Motorcycle Engine Oil (MCO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Passenger Car Motor Oil (PCMO)
- By Base Stock
- Mineral
- Synthetic
- Semi-Synthetic
List of Companies Covered in this Report:
- AP SAIGON PETRO
- BP p.l.c.
- Chevron Corporation
- Exxon Mobil Corporation
- FUCHS
- GS Caltex Corporation
- Gulf Oil International Ltd.
- Idemitsu Lubricants Vietnam
- Mekong Petrochemical Jsc
- Motul Vietnam (Vilube)
- Petrolimex (PLX)
- PETRONAS Lubricants International
- PVOIL
- Repsol Vietnam
- Shell Plc
- TotalEnergies
- Wolf Oil Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Motorcycle Parc and Maintenance Frequency
- 4.2.2 Government Incentives for Domestic Oil Blending Capacity
- 4.2.3 Shift Toward Low-Viscosity Synthetic Grades for Fuel Economy
- 4.2.4 E-Commerce Expansion in Lubricant Retailing
- 4.2.5 OEM Factory-Fill Localisation Partnerships
- 4.3 Market Restraints
- 4.3.1 Growing EV Penetration in Urban Centres
- 4.3.2 Counterfeit / Grey-Market Engine Oils
- 4.3.3 Crude-Price Volatility Squeezing Blender Margins
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Passenger Car Motor Oil (PCMO)
- 5.1.1.1 0W-XX
- 5.1.1.2 5W-XX
- 5.1.1.3 10W-XX
- 5.1.1.4 15W-XX
- 5.1.1.5 Monogrades
- 5.1.1.6 Other Grades
- 5.1.2 Heavy Duty Motor Oil (HDMO)
- 5.1.2.1 0W-XX
- 5.1.2.2 5W-XX
- 5.1.2.3 10W-XX
- 5.1.2.4 15W-XX
- 5.1.2.5 Monogrades
- 5.1.2.6 Other Grades
- 5.1.3 Motorcycle Engine Oil (MCO)
- 5.1.3.1 0W-XX
- 5.1.3.2 5W-XX
- 5.1.3.3 10W-XX
- 5.1.3.4 15W-XX
- 5.1.3.5 Monogrades
- 5.1.3.6 Other Grades
- 5.1.1 Passenger Car Motor Oil (PCMO)
- 5.2 By Base Stock
- 5.2.1 Mineral
- 5.2.2 Synthetic
- 5.2.3 Semi-Synthetic
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 AP SAIGON PETRO
- 6.4.2 BP p.l.c.
- 6.4.3 Chevron Corporation
- 6.4.4 Exxon Mobil Corporation
- 6.4.5 FUCHS
- 6.4.6 GS Caltex Corporation
- 6.4.7 Gulf Oil International Ltd.
- 6.4.8 Idemitsu Lubricants Vietnam
- 6.4.9 Mekong Petrochemical Jsc
- 6.4.10 Motul Vietnam (Vilube)
- 6.4.11 Petrolimex (PLX)
- 6.4.12 PETRONAS Lubricants International
- 6.4.13 PVOIL
- 6.4.14 Repsol Vietnam
- 6.4.15 Shell Plc
- 6.4.16 TotalEnergies
- 6.4.17 Wolf Oil Corporation
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
8 Key Strategic Questions for CEOs

