PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116386

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116386
Indonesia Automotive Engine Oils - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the indonesian automotive engine oils market size was valued at 371.28 million liters in 2025 and estimated to grow from 374.88 million liters in 2026 to reach 393.42 million liters by 2031, at a CAGR of 0.97% during the forecast period (2026-2031).
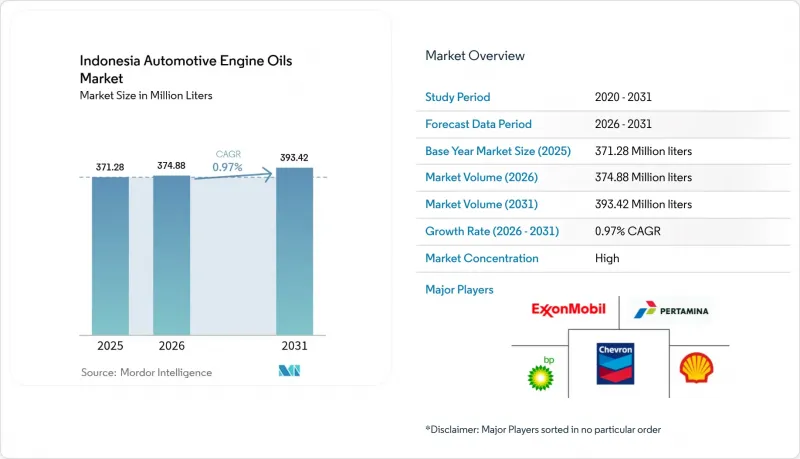
This report is Segmented by Resin Type (Passenger Car Motor Oil, Monogrades, Heavy Duty Motor Oil, and Motorcycle Engine Oil (MCO)), Base Stock (Mineral, Synthetic, Semi-Synthetic, and Bio-Based). The Market Forecasts are Provided in Terms of Volume (Litres).
Indonesia Automotive Engine Oils Market Trends and Insights
Rapid Growth of Vehicle Parc Drives Base Demand
Indonesia's 138 million-unit vehicle population, including 113 million motorcycles, produces an unmatched aftermarket lubricant opportunity. Government tax incentives propelled car sales to 81,230 units in February 2022, a 65% year-on-year jump. More cars and two-wheelers translate directly into higher lubricant change frequencies, while new toll roads lengthen average kilometers traveled. These factors shift the Indonesian automotive engine oil market from pure replacement to incremental volume expansion as new vehicle additions consistently outrun fleet retirements.
OEM Specifications Shift Toward Advanced Formulations
Global and local automakers are standardizing on API SP or higher for gasoline engines and advocating 0W or 5W grades to optimize thermal management and fuel economy. Motorcycle applications lag at API SN but are expected to follow by 2027. Motul and other premium brands already promote 10W-30 and 10W-40 synthetics for future-proofing against tighter emission norms. Suppliers enjoying early-mover advantage in synthetic technology can achieve double-digit margin premiums while educating workshops on viscosity migration. Consumers gravitate toward better cold-start protection and extended service intervals, accelerating the premiumization of the Indonesia automotive engine oil market.
Lengthening Drain Intervals Reduce Consumption Frequency
Synthetic oils support 10,000-kilometer service intervals versus 5,000 kilometers for conventional blends. Newer low-cost green cars employ tighter tolerances and smaller sumps that cut per-service volumes. Fleet managers favor higher-priced synthetics because lifetime cost per kilometer falls, trimming absolute liters consumed even as revenue per liter rises. Motorcycles adopt improved circulation that extends oil life, yet congestion-induced stop-start driving partly offsets the interval expansion.
Other drivers and restraints analyzed in the detailed report include:
- Rising Motorcycle Ownership Sustains Volume Growth
- Government Incentives Accelerate Technology Adoption
- Electric Two-Wheelers Introduce Long-Term Displacement Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The Indonesia automotive engine oil market size for passenger car motor oil accounted for 63.62% of the total volume in 2025. API SP upgrades and 0W-20 viscosity adoption underpin premiumization. OEM factory-fill contracts provide early volume security and brand loyalty that extend into the aftermarket. Heavy-duty motor oil serves logistics and agriculture, with B40-ready formulations becoming a prerequisite.
Motorcycle engine oil volume is projected to climb at a 1.14% CAGR through 2031. Continuous city riding elevates lubricant stress, supporting higher change frequencies. JASO MB specifications for automatic clutch designs create differentiation opportunities, illustrated by Shell Advance City Scooter's full-synthetic launch in June 2025. As disposable income rises, riders shift from mineral 20W-50 to semi-synthetic 10W-40, lifting average revenue per liter.
Complete Report Scope:
- By Product Type
- Passenger Car Motor Oil (PCMO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Heavy Duty Motor Oil (HDMO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Motorcycle Engine Oil (MCO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Passenger Car Motor Oil (PCMO)
- By Base Stock
- Mineral
- Synthetic
- Semi-Synthetic
- Bio-Based
List of Companies Covered in this Report:
- BP plc
- Chevron Corporation
- ENEOS Corporation
- Exxon Mobil Corporation
- FUCHS
- Gazpromneft-Lubricants Ltd.
- Idemitsu Kosan Co. Ltd.
- PETRONAS Lubricants International
- PT Pertamina
- PT Surganya Motor
- PT Wiraswasta Gemilang Indonesia
- Repsol
- Shell plc
- Sinopec Lubricant Co. Ltd.
- TOP 1 Oil Products Company
- TotalEnergies
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid growth of vehicle parc
- 4.2.2 OEM push toward low-viscosity oils
- 4.2.3 Rising motorcycle ownership
- 4.2.4 Government incentives for cleaner engines
- 4.2.5 Ride-hailing fleet expansion
- 4.3 Market Restraints
- 4.3.1 Lengthening drain intervals
- 4.3.2 Uptake of electric two-wheelers
- 4.3.3 Counterfeit / adulterated lubricants
- 4.4 Value Chain and Distribution Channel Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Industry Rivalry
- 4.6 Regulatory Framework
- 4.7 Automotive Industry Trends
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Passenger Car Motor Oil (PCMO)
- 5.1.1.1 0W-XX
- 5.1.1.2 5W-XX
- 5.1.1.3 10W-XX
- 5.1.1.4 15W-XX
- 5.1.1.5 Monogrades
- 5.1.1.6 Other Grades
- 5.1.2 Heavy Duty Motor Oil (HDMO)
- 5.1.2.1 0W-XX
- 5.1.2.2 5W-XX
- 5.1.2.3 10W-XX
- 5.1.2.4 15W-XX
- 5.1.2.5 Monogrades
- 5.1.2.6 Other Grades
- 5.1.3 Motorcycle Engine Oil (MCO)
- 5.1.3.1 0W-XX
- 5.1.3.2 5W-XX
- 5.1.3.3 10W-XX
- 5.1.3.4 15W-XX
- 5.1.3.5 Monogrades
- 5.1.3.6 Other Grades
- 5.1.1 Passenger Car Motor Oil (PCMO)
- 5.2 By Base Stock
- 5.2.1 Mineral
- 5.2.2 Synthetic
- 5.2.3 Semi-Synthetic
- 5.2.4 Bio-Based
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Production Capacity, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BP plc
- 6.4.2 Chevron Corporation
- 6.4.3 ENEOS Corporation
- 6.4.4 Exxon Mobil Corporation
- 6.4.5 FUCHS
- 6.4.6 Gazpromneft-Lubricants Ltd.
- 6.4.7 Idemitsu Kosan Co. Ltd.
- 6.4.8 PETRONAS Lubricants International
- 6.4.9 PT Pertamina
- 6.4.10 PT Surganya Motor
- 6.4.11 PT Wiraswasta Gemilang Indonesia
- 6.4.12 Repsol
- 6.4.13 Shell plc
- 6.4.14 Sinopec Lubricant Co. Ltd.
- 6.4.15 TOP 1 Oil Products Company
- 6.4.16 TotalEnergies
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
8 Key Strategic Questions for CEOs

