PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116381

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116381
China Automotive Engine Oils - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the China automotive engine oils market size in 2026 is estimated at 2.9 billion liters, growing from 2025 value of 2.90 billion liters with 2031 projections showing 2.92 billion liters, growing at 0.10% CAGR over 2026-2031.
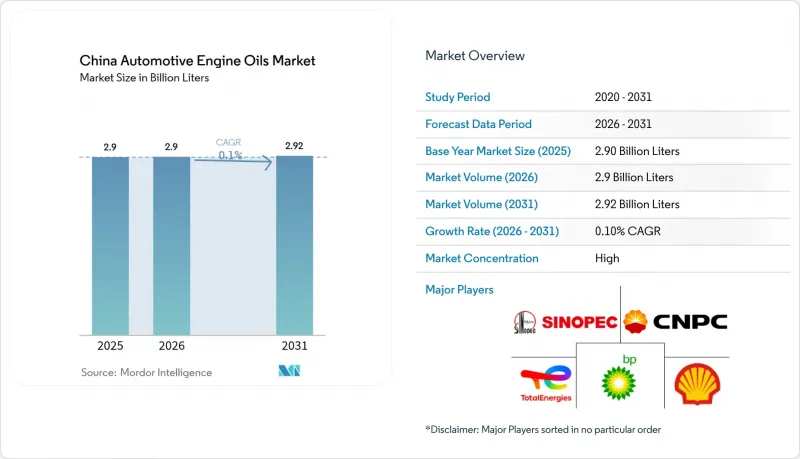
This report is Segmented by Product Type (Passenger Car Motor Oil, Heavy Duty Motor Oil, and Motorcycle Engine Oil), Base Stock (Mineral, Synthetic, Semi-Synthetic, Bio-Based). The Market Forecasts are Provided in Terms of Volume (Liters).
China Automotive Engine Oils Market Trends and Insights
Rising Vehicle Parc & Ageing Fleet
The passenger-car parc continued to expand in 2025, adding a modest but steady flow of replacement demand despite the headline EV surge. Older ICE models dominate Tier 2-3 cities, where households postpone EV upgrades, translating into higher per-vehicle oil consumption and more frequent top-ups. Inland provinces, therefore, offer a multi-year buffer that slows the nationwide volume decline. Scrappage incentives and tighter inspection programs in coastal hubs, however, foreshadow a gradual shift that will ultimately cap this driver's contribution to the China automotive engine oils market.
Stringent China VI-b Emission Norms Driving High-Performance Lubricants
China VI-b standards oblige formulators to cut SAPS levels and deliver fuel-economy-oriented viscosities such as 0W-20 while still protecting after-treatment hardware. Over 1,800 products were relicensed under API SQ/ILSAC GF-7 in the first nine months after the March 2025 start date. Tier 1 cities moved first, triggering a ripple of demand for fully-synthetic and high Group III blends that continues to widen inland. Compliance costs have squeezed small blenders and are accelerating mergers or supply agreements with base-oil majors, a trend reinforcing the concentrated character of the China automotive engine oils market.
Longer OEM Drain Intervals & Oil-Life Monitoring
Mainstream OEMs now quote service intervals at 7,500-8,000 km with fully synthetic 0W-20 and 5W-30 oils, and many premium marques pair that with in-vehicle algorithms that push drains out when operating conditions are mild. Although each sump fill is larger, annual per-car lubricant consumption falls roughly 20% compared with 2020 practices, pressuring the China automotive engine oils market size even as unit prices rise.
Other drivers and restraints analyzed in the detailed report include:
- Turbo GDI Adoption in Passenger Cars Boosting Synthetic Demand
- Expansion of IAM Workshops & E-Commerce Retail
- Crack-Down on Counterfeit Oils Causes Grey-Channel Destocking
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger car motor oil contributed 58.10% of 2025 volume, confirming its historical role at the center of the China automotive engine oils market. A broad viscosity spread-from legacy 10W-40 for older compact cars to modern 0W-20 for turbo GDI models-keeps the category diverse. The Chinese ride-hailing fleet still relies on ICE sedans and therefore underpins baseline PCMO demand in urban cores. Nonetheless, battery-electric sedans and crossovers account for an ever-larger share of new registrations, chipping away at the internal-combustion aftermarket. Motorcycle engine oil, by contrast, posts a 0.15% CAGR through 2031 thanks to the resilience of two-wheelers in parcel-delivery and rural transport duty cycles.
The heavy-duty motor-oil segment faces twin forces: emission norms that necessitate CK-4 level performance and pilot electrification projects in urban distribution. Range-extender trucks temporarily cushion volumes because they still carry small diesel generators, but pure-electric drayage initiatives in the Pearl River Delta foreshadow future shrinkage. Overall, passenger-car oil will remain the single largest bucket, yet its share will ebb as electrification accelerates and two-wheeler delivery fleets find new momentum in inland regions.
Complete Report Scope:
- By Product Type
- Passenger Car Motor Oil (PCMO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Heavy Duty Motor Oil (HDMO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Motorcycle Engine Oil (MCO)
- 0W-XX
- 5W-XX
- 10W-XX
- 15W-XX
- Monogrades
- Other Grades
- Passenger Car Motor Oil (PCMO)
- By Base Stock
- Mineral
- Synthetic
- Semi-Synthetic
- Bio-Based
List of Companies Covered in this Report:
- BP p.l.c.
- Chevron Corporation
- China National Petroleum Corporation
- China Petrochemical Corporation
- ExxonMobil Corporation
- FUCHS
- HF Sinclair Corporation
- Idemitsu Kosan Co., Ltd.
- Jiangsu Lopal Tech Co., Ltd.
- JX Nippon Oil & Energy Corp. (ENEOS)
- Lubrizol Corp. (Additive Vendor)
- Qingdao COPTON Technology Co., Ltd.
- Saudi Arabian Oil Co.
- Shell plc
- SK ZIC
- Tongyi Petrochemical Co., Ltd.
- TotalEnergies
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising vehicle parc and ageing fleet
- 4.2.2 Stringent China VI-b emission norms driving high-performance lubricants
- 4.2.3 Turbo GDI adoption in passenger cars boosting synthetic demand
- 4.2.4 Expansion of IAM workshops and e-commerce lubricant retail
- 4.2.5 Hybrid range-extender trucks needing low-viscosity diesel oils
- 4.3 Market Restraints
- 4.3.1 Surging EV penetration shrinking ICE lubricant pool
- 4.3.2 Longer OEM drain intervals and oil-life monitoring
- 4.3.3 Crack-down on counterfeit oils causes grey-channel destocking
- 4.4 Value Chain and Distribution Channel Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Industry Rivalry
- 4.6 Regulatory Framework
- 4.7 Automotive Industry Trends
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Passenger Car Motor Oil (PCMO)
- 5.1.1.1 0W-XX
- 5.1.1.2 5W-XX
- 5.1.1.3 10W-XX
- 5.1.1.4 15W-XX
- 5.1.1.5 Monogrades
- 5.1.1.6 Other Grades
- 5.1.2 Heavy Duty Motor Oil (HDMO)
- 5.1.2.1 0W-XX
- 5.1.2.2 5W-XX
- 5.1.2.3 10W-XX
- 5.1.2.4 15W-XX
- 5.1.2.5 Monogrades
- 5.1.2.6 Other Grades
- 5.1.3 Motorcycle Engine Oil (MCO)
- 5.1.3.1 0W-XX
- 5.1.3.2 5W-XX
- 5.1.3.3 10W-XX
- 5.1.3.4 15W-XX
- 5.1.3.5 Monogrades
- 5.1.3.6 Other Grades
- 5.1.1 Passenger Car Motor Oil (PCMO)
- 5.2 By Base Stock
- 5.2.1 Mineral
- 5.2.2 Synthetic
- 5.2.3 Semi-Synthetic
- 5.2.4 Bio-Based
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)**/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Production Capacity, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BP p.l.c.
- 6.4.2 Chevron Corporation
- 6.4.3 China National Petroleum Corporation
- 6.4.4 China Petrochemical Corporation
- 6.4.5 ExxonMobil Corporation
- 6.4.6 FUCHS
- 6.4.7 HF Sinclair Corporation
- 6.4.8 Idemitsu Kosan Co., Ltd.
- 6.4.9 Jiangsu Lopal Tech Co., Ltd.
- 6.4.10 JX Nippon Oil & Energy Corp. (ENEOS)
- 6.4.11 Lubrizol Corp. (Additive Vendor)
- 6.4.12 Qingdao COPTON Technology Co., Ltd.
- 6.4.13 Saudi Arabian Oil Co.
- 6.4.14 Shell plc
- 6.4.15 SK ZIC
- 6.4.16 Tongyi Petrochemical Co., Ltd.
- 6.4.17 TotalEnergies
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
8 Key Strategic Questions for CEOs

